Everything about crypto cards in one place: what they are, the types that exist, and independent rankings built on verified fees, custody analysis, and onchain-measured spending.
A crypto card is a Visa or Mastercard-branded payment card that lets you spend cryptocurrency, including Bitcoin, Ethereum, stablecoins like USDC and USDT, and dozens of other digital assets, at merchant terminals and online checkouts worldwide.
When you tap or swipe, the card converts your crypto into the local fiat currency in real time. The merchant receives regular dollars, euros, or pounds, while you get the convenience of spending crypto almost as easily as spending from a bank account.
Every fee and reward rate is sourced from official issuer documentation and checked against our methodology.
What Types of Crypto Cards Are There?
Crypto cards divide along five real lines: how the card pays, what form it takes, who holds your crypto, what it pays you back, and what it costs to run. Add where you live and who you are, and every card on this site sits somewhere on this map. Each branch below has its own full ranking page.
How the Card Pays: Debit, Prepaid, or Credit-Backed
The first divide is where the money comes from at the moment of purchase.
Crypto Debit Cards
The most common type. You fund a balance with crypto, and the card debits it in real time at the till, converting to fiat as you pay. Our debit vs prepaid guide covers where the line sits.
A fiat balance you load from crypto in advance, so conversion happens at top-up rather than at purchase. That makes spending predictable, at the cost of an extra loading step.
Instead of selling crypto, these draw a credit line against your holdings as collateral, so spending does not trigger a taxable disposal. In high-tax countries this saves more than any cashback rate earns.
A funding choice more than a card type: cards built around USDC and USDT balances. Near-zero capital gains per swipe makes this the tax-cleanest way to run any crypto card. See the stablecoin cards ranking.
The third divide decides what happens if the company behind your card fails.
Self-Custody Crypto Cards
Your keys, your crypto, until the second the payment settles. This removes exchange-custody failure from the risk model, but smart-contract, bridge, stablecoin, and chain risks remain. MetaMask, Ledger, and xPlace anchor the live category. Gnosis Pay closes its direct consumer card on December 20, while Payy's confirmed exploit remains under third-party validation. The full list lives on our self-custody cards ranking.
Custodial cards, the majority, hold your balance on the issuer's books like an exchange account does: smoother onboarding and simpler recovery, in exchange for counterparty risk. A few hybrids split the difference by holding funds with a regulated third-party custodian.
What the Card Pays You: Rewards and Perks
The fourth divide is the payback, and the payback comes in four different currencies.
Cashback Crypto Cards
The reward maximizers. The headline rate is rarely the real rate: caps, FX fees, per-payment charges, and token-price risk decide what you actually keep. Our cashback cards ranking is built on net rates, not headlines.
Airdrop and Points Cards
Cards that pay in points or pre-token rewards on top of, or instead of, cashback: a bet on a future token event, speculative by design. The airdrop cards page tracks which programs are live.
Perk
What it means
Full page
Staking boosts
Higher reward tiers unlocked by staking the issuer's token
Availability decides everything before rewards even enter the picture: a card that does not serve your country ranks nowhere for you. We maintain crypto card guides for 108 countries, each with a localized ranking, tax treatment, and funding routes.
Choosing the Best Crypto Card for You
Best means different things depending on who is asking. A traveler chasing 0% FX, a holder who refuses custodians, and a cashback maximizer would each rank the same cards in a different order, which is exactly what the type pages above are for.
The ranking below is our best-overall list. It is not sorted by headline cashback. We compare the net annual value after fees and reward caps, then weigh country coverage, custody and protocol risk, funding friction, app usability, and payment reliability.
A card moves down when a rate cut or cap weakens its ordinary-user return, even if its advertised maximum still looks high. Narrow availability also limits a card's place on this global list. A shutdown removes a product from new-user consideration, while an unresolved security incident can keep an otherwise distinctive card outside the ranking until its impact is clear. Country and use-case pages can therefore produce a different order from this global list.
For power users, the Tria Signature Card is the high-utility tier. At $109/year, the 15% APY on self-custodial assets covers the fee at modest balances. The 4.5% cashback applies to the first $1,000 of monthly spend (1% above that), so it suits moderate spenders who want to keep their own keys while earning high yield.
Why it ranks here
4.5% cashback (on the first $1,000/month, then 1%) on a self-custodial card is a combination almost nobody else offers. The $109 annual fee pays for itself at around $227/month in spending. Account abstraction means you get self-custody without managing seed phrases.
Watch out
Non-USD spend carries 1% FX plus a 0.5% per-payment fee, trimming the net rate. The Premium tier ($250/yr, 6% on the first $2,000/month then 1%) exists but the Signature is the better risk-adjusted pick for most people. If your monthly spend is under $227, the annual fee eats into the value.
The Plasma One Core Card sits between Lite and Platinum. $199 annual fee, or a 20,000 XPL twelve-month lock instead. It earns 3% base and 5% AI-spend cashback in XPL, rebates up to $8/month toward ChatGPT Go, and earns up to 5% variable vault yield. Best for AI-heavy spenders who use the rebate and spend enough to recover the fee.
Why it ranks here
The strongest all-rounder in Plasma's new three-tier lineup. It is a self-custodial Visa that pays 3% on the first $1,000 of monthly spend, with AI purchases earning up to 5% (5% to $250/month, then 4% to $500), all in XPL, and it rebates up to $8/month toward ChatGPT Go when you pay with the card. Idle stablecoin balance earns up to 5% in the in-app Earn vault; the tier costs $199/year or a 20,000 XPL twelve-month lock. We tested the lineup hands-on, including the per-purchase fee breakdown the app now shows before you confirm a payment.
Watch out
Cashback pays in XPL, so a headline rate only holds if the token does while you hold it. Payouts land weekly, on Thursdays, which shortens that exposure but does not remove it. Both the base and AI rates step down by monthly spend band (base tapers above $1,000; AI is 5% only on the first $250), so the value is real mainly if you route AI subscriptions and steady everyday spend through it. Non-USD spend carries a 0.5% FX fee.
+3% base cashback with a stepped 5% on AI spend (5% to $250/month, then 4% to $500), paid in XPL
+ChatGPT Go rebate: up to $8/month (~$96/year) reimbursed in USD when you pay with the card
+Up to 5% variable yield on idle stablecoin balance via the Earn vault
+Reduced fees and priority support versus the free Lite tier
Option 3
3. ether.fi Core Card
3% Back on the First $2,000 Each Month, No Stake Required
The ether.fi Core Card is the free entry to ether.fi Cash. It earns 3%% cashback on the first $2,000 each month, carries a Free mandatory annual fee, and includes one virtual card plus a physical card with shipping charged.
Why it ranks here
Free card, 3% cashback, and you can borrow against staked ETH instead of selling it. That means no taxable disposal event in most jurisdictions. The restaking yield adds passive income on top of card rewards.
Watch out
The value case is strongest if you already hold ETH and understand collateralized spending. If you just want a simple card to load with stablecoins and spend, the DeFi-native setup adds complexity you may not need.
+3% cashback on the first $2,000 monthly spend band
+No annual fee or qualification threshold
+Free physical card, with shipping charged
+Lounge access, Visa concierge, and up to $10,000 account protection
The COCA Visa Card packs 8% cashback, 0% FX, 5% APY, and 50% subscription rebates into a single non-custodial wallet. Earning is uncapped, but withdrawing rewards is metered by a Monthly Claim Capacity of $15 to $350 depending on tier, so heavy spenders should size their tier around what they can actually extract. Six tiers from Starter (free) to Elite (stake 30K COCA) with 30-day cooldown to unstake. Card issued by Wirex with personal IBAN and broad country coverage.
Why it ranks here
Up to 8% cashback ceiling, 50% off subscriptions like ChatGPT and Netflix (from Standard tier), a personal IBAN, and a smart-wallet setup that keeps you in control. The feature density per dollar is hard to beat.
Watch out
The higher cashback tiers require staking COCA tokens (locked during membership, 30-day cooldown), and the subscription rebates start at Standard (300 COCA). The free Starter tier is much thinner. The value scales with how far up the tier ladder you go.
+1% to 8% stablecoin cashback by tier, with no limit on how much you can earn
+0% FX fees, $0 annual fee, $200/month free ATM withdrawals
The K Card is KAST's free Standard tier entry point. It earns 1.5% USD cashback on the first $2,000 of spend per month (roughly $30/mo at the cap). Cashback unlocks after a 14-day timelock and applies to your next card purchase only. KAST replaced the previous $MOVE cashback program with this USD cashback model in May 2026.
Why it ranks here
1.5% USD cashback on the first $2,000/month. Card takes 2 minutes to set up via Sumsub (ID + selfie). Instant virtual card, 170+ countries. The speed from signup to first purchase is among the fastest in crypto cards.
Watch out
Cashback is in-app credit toward your next card spend (14-day hold), not cash you can withdraw. The 0.5-1.75% FX fee on non-USD spending can wipe out the 1.5% cashback at the worst FX-pair end. Above the $2K/mo cap, every additional dollar earns 0% cashback while still paying FX. KAST Points accrue on Premium and Luxe tiers as a secondary stream, but KAST confirmed in July 2026 they will convert into an equity-linked instrument rather than a token (mechanics due Q4 2026) - value them at zero until then.
+No annual fee ($40 physical card shipping)
+1.5% USD cashback on first $2,000/month of spend (max $30/mo)
+Separate Standard Reserve account pays a promotional 8% annual reward rate on an uncapped balance
Jupiter Global is a solid free virtual card, but read the base rate honestly: 2% in USDC, doubling to 4% only in months after you refer 2 qualifying friends. The verdict also depends on issuer assignment: Rain keeps the FX profile cleaner, while DCS asks you to accept 1.8% non-USD conversion costs.
Why it ranks here
2% base USDC cashback on a free virtual card with 0% on USD payments, credited automatically after each transaction settles. You can raise it to 4% (cap $200) for a month by referring 2 qualifying friends the prior month. A $20 sign-up bonus through SpendNode lands after $1,000 in first-30-day spend. Apple Pay and Google Pay supported.
Watch out
The base rate is now 2%; the 4% base and its 5/8/10% referral tiers were a launch promotion that ran its course and ended June 30, 2026. 1% FX on non-USD (Rain) or 1.8% (DCS) erodes it further for international spending, and the $100 base cap binds at $5,000/month. Live in selected US, LATAM, APAC, Africa, Caribbean, and UAE markets rather than broad Europe-wide coverage. Customer support is helpful but slow.
+2% base cashback on a free virtual card
+Refer 2 qualifying friends a month to raise cashback to 4%
+USDC deposits convert 1:1 to USD with no fee
+0% fee on USD card payments
Option 7
7. Oobit Visa Card
Spend Crypto Anywhere Visa Works - Self-Custody or In-App
The Oobit Visa Card is a virtual, tap-to-pay crypto card with a Free annual fee that spends from your own wallet or an in-app balance. Domestic USD spending is cheap and the cashback is strong once unlocked at Level 2 ($250 of spend): 10% in OOB or 5% in stablecoin on USDT, paid in 1-3 days. Foreign spending carries roughly 3% in FX, so it suits USD-heavy spenders best.
Why it ranks here
5% back on stablecoin-funded spend paid in stablecoin, with a higher 10% OOB-funded track for users willing to take OOB payout exposure. The virtual Visa has no annual fee, works through a hybrid custody model, and is broad enough geographically to matter on a global hub page.
Watch out
The headline rewards are capped and conditional: 5% stablecoin rewards are capped at $200/month of spend, while 10% OOB rewards apply only to OOB-funded spend and are capped at $10,000/month of spend. Non-USD payments carry roughly 3% FX, and each payment has a 1% or $0.25 minimum fee, so it is strongest when the reward track comfortably clears the fee stack.
+Up to 10% cashback (OOB) or 5% in stablecoin (USDT), paid in 1-3 days
+Hybrid spending from a connected wallet or in-app balance
+No annual or issuance fee
+Apple Pay and Google Pay supported worldwide
Option 8
8. Pro (Royal Indigo / Jade Green)
The Lifestyle Sweet Spot: 3% Cashback + Lounges + Netflix
For many, the Pro (Royal Indigo / Jade Green) is the sweet spot. It offers a solid 3%% rate and airport lounge access. Whether you pay $299.9 or lock up $5,000 in CRO, the lifestyle perks add up quickly for frequent travelers.
Why it ranks here
3% cashback, airport lounge access, and the most recognized brand in crypto cards. Crypto.com has been doing this longer than almost anyone, the app is polished, and customer support exists at a scale most crypto card issuers cannot match.
Watch out
Requires a $5,000 CRO stake to unlock. CRO is a volatile platform token, so the actual cost depends on what CRO does over your holding period. If CRO drops 30%, the lounge access and 3% cashback may not cover the loss.
+6-month Spotify, Netflix, and Truth+ rebates
+Airport lounge access (4 visits/year for annual subs)
+Solid 3.0% rewards on everyday spend
+Crypto.com Travel rewards vary by plan and market
Option 9
9. Xplace Gold Card
10% Off Gold with SPENDNODE: Pay $224.10 Instead of $249
Gold is the premium metal tier. At $249 per year it pays 1.5% USDC cashback in Credit Mode, cuts FX to 0.25%, and adds four annual lounge visits with fast-track. The $249 fee is recovered at roughly $16,600 of annual cashback-eligible spend, within the $100 monthly cashback limit.
Why it ranks here
A self-custody metal tier on a Kamino-backed Solana credit line: 1.5% USDC on Credit Mode spending for new memberships, capped at $100 of cashback per month, to a $200,000 monthly limit. The metal card, four lounge visits, 0.25% FX, a 6% XP rate, and 5% AI and rides boosts come bundled.
Watch out
You are spending borrowed USDC against your own collateral, so the card carries Kamino borrow APR and liquidation risk that top-up cards do not. Cash Mode earns no cashback on new memberships, and the $249/year fee needs roughly $16,600 of annual eligible spend to recover on the flat rate. Xplace has repriced repeatedly in 2026; memberships bought before September 14, 2026 can keep the earlier 3% for up to 12 months from purchase.
+1.5% USDC cashback in Credit Mode plus 6% XP
+0% card transaction fee, FX cut to 0.25%
+4 free lounge visits and 2 fast-track passes per year
+$200,000 monthly spending limit
Honorable Mention
This card would rank alongside the picks above if it were available globally. It is currently limited to the EEA and Switzerland.
Option 10
10. Bleap Mastercard
Secure DeFi Spend: Tiered USDC Cashback + 0% FX Fees
The standard Bleap card pairs self-custody with the liquidity of a Mastercard. It offers 2% cashback and a Free annual fee, with funds held in a smart account you control until the moment of purchase.
Why it ranks here
Free, self-custodial, 0% FX, and a tiered cashback structure that pays 20% on streaming and AI subscriptions, 3% on rides and delivery, and 2% on groceries and dining. Plus yield on idle balances (5% EUR, 11% USD). It hits nearly every category on our scoring framework.
Watch out
EEA and Switzerland only. If it were available globally it would be in the main list. The cashback cap is described as a fair-usage limit with no hard number disclosed, so heavy spenders should watch for throttling.
+100% non-custodial account abstraction
+Tiered cashback: 20% subs, 3% rides/delivery, 2% dining/groceries, 1% base
+Zero Bleap fees (no FX, no monthly)
+Virtual + plastic + metal card options
spendnode.io Research9 verified in the last 30 days
Crypto Card Market Changes We Verified
Rate cuts, fee changes, launches and shutdowns confirmed against official vendor sources or in-app checks before we updated our rankings.
Oct 19, 2026spendnode.io Research
Wirex: Wirex activity rises while average observed value declines
Previous period: Week ending October 11: $6.73M across 111,388 card-debit events and 11,499 active wallets
Current period: Week ending October 18: $6.59M, down 2.1%, across 113,347 events and 11,870 active wallets
Oct 19, 2026spendnode.io Research
xPlace: xPlace records the largest weekly percentage decline
Previous period: Week ending October 11: $2.06M across 39,886 observed events and 5,844 active wallets
Current period: Week ending October 18: $1.60M, down 22.6%, across 18,729 events and 1,798 active wallets
Before: Signup links and recommendations suspended while the outage remained unexplained
Now: Removed from active listings, recommendations, promo coverage, comparisons, and monitoring after the domain stopped resolving and no customer-funds notice appeared
Oct 12, 2026spendnode.io Research
ether.fi: ether.fi records more events at a lower average value
Previous period: Week ending October 4: $33.10M across 407,644 observed spend events, averaging $81.21 per event
Current period: Week ending October 11: $31.62M, down 4.5%, across 412,894 events, averaging $76.57 per event
Oct 12, 2026spendnode.io Research
Plasma One: Plasma One volume rises as the prior event-count spike reverses
Previous period: Week ending October 4: $6.70M across 153,230 settlement events and 20,923 active wallets
Current period: Week ending October 11: $7.28M, up 8.6%, across 37,060 events and 12,504 active wallets
Oct 10, 2026Availability
PlasBit: Website and signup flow become unavailable
Before: Website, account signup, and official social pages available
Now: Website and signup unavailable; public communication channels inaccessible; no official shutdown or maintenance notice found
Oct 5, 2026spendnode.io Research
Plasma One: Plasma One records more events and wallets at a lower average value
Previous period: Week ending September 27: $6.83M across 36,674 settlement events and 12,019 active wallets
Current period: Week ending October 4: $6.70M, down 1.9%, across 153,230 events and 20,923 active wallets
Oct 5, 2026spendnode.io Research
ether.fi: ether.fi leads weekly growth among measured programs above $1 million
Previous period: Week ending September 27: $28.98M measured card spend across 376,833 observed spend events
Current period: Week ending October 4: $33.10M, up 14.2%, across 407,644 events
Oct 1, 2026New listing
Pulsar Money: Pulsar Money joins the SpendNode catalog with Free and Pro Visa cards
Verified: SpendNode completed verification and a successful card purchase; Free and Pro virtual Visa plans serve 76 published countries with USD and EUR balance routes
Sep 25, 2026Security
Payy: Exploit investigation moves to third-party validation
Before: Payy had not publicly confirmed an active security incident
Now: Payy confirmed an exploit; independent validation is pending and scope, amount, and user impact remain undisclosed
Sep 21, 2026spendnode.io Research
xPlace: xPlace volume rises while observed wallet count declines
Previous period: Week ending September 13: $2.36M measured card spend across 1,534 observed wallets
Current period: Week ending September 20: $2.62M, up 10.9%, across 1,461 observed wallets
Sep 21, 2026spendnode.io Research
Plasma One: Plasma One leads weekly growth among measured programs above $1 million
Previous period: Week ending September 13: $5.22M measured card spend across 33,982 settlement events and 11,192 active wallets
Current period: Week ending September 20: $6.23M, up 19.5%, across 32,384 events and 11,483 active wallets
Sep 21, 2026Shutdown
Gnosis Pay: Direct consumer card and web app to close December 20
Before: Gnosis Pay operated a direct consumer card and web app
Now: Direct card spending ends December 20, 2026; Safe balances remain self-custodial with a continuing withdrawal route
Sep 14, 2026spendnode.io Research
ether.fi: ether.fi records more spend events at a lower average value
Previous period: Week ending September 6: $32.58M across 355,972 observed spend events, averaging $91.53 per event
Current period: Week ending September 13: $28.53M, down 12.4%, across 364,166 events, averaging $78.34 per event
Sep 14, 2026spendnode.io Research
Wirex: Wirex leads weekly growth among measured programs above $1 million
Previous period: Week ending September 6: $5.14M measured card spend across 84,605 card-debit events and 8,614 active wallets
Current period: Week ending September 13: $5.61M, up 9.1%, across 92,281 events and 9,210 active wallets
Before: The prior card structure did not publish the current Core, Luxe, Pinnacle, and VIP qualification and benefit schedule
Now: Core remains free; Luxe and Pinnacle add points, Liquid, ETHFI, or annual qualification routes; VIP publishes asset thresholds and 4% ETHFI cashback on the first $50,000 monthly band
Sep 7, 2026spendnode.io Research
ether.fi: ether.fi records the largest observed weekly card volume
Previous period: Week ending August 30: $27.65M measured card spend
Current period: Week ending September 6: $32.58M, up 17.9%, and the largest result among 11 mapped programs
Sep 7, 2026spendnode.io Research
Plasma One: Plasma One leads weekly growth among measured programs above $1 million
Previous period: Week ending August 30: $3.76M observed settlement-based card spend across 8,881 active settling wallets
Current period: Week ending September 6: $4.83M, up 28.6%, across 10,607 active settling wallets, up 19.4%
Sep 1, 2026New listing
Ethena Pay: Ethena Pay launches beta card in 49 countries
Verified: A self-custodial app with a secured virtual Visa, 4-5% first-band cashback paid in AVAX, and an annualized Daily Boost of up to 6% on eligible balances
Aug 31, 2026New listing
MEXC: MEXC Global Card launches across 100+ markets
Verified: A virtual Visa Platinum funded with USDT is live with 0% purchase fees through September 30, then 1%, and VVIP cashback of 4-10% with monthly caps
Aug 27, 2026spendnode.io Research
Jupiter: Jupiter settlement mapping corrected after a collector rotation
Previous period: July measured card spend appeared to be $0.4M when only the legacy Solana settlement address was counted
Current period: Expanded mapping across the legacy and rotating collector lanes measures $7.5M in July and $5.7M through August 25; current-month data remains partial
Before: The 16g Platinum Visa Infinite card had been announced but was not yet reaching cardholders
Now: Plasma One has started shipping the metal card, and early qualified cardholders are receiving deliveries
Aug 18, 2026Launch
Hyperbeat: Hyperbeat Pay launches on iOS and Android
Before: Hyperbeat did not have a public mobile card product
Now: A free virtual Visa is live with Cash and collateralized Credit modes, WHYPE cashback, and a $15 new-user reward after KYC and three card transactions
Aug 15, 2026Rate change
xPlace: xPlace to cut card cashback from 14 September 2026
Before: Credit Mode pays 1-4% USDC (Basic 1%, Silver 2%, Gold 3%, Platinum 4%) and Cash Mode still earns cashback
Now: From 14 September 2026, Basic and newly purchased paid memberships receive 0.5-2% in Credit Mode and 0% in Cash Mode; paid memberships purchased before the deadline keep their current 2-4% Credit Mode and 1-2% Cash Mode rates for up to 12 months from purchase
Aug 13, 2026Promo
KAST: Five-percent category cashback campaign goes live
Before: Normal membership-tier rewards
Now: Eligible Shopping, Dining, and Travel purchases earn 5% net cashback through September 30, capped at $100 per person; rewards are due in early October and the campaign can end early when its budget is exhausted
Jul 31, 2026Program change
PlasBit: PlasBit discontinues its prepaid card program
Before: PlasBit offered two cards: a reloadable Visa debit card and a fixed-balance prepaid Mastercard line in denominations from $25 to $10,000
Now: PlasBit has permanently closed the prepaid card program and now offers only its reloadable Visa debit card, which is unaffected
Jul 30, 2026Program change
Ready: Ready card program unavailable as its issuer winds down
Before: Ready (formerly Argent) card live: self-custodial Starknet Mastercard, Lite (free, 0.5% STRK) and Metal (120 USDC/yr, 3% STRK, 0% FX), USDC spend from your own wallet in the EEA and UK
Now: The card stopped after Ready's card issuer (Kulipa, the same partner whose wind-down paused Solflare days earlier) began winding down; wallet assets stayed in users' self-custody and eligible card subscriptions are being refunded automatically. Ready says it is rebuilding on new infrastructure, with no confirmed relaunch date, issuer, or terms
Jul 29, 2026spendnode.io Research
ether.fi: ether.fi tracks toward its first ~$100M card-spend month
Previous period: June 2026 measured card spend: $83.4M across 37,051 active accounts (Optimism)
Current period: July at $91.9M by the 29th and pacing toward roughly $98M, extending the climb since the Optimism migration and the largest measured card-spend program we track
Jul 28, 2026Program change
Solflare: Card paused as issuing partner Kulipa winds down
Before: Self-custodial Solana card live: virtual and physical cards spending USDC straight from your wallet
Now: Both cards stopped July 28 after issuing partner Kulipa wound down; funds stayed safe in users' wallets and open Borrow positions kept working; a new-issuer card is expected August 2026, though existing cards will not carry over
Jul 21, 2026spendnode.io Research
KAST: KAST top-ups pace toward a record month despite the token cancellation
Previous period: June 2026 onchain top-ups: $194M; token plans cancelled July 2
Current period: July top-ups pacing about 10% above June toward the program's strongest month yet, three weeks after the points-to-equity pivot
Jul 21, 2026spendnode.io Research
Plasma One: Plasma One clears June's volume with a third of July left
Previous period: June 2026 measured card spend: $9.0M across 10,124 settling accounts
Current period: July at $9.4M by the 21st with more than 11,400 active settling accounts, five weeks after the June 16 public launch
Jul 21, 2026spendnode.io Research
Xplace: Xplace July spend passes June's full month by mid-month
Current period: July passed June's full-month total by the 21st and is pacing at roughly double, the clearest volume response to the July Credit Mode cashback doubling among the programs we measure
Jul 18, 2026Security
MetaMask: Consensys revokes code access for North Korea-linked developer
Before: A DPRK-linked contractor held access to MetaMask-related code repositories
Now: Access revoked after internal review; Consensys says user funds and released wallet code were not compromised
Now: Full vendor + product coverage live: reloadable EUR/USD Visa Platinum debit at currently zero issuance, loading, and monthly fees, plus fixed-balance Mastercard prepaid cards from $25 to $10,000
Jul 17, 2026Program change
Kolo: BTC cashback becomes introductory and capped
Before: A flat 2% BTC cashback headline with no published ATM terms in our data
Now: Individual USD and EUR cards earn 2% for 30 days then 1%, with per-transaction and $100/EUR 100 monthly caps; ATM withdrawals are limited to $500 each and three per day at $1 plus 0.65%
Jul 17, 2026New listing
Rizon: Rizon joins the SpendNode catalog with a $1 card code
Before: No coverage; US-issued cards largely out of reach for the 50 passports Rizon serves
Now: Full vendor + product coverage live; code spendnode cuts the virtual Visa Platinum from $10 to $1 (90% off)
Jul 17, 2026Program change
Crypto.com: Citadel Securities invests $400M at a $20B valuation
Before: Self-funded exchange balance sheet behind the card program
Now: $400M strategic investment from Citadel Securities, the largest US market maker, at a $20B valuation
Tria: VIP trading-badge ladder raises cashback for high-volume traders
Before: Standard tier cashback with no trading-badge boosts
Now: A VIP badge ladder adds +0.25% to +3.5% cashback and lifts the spend cap, but the badges are gated by $250K to $100M of 30-day trading volume on Hyperliquid and Decibel, so ordinary cardholders will not reach them
Jul 8, 2026Availability
Nexo: Nexo Card launches in Argentina, its first LATAM market
Before: Nexo Card available across Europe
Now: Now live in Argentina, the first Latin American rollout, extending the borrow-to-spend card beyond Europe
Jul 8, 2026Fee change
Plasma One: Core tier repriced as the launch-window free year ends
Before: Core annual fee $120 (or a 10,000 XPL lock), with a free first year during the launch window
Now: Core annual fee $199 (or a 20,000 XPL twelve-month lock); the free first year has ended
Xplace: Merchant category boosts added to paid tiers
Before: Flat Credit Mode cashback by tier
Now: Paid tiers add 3-5% on rides (Sixt, Uber, Wheely), 5-10% on AI subscriptions (ChatGPT, Claude, Cursor), and 10% at six airlines on Platinum, each capped at $250-$500 of Credit Mode spend per month
Gnosis Pay: June 1 security incident disclosed, balances restored
Before: A June 1 security incident affected some card accounts
Now: Gnosis Pay disclosed the incident and said all affected balances had been restored
Jul 2, 2026Program change
KAST: Token launch cancelled; points to convert into equity-linked instrument
Before: KAST Points framed as a future token allocation (originally 1 point = 1 token at TGE)
Now: No token. Points slated to convert into an equity-linked instrument valued off the latest funding round, mechanics due Q4 2026, with redemption and buyback options for smaller balances
Tria: Season 3 cashback cap confirmed as a spend cap
Before: Uncapped headline cashback
Now: 6% on the first $2,000 of monthly spend (Premium), then 1%
May 10, 2026Promo
ether.fi: Dining cashback boost via SpendNode referral
Verified: Up to 15% cashback on food and dining through SpendNode's link
Every entry verified by spendnode.io before rankings were updated. Full history on each vendor page.
spendnode.io Research
Onchain Crypto Card Volume Tracker (Sep 2026)
The card programs we measure directly from blockchain settlement data. This is not a market total: it covers the programs whose flows we can verify onchain, ranked by their latest full month.
Latest closed week
October 25, 2026
Observed spend
$86.4M
Week over week
+5.2%
Programs rising
7/11
Frozen Monday-to-Monday UTC measurement across mapped programs, not total market volume.
Latest full-month trends
SpendNode measured $347.1M of card spending across 11 programs in September, up 13.6% from August on a matching basis. Ether.fi led at $128.8M and KAST followed at $113.8M. Plasma One, Wirex One, and Tria each exceeded $20M, while eight of the 11 measured programs finished higher month over month.
Ether.fi and KAST supplied $28.3M of the $41.5M net increase and represented 69.9% of observed spending. Optimism carried $129.8M and Solana $109.8M across the mapped programs. These chain totals describe SpendNode's observed set, not total crypto card market share.
Activity did not move in lockstep with value. Plasma One settlement events rose 76.3% while active settling wallets declined 5.6%; xPlace events rose 36.8% while average observed event value fell 22.2%. Ether.fi's events rose 9.5% and active Optimism accounts rose 8.0%, while spending increased 17.6%.
RedotPay received $496.9M across 582,320 recognized-asset top-ups, down 4.4% from August under the same nine-chain scope. That series measures card funding rather than purchases and remains separate from measured spending. Bitcoin and unmapped routes are excluded rather than estimated.
Source: direct chain data and Dune indexed tables, analysis by www.spendnode.io - Updated 2026-10-26 - Methodology - Program details remain available on each vendor page.
How We Test Crypto Cards
My colleagues and I have put more than $40,000 through crypto cards to see what happens after the marketing ends. Some paid instantly. Some hid their real cost in spreads, limits, or delays. On a few, we were still waiting months later for rewards that were supposed to be simple.
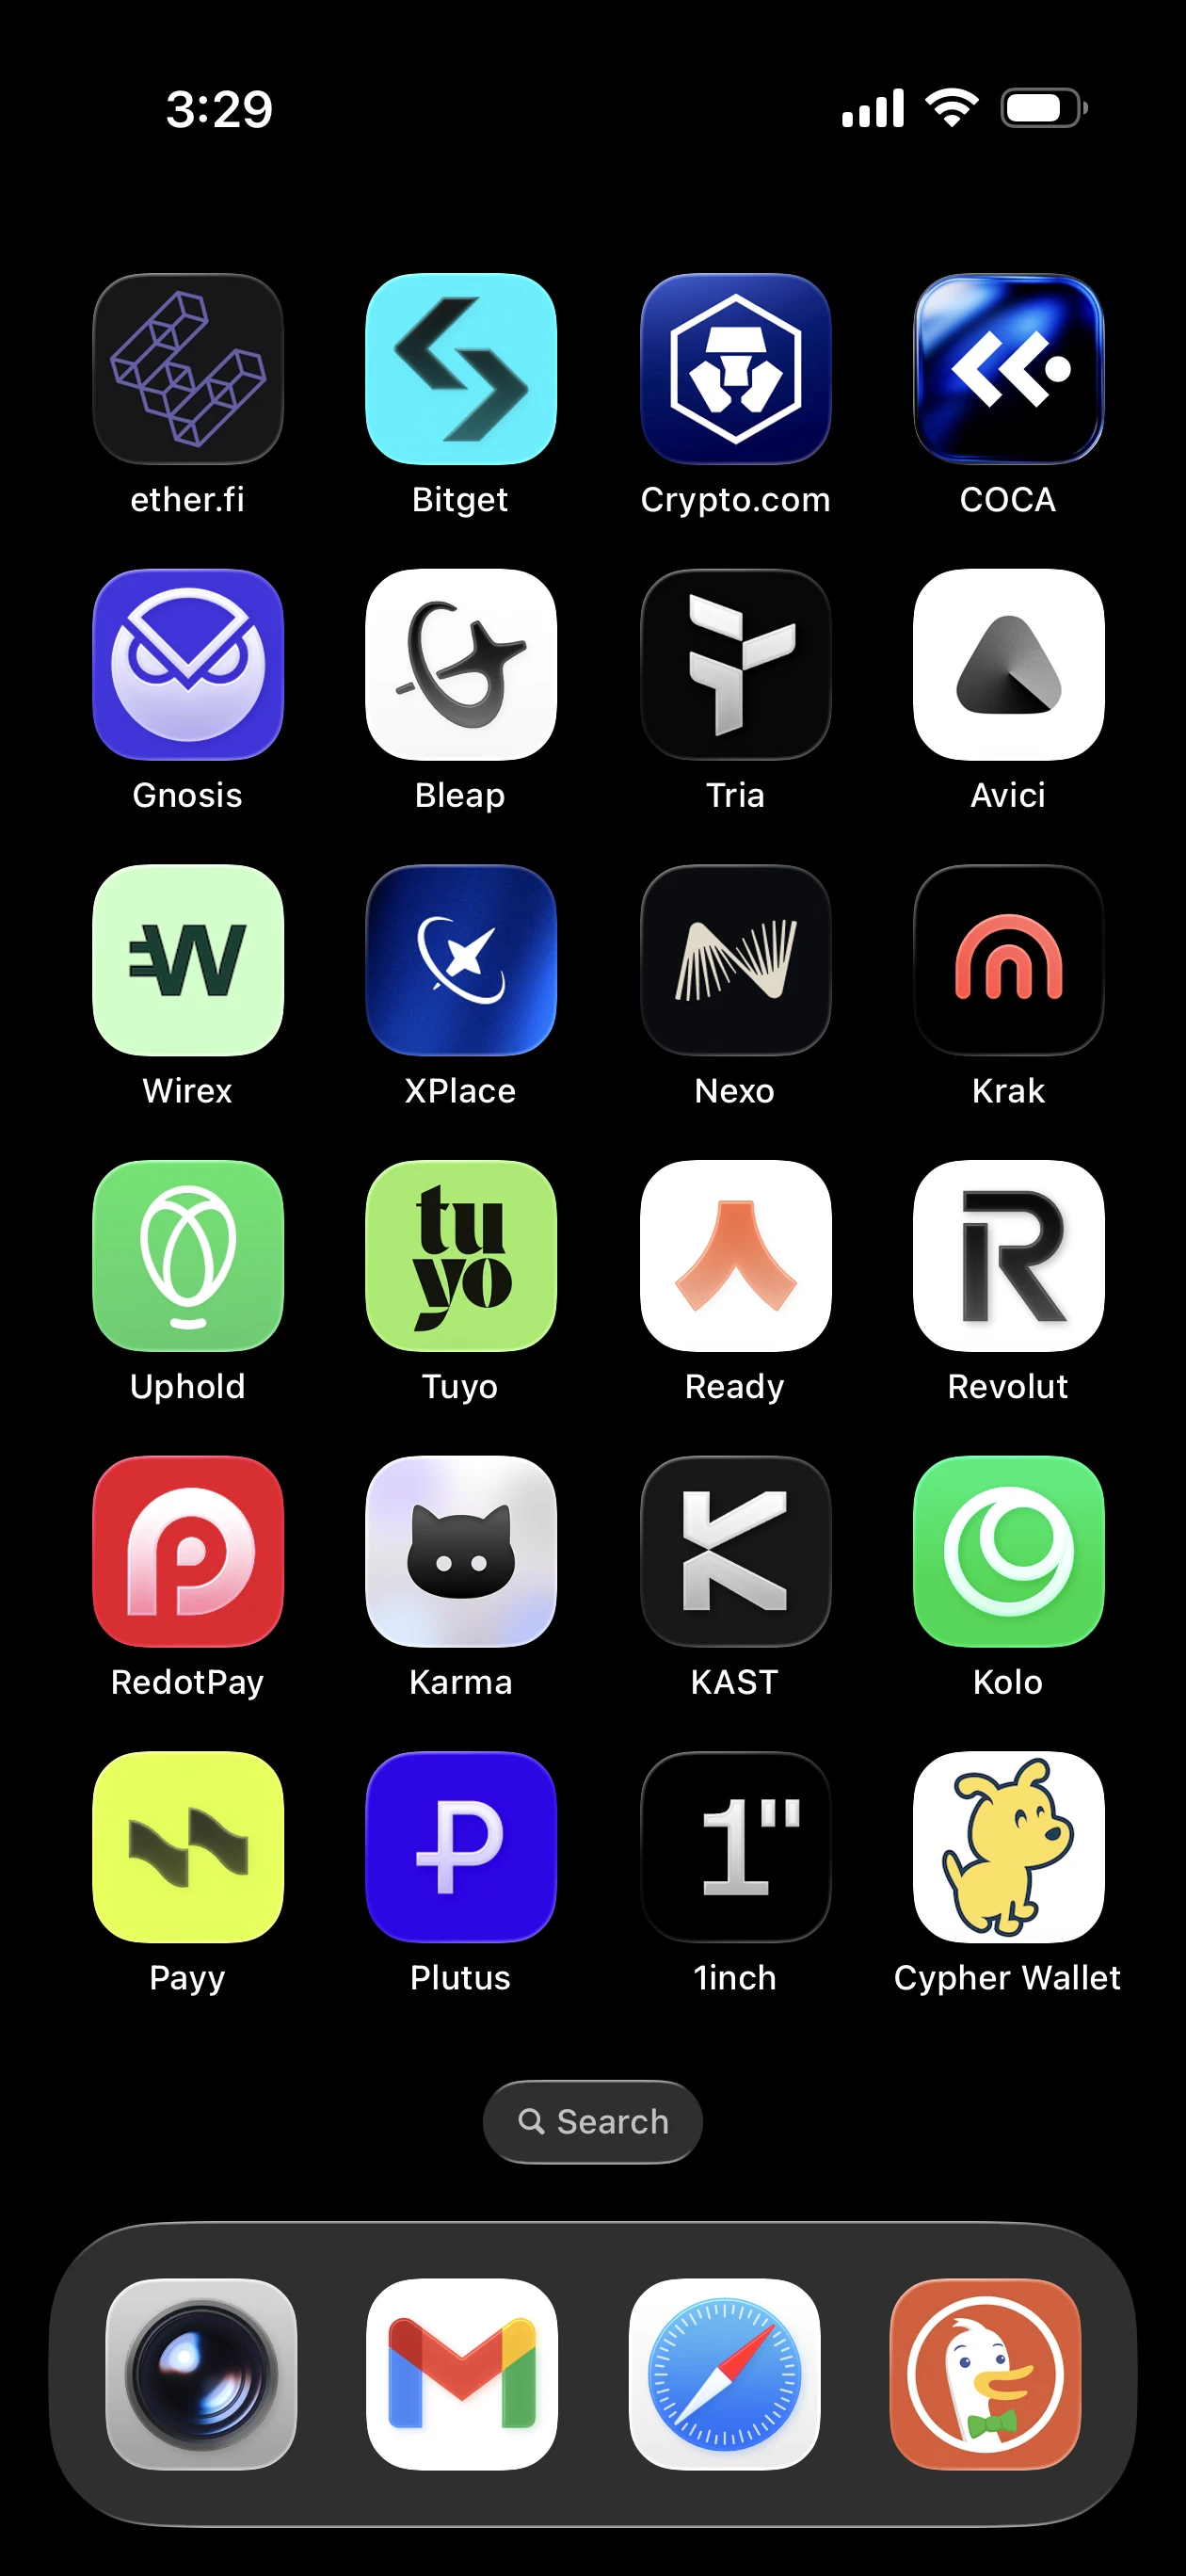
When I started this journey, all I wanted was to spend my crypto without going through a bank. At the time, only a handful of cards existed. Then one by one, competition started growing - more cards launching with better perks, lower fees, and wilder cashback promises - to the point where my iPhone home screen became a full page of virtual crypto cards.
That is when I decided to start tracking my actual expenses, real ROI, and what mattered most to me so I could get the most out of each one. Once I started doing that, the idea of building a comparison site felt obvious. If you want to compare cards yourself, you can use our comparison tool here.
Comparing crypto cards well is harder than most people expect. The headline cashback rate is only part of the story; the biggest differences usually come from custody model, hidden spread, reward payout speed, regional availability, funding flow, and whether the card still makes sense after fees and restrictions show up.
So what mattered most when we ranked the cards? There is no single factor. Rewards are measured after annual fees, payment charges, FX costs, and monthly caps rather than by the maximum advertised percentage. We also tested Apple Pay and Google Pay support, KYC time, funding flow, reward payout, and how each app handles day-to-day spending. Custody design matters, but it does not cancel smart-contract, bridge, issuer, or chain risk.
Broad availability matters on this page because a card that serves one narrow market cannot be the best general recommendation. Reliability can override the arithmetic: a closing card is removed from new-user picks, and a product with an unresolved security incident is not promoted as a top choice until the material facts are public. We rerank when fees, reward caps, availability, security status, or issuer terms change.
SpendNode app screenshot
A portion of crypto cards sitting in my phone.
How Crypto Cards Actually Work
If you are new to crypto cards or just want to understand the mechanics before picking one, here is how the whole thing works under the hood.
A crypto card bridges the gap between digital assets and everyday spending. You hold Bitcoin, Ethereum, USDC, or other cryptocurrencies in a wallet or exchange account. The card is linked to that balance.
When you make a purchase - groceries, a flight, a subscription - the card issuer converts just enough crypto to cover the transaction amount in the merchant's local currency. The merchant receives fiat through the Visa or Mastercard network, exactly like any other card payment. The entire conversion happens in seconds. That same mechanic runs underneath every card type mapped above; what changes between types is where the money sits before the swipe and who holds it.
Is a Crypto Card a Credit or Debit Card?
Most are prepaid or debit: you spend crypto you already hold, with no credit line. A smaller group are true credit cards - Gemini issues a Mastercard credit card and Coinbase One runs on American Express - while crypto-backed cards like Nexo let you borrow against your holdings instead of selling, and Avici issues a secured card where your crypto collateral funds a USD spending limit. Each card's type is listed on its own page.
Who Holds Your Crypto? The Custody Question
Custody is the single most important decision when choosing a crypto card. It determines what happens to your money if the card company fails, gets hacked, or freezes your account.
Custodial cards keep your crypto in the exchange's wallet. The exchange controls the private keys. If the company fails, you are an unsecured creditor. FTX (2022) - users lost 100% initially, partial recovery after 2+ years of bankruptcy. Celsius (2022) - approximately 70% recovery after 18 months. Voyager (2022) - approximately 35%. These collapses permanently changed how the market thinks about custodial risk and directly fueled the self-custody movement.
Self-custodial cards let you control the private keys. The card issuer facilitates conversion at the point of sale without holding the spending balance in a company account. If the card company shuts down, the assets can remain on-chain even though card access may stop; recovery still depends on the wallet, contracts, chain, and available exit path.
The trade-off: full self-custody means full responsibility. Lose your seed phrase and there is no password reset. One exception: 1inch Card is wallet-branded but actually custodial (issued by Baanx), so your funds leave your control when loaded.
Smart wallet and hybrid cards use account abstraction, MPC, or social recovery to give you self-custody security without the seed phrase anxiety. Your keys are split across multiple parties or secured behind guardian-based recovery, so losing one factor does not mean losing everything. ether.fi, Tria, COCA, and Bleap all use variations of this approach.
Custody Model
Who Holds Keys
Company Fails
Recovery
Best For
Custodial
The exchange
You are unsecured creditor
Customer support, password reset
Beginners, convenience
Self-Custodial
You (seed phrase)
Assets remain on-chain; card access may stop
Seed phrase and a working exit path
Security-conscious users
Smart Wallet / MPC
Split across parties
Assets can remain on-chain; recovery design varies
Social recovery, guardians
Balance of security and usability
How to choose: If you hold under $1,000 in crypto and value simplicity, custodial cards from regulated issuers (Coinbase, Crypto.com, Kraken) offer the path of least resistance.
If you hold significant value or distrust centralized platforms after watching exchanges collapse, live self-custodial cards such as MetaMask and xPlace remove direct exchange custody from the spending balance. They do not remove protocol or card-program risk. Gnosis Pay demonstrates the distinction: its direct card closes December 20, but users retain control of their Safe balances and withdrawal access.
If you want self-custody without the seed phrase anxiety, smart wallet cards (ether.fi, Tria, COCA) offer a middle ground with account abstraction or social recovery. Browse our full self-custody card comparison for detailed breakdowns.
The Total Cost of a Crypto Card: Fees, Spreads, and Hidden Charges
A crypto card advertised as "0% fees" can still cost you 2-3% per transaction. The crypto card fee structure has up to five layers, and the one that costs the most is the one that is hardest to see.
The Five Fee Layers
1. Conversion spread (0.1% - 3%) - The difference between the true market price (what CoinGecko or CoinMarketCap shows) and the rate the card gives you. A card might quote you Bitcoin at $98,000 when the market price is $100,000 - that 2% gap is $2,000 per Bitcoin, or $2 on a $100 purchase.
This is the primary revenue source for most crypto card issuers, and it is almost never disclosed upfront. Cards that allow stablecoin spending (USDC, USDT) have the tightest spreads (0.1-0.5%) because there is virtually no volatility to mark up.
2. Transaction fee (0% - 1.5%) - A flat percentage charged on every purchase. Most major issuers charge 0%, but some add transaction fees on top of spreads. Bitget Wallet Card charges 1.7% FX (with a $400/month zero-fee quota). Bitget Exchange Card charges 0.9% per transaction.
3. Foreign exchange fee (0% - 3%) - Charged when you spend in a currency different from the card's base currency. This is the fee that hits travelers hardest.
Cards with 0% or near-0% issuer FX positioning include Bitpanda, Wirex (35 countries), and Kraken. Gnosis Pay also avoids issuer FX markup, but non-EUR usage still follows the Visa network rate. Ready Metal sat here too, but the Ready card program is currently unavailable after its card issuer began winding down.
Tria is better treated as a high-reward card where the 0.5% payment fee and non-USD FX cost need to be included in the math. Nexo charges a low 0.2% weekday / 0.7% weekend within EEA/UK/CH. Others charge 1-3% that compounds on top of the conversion spread. See our full no-FX-fee card comparison.
4. ATM withdrawal fee ($0 - $5+) - Charged when you withdraw cash from an ATM. Most cards charge a flat fee ($1-3) plus a percentage (0.5-2%). Some premium tiers include free monthly ATM allowances: Crypto.com Obsidian ($1,000/month free) and Avici Signature ($0 ATM fees). Ready Metal offered $800/month free, but the Ready card program is currently unavailable after its card issuer began winding down.
Premium tiers carry annual fees: Avici Signature ($30/year), and Ready Metal charged 120 USDC/year before the Ready card program became unavailable (its card issuer began winding down). Crypto.com tiers above Ruby require CRO staking, which is a form of opportunity cost even if no explicit annual fee exists. See our full no-annual-fee card comparison.
How to Minimize Your Total Cost
Spend stablecoins whenever possible. When you spend USDC or USDT, the card converts a dollar-pegged asset to dollars - minimal volatility means minimal spread opportunity for the issuer. Spreads on stablecoin transactions are typically 0.1-0.5%, compared to 1-3% on volatile assets like BTC or ETH. Cards that support direct stablecoin spending include ether.fi, RedotPay, KAST, MetaMask, COCA, Kolo, and Payy. See our stablecoin card comparison.
Avoid the staking trap. High cashback rates that require locking thousands of dollars in a volatile platform token (CRO, WXT, BGB) can cost more in token depreciation than they earn in rewards.
Example: A card offering 3% cashback with a $5,000 CRO stake generates $720/year on $2,000/month spend. But if CRO drops 20% (which happened in Q4 2025), the $1,000 stake loss wipes out nearly 17 months of cashback earnings. For most users spending $1,000-3,000 per month, a no-stake card with 1-4% cashback delivers better risk-adjusted returns. See our detailed reward comparison.
Check FX fees before traveling. A card with 0% transaction fee but 3% FX markup costs you 3% on every purchase abroad. For international travel, a zero-FX card paying from stablecoins gives the tightest total cost - potentially under 0.5% all-in versus 3-5% on a card with stacked fees. See our no-FX-fee comparison and our travelers guide.
Compare the full fee stack, not individual fees. A card advertising "0% transaction fee" with a 2.5% spread costs more than a card with a 1% transaction fee and 0.3% spread. The only way to know the true cost is to test with a small transaction and compare the amount deducted from your balance against the CoinGecko mid-market rate at the time of purchase.
How to Choose the Right Crypto Card
The best crypto card depends on four factors, in this order of importance:
1. Where You Live
Regional availability eliminates most options before you start comparing features. A US resident choosing between 5-6 cards faces a fundamentally different decision than a European resident choosing between 20+. Start by checking your country guide to see which cards are actually licensed and available in your market. Do not apply for a card that does not explicitly list your country in its supported regions - you risk account closure and frozen funds.
2. Your Custody Preference
This is your security decision, and it is permanent for the life of that card relationship. If you lived through the FTX collapse or simply believe in "not your keys, not your coins," live self-custodial cards such as MetaMask, Ledger, and xPlace are the relevant category. Gnosis Pay is winding down its direct card, Payy's confirmed exploit remains under third-party validation, and Solflare's card is paused.
If you prioritize convenience and trust regulated exchanges, custodial cards from Coinbase, Crypto.com, or Kraken are appropriate. If you want self-custody with training wheels, smart wallet cards (ether.fi, COCA) split keys across parties with social recovery. There is no universally correct answer - only different risk tolerances. See our full self-custody comparison.
3. Your Fee Sensitivity
If you spend $500/month, a 2% hidden spread costs you $120/year. At $3,000/month, the same spread costs $720/year. At $10,000/month, it costs $2,400/year.
For low spenders, fee differences between cards are marginal and convenience matters more. For high spenders ($3,000+/month), the difference between a 0.3% spread (stablecoin spending on Gnosis Pay) and a 2% spread (BTC conversion on a generic card) is hundreds of dollars annually. High spenders should optimize for the lowest total fee stack, not the highest cashback rate. See our high spenders guide.
4. What You Actually Want From Rewards
No-stake cashback (Oobit 5% USDT / up to 10% OOB, Tria 4.5% to $1,000/mo before fees, xPlace Gold 1.5% USDC in Credit Mode capped at $100/mo with a $249/yr fee, ether.fi Core 3%, Jupiter Global 2% base, Kolo 1% BTC ongoing (2% intro, capped), COCA 1% Starter): Your rewards carry no token-staking capital at risk. Best for most users.
Staking-based cashback (Crypto.com 1-5%, Wirex 2-8%, COCA up to 8% with staking $COCA): Higher advertised rates require locking volatile platform tokens.
The math only works if the token holds value over your staking period and your monthly spend is high enough for cashback to outweigh stake depreciation risk. Best for users who already hold the platform token for other reasons.
Points and airdrop exposure (ether.fi tiers, xPlace): Speculative upside with no capital lockup requirement. Points may convert to valuable tokens at a future token generation event, or they may be worth nothing. KAST sits apart here since July 2026: its points are slated to convert into an equity-linked instrument rather than a token, with terms due Q4 2026. Best for crypto-native users who want exposure to potential upside without committing capital.
What This Looks Like in Practice
Here are a few decision paths to show how the four factors above play out:
A European digital nomad who values security and travels frequently: ether.fi Core combines self-custody with broad coverage and 3% cashback. (Ready Metal filled another travel slot with 3% STRK, 0% FX, and $800/month free ATM across EEA and UK, but the Ready card program is currently unavailable after its card issuer began winding down.) See our digital nomad guide.
A US beginner who wants simple crypto exposure through spending: Coinbase Card for up to 4% BTC cashback with no staking requirement and FDIC-insured USD balances, or Gemini Credit Card for up to 4% in 50+ cryptocurrencies as a true credit card with no annual fee. See our beginners guide.
A DeFi-native user who wants to spend from their own wallet: MetaMask Card for Ethereum users, xPlace for Solana users, or ether.fi for users who want to earn restaking yield while maintaining card spending capability. Solflare's Solana card is paused as of July 2026 and cannot be used until its replacement launches. See our DeFi users guide.
A high-volume trader who wants maximum cashback on large spend: Crypto.com Obsidian offers 5% cashback with a $400,000 CRO stake, but that only makes economic sense if you are already long-term bullish on CRO and would hold it regardless of the card benefit. See our high spenders guide.
A privacy-focused user who wants minimal onboarding friction: MetaMask Virtual combines self-custody with streamlined verification, while KAST Standard completes full KYC in about 2 minutes. RedotPay also requires government-ID and selfie verification despite its fast-onboarding reputation. See our privacy-focused users guide and no-KYC comparison.
Do Crypto Cards Require KYC?
Most crypto cards require full Know Your Customer (KYC) verification with a government ID and proof of address. A handful keep it minimal or near-instant, including RedotPay, MetaMask, Bleap, KAST (about two minutes), and 1inch. Regulation is tightening under MiCA and the FATF Travel Rule, so low-KYC options may narrow over time. Our no-KYC cards page tracks the current shortlist.
Which Crypto Cards Work in the US, Europe, and the UK?
Availability decides more than features do. Europe (EEA) has the widest choice with 20+ options; the US is narrower, led by Coinbase, Gemini, Tria, and Avici; and the UK sits between the two.
Do not apply for a card that does not explicitly list your country, or you risk a frozen account. We keep dedicated country guides for 100+ markets, including Germany and the rest of the EEA.
Crypto Cards vs Traditional Bank Cards
Crypto cards are not replacing traditional bank cards. They serve different purposes and work best as complementary tools in a broader financial strategy. Here is the comparison:
Feature
Crypto Cards
Traditional Cards
Rewards
1-8% in crypto (variable value)
1-3% in cash/points (stable value)
FX Fees
0-3% (varies by issuer)
0-3% (premium tiers often 0%)
Custody Risk
Counterparty risk if custodial; contract, chain, and exit-path risk if self-custodial
Low (FDIC/FSCS insured)
Tax Complexity
High (every crypto purchase is a disposal event)
Low (rewards generally non-taxable)
Privacy
Higher with self-custody cards
Low (bank tracks everything)
Annual Fee
$0-500
$0-695
Fraud Protection
Weaker (crypto transactions are irreversible)
Strong (chargeback rights under Regulation E/Section 75)
Crypto cards win when: You already hold crypto and want to spend it directly rather than selling on an exchange, transferring to your bank, and then spending from the bank account. You travel internationally and want 0% FX fees without paying $500+ annual fees for a premium traditional card.
You want to reduce reliance on an institution holding your spending balance through self-custody. The card provider can still suspend card access even when it cannot take custody of the underlying wallet assets. You may also want cashback in potentially appreciating assets - 4% in BTC today could be worth 8%+ if Bitcoin doubles.
Traditional cards win when: You need strong purchase protection and chargeback rights (crypto transactions are irreversible). You want stable, predictable reward values that do not fluctuate with market volatility. You do not want to deal with crypto tax reporting on everyday purchases. You value travel perks (Priority Pass lounge access, travel insurance, rental car coverage, concierge services) that most crypto cards cannot match.
What experienced users actually do: Use a traditional card for domestic spending where chargebacks and purchase protection matter most.
Use a crypto card for international spending (zero FX fees), crypto-native purchases (avoiding the exchange-to-bank roundtrip), and deploying stablecoin savings (earn yield until the moment you spend). This hybrid approach captures the benefits of both worlds while minimizing the drawbacks of each.
Crypto Card Tax Implications
In most jurisdictions, spending cryptocurrency through a card is treated as disposing of a capital asset. Every purchase creates a taxable event where you must calculate capital gains or losses based on the difference between your cost basis (what you paid for the crypto) and the disposal value (what the card converted it for at the point of sale).
The specific rates, exemptions, and holding period rules vary enormously by country - check your country guide for jurisdiction-specific details and always consult a qualified tax professional.
That said, two things matter regardless of where you live:
The stablecoin tax advantage: Spending USDC or USDT through a crypto card dramatically simplifies tax reporting. Because stablecoins are pegged to $1.00, the difference between your cost basis and disposal value is typically negligible (fractions of a cent per transaction).
This means minimal or zero capital gains per transaction, turning what would be dozens of complex tax calculations into effectively rounding errors. This is one of the strongest practical arguments for stablecoin-based crypto card spending.
Cashback tax treatment: In most jurisdictions, cashback received from crypto card purchases is treated as a purchase price reduction (rebate), not as income. This means it is generally not a taxable event when received. However, when you later sell or spend the crypto you earned as cashback, the full disposal value may be a taxable gain because your cost basis in that cashback crypto is effectively zero. Track your cashback receipts carefully for accurate tax reporting.
The 2026 Crypto Card Market
The crypto card market is moving fast. Three shifts stand out.
Self-custody is going mainstream. The FTX, Celsius, and Voyager collapses permanently changed user expectations. Self-custodial and smart wallet cards are growing fastest, and the trend is structural - once users experience true asset ownership, the conversion back to custodial models is rare. See our self-custody comparison.
Regulatory compliance is now a competitive advantage. MiCA in Europe, FinCEN tightening in the US, and FATF Travel Rule adoption globally mean that only properly licensed issuers can operate at scale. Vendors without clear regulatory standing are losing banking partnerships and being forced out of major markets. This consolidation benefits consumers through improved security and dispute resolution.
Stablecoins are becoming the default spending asset. More users are loading USDC and USDT instead of spending volatile BTC or ETH. Stablecoin spending eliminates price volatility, minimizes conversion spreads, and simplifies tax reporting. Cards with native stablecoin support are positioned to benefit most, and pending regulatory frameworks in the US and EU could accelerate this by giving stablecoins bank-level recognition. See our stablecoin cards comparison.
Disclaimer: SpendNode is a data comparison platform. We are not financial advisors. Crypto cards involve risks including asset volatility, custodial risk, and tax complexity. Verify all terms directly with issuers before applying.
A crypto card is a Visa or Mastercard that lets you spend Bitcoin, Ethereum, stablecoins, and other digital assets at any merchant worldwide. When you make a purchase, the card converts your crypto to the local fiat currency (USD, EUR, GBP) in real time. The merchant receives regular fiat and never interacts with crypto.
Cards divide by how they pay: debit cards spend a crypto balance in real time, prepaid cards spend fiat you loaded in advance, credit cards pay crypto rewards on a traditional credit line (Gemini, Coinbase One), and crypto-backed cards borrow against your collateral instead of selling it (Nexo, ether.fi). SpendNode tracks crypto cards across major issuers, custody models, and regions.
Is a crypto card a credit card or debit card?
Most crypto cards are prepaid or debit cards where you spend funds you already own in your wallet or exchange account. A smaller number are true credit cards (Gemini issues a Mastercard World Elite credit card with standard credit checks and APR, Coinbase One is an American Express credit card).
Crypto-backed cards like Nexo and ether.fi let you borrow against your holdings without selling, which avoids triggering a taxable event in most jurisdictions - but these are collateral-backed spending lines, not traditional credit cards.
Are crypto cards safe to use?
Safety depends on both custody and the infrastructure behind the card. Custodial cards (Coinbase, Crypto.com, Kraken) hold your funds on the exchange, meaning you are an unsecured creditor if the company fails. Self-custodial cards remove that direct issuer-custody risk, but smart-contract, bridge, stablecoin, chain, and card-program risks remain. Gnosis Pay illustrates the distinction: its direct card closes on December 20, 2026 while users retain control of their Safe balances. Payy has confirmed an exploit whose scope and user impact remain undisclosed pending third-party validation. Visa and Mastercard dispute protections depend on each active card program's current terms.
What fees do crypto cards charge?
Crypto cards have up to five fee layers: conversion spread (0.1-3% markup on the exchange rate), transaction fee (0-1.5% per purchase), foreign exchange fee (0-3% for non-local currencies), ATM withdrawal fee (typically $1-5 per withdrawal), and annual fee ($0-500 depending on tier).
The conversion spread is the biggest hidden cost because many cards advertise 0% fees while charging 1-2% through the spread. Spending stablecoins (USDC, USDT) minimizes spread costs because there is minimal price volatility to mark up.
Can I use a crypto card internationally?
Yes. Crypto cards work at any Visa or Mastercard terminal worldwide. However, foreign exchange fees vary significantly. Cards like Wirex and Bitpanda charge 0% FX markup, while Gnosis Pay avoids issuer FX markup but still follows the Visa network rate on non-EUR usage. Nexo charges 0.2% on weekdays within EEA/UK/CH. Others charge 1-3% on top of conversion spreads.
For international travel, a zero-FX card paying from stablecoins gives the tightest total cost. SpendNode covers card availability through dedicated country and regional guides.
Are crypto card rewards taxable?
In most jurisdictions, cashback received when spending crypto is treated as a purchase price reduction or rebate, which is generally not a taxable event at the time of receipt.
However, when you later sell or spend the crypto you earned as cashback, you trigger capital gains tax based on the difference between your cost basis (the value when received) and the disposal value. Tax rules vary by country. US residents report via IRS Form 8949, EU residents follow MiCA-aligned national rules, and UK residents follow HMRC crypto asset guidance.
What is a self-custody crypto card?
A self-custody crypto card connects to a wallet where you control the private keys rather than loading a company-controlled exchange balance. This can keep the assets on-chain if the card program closes, but card access can still stop and recovery depends on the wallet, contracts, chain, and available exit path.
Current examples include MetaMask Card, Ledger CL Card, and xPlace. Gnosis Pay is winding down its direct card on December 20, 2026 while preserving Safe withdrawals, and Payy's confirmed exploit remains under third-party validation. Solflare's self-custodial card is paused.
Some wallet-branded cards are custodial: the 1inch Card is issued by Baanx with custodial fund management despite the 1inch wallet itself being self-custodial. Full self-custody also means responsibility for key management and no conventional password reset if access is lost.
Do I need KYC verification for a crypto card?
Most crypto cards require Know Your Customer (KYC) verification with government ID and proof of address. However, several cards offer reduced or 2-minute KYC: RedotPay Virtual Card, KAST cards (2-minute verification), MetaMask Virtual Card, Bleap Card, and 1inch Card all operate with minimal identity requirements. Regulatory pressure is tightening globally under frameworks like MiCA (EU) and the Travel Rule (FATF), so fast KYC (2-min) options may become more restricted over time.
Which crypto cards work in Europe, the US, and the UK?
Europe (EEA) has the widest selection with 20+ cards including Bleap, Plutus, Bitpanda, Wirex, Nexo, Ledger, Crypto.com, Bitget, and more. The US market is more restricted: Coinbase, Gemini, Tria, BitPay, Uphold, Avici, and Oobit are the primary options. The UK sits between the two with Crypto.com, Wirex, Nexo, and Tria available. (Ready served the EEA and UK, but its card program is currently unavailable after its card issuer began winding down.) SpendNode maintains dedicated country guides for 100+ covered markets.
Latest Page Changes to Best Crypto Cards
2026-09-26
Jupiter Global moved above Oobit in the main ranking. Jupiter's free 2% base USDC cashback with a $100 monthly reward cap offers stronger general-purpose value than Oobit's 5% stablecoin rate, which applies only to the first $200 of monthly spend and carries a heavier payment and non-USD fee stack
The custody guidance now separates control of wallet keys from card, contract, bridge, and chain risk. Gnosis Pay is identified as a closing direct-card program, while Payy is withheld from recommendation during its unresolved exploit review
2026-09-18
xPlace Gold moved lower in the main card ranking after new-member Credit Mode cashback changed to 1.5% USDC capped at $100 monthly. Its low FX and Solana self-custody remain useful, but the $249 fee limits its rewards case
2026-08-27
Corrected the Jupiter volume series after tracing a Solana collector rotation. July measured card spend is $7.5 million across the legacy and current settlement lanes, not the earlier $0.4 million legacy-only reading; the unsupported post-promotion collapse conclusion has been removed
2026-08-03
Moved the Plasma One Core Card up among our top picks after follow-up checks confirmed the full benefit stack: a self-custodial Visa Signature with 3% base cashback, up to 5% on AI spend, a ChatGPT Go rebate that offsets about half the $199 annual fee, up to 5% yield on idle stablecoin balance, discounted lounge access, car-rental insurance, and purchase, warranty, and price protection across a card available in 150+ countries
2026-07-04
Added the Xplace Gold Card to our top picks after Xplace doubled Credit Mode cashback across all tiers in July 2026, lifting Gold to an uncapped 3% USDC for $249/year on a self-custodial Solana credit line
Last modified: Oct 19, 2026 · Last verified: Oct 19, 2026 · Data sourced from official vendor documentation. · Methodology