The only crypto card that toggles between credit and debit mode in one tap.
SpendNode Rating for Nexo
3.6/5
Known for: hybrid credit and debit
Nexo still has a distinctive card model, and that keeps it relevant. The score is moderated by the same trust sensitivity that hangs over every lender-style crypto issuer after 2022.
The lineup is useful and different enough to matter. The ceiling is lower because trust is not just about features when users are parking assets on-platform.
Issuer Snapshot
Active Products1
Editorial vendor score stays separate from user reviews. Methodology
The Nexo Card is a hybrid Mastercard available in the EEA, UK, and Switzerland that toggles between Debit mode (spend your fiat, stablecoin, or FiatX balance while earning up to 14% APY paid daily) and Credit mode (borrow against crypto collateral at 1.9-13.9% APR depending on loyalty tier), offering 0.5-2% cashback in NEXO tokens or 0.1-0.5% in BTC for accounts with $5,000+ in digital assets.
Our 2026 review covers every crypto card in Europe. Most crypto cards force a choice: sell your crypto to spend (debit) or lock it up and borrow against it (credit). Nexo eliminates this trade-off with a single card that toggles between both modes in the app. Tap "Credit" and your BTC becomes collateral for instant borrowing. Tap "Debit" and you spend your EUR/GBP/FiatX balance while earning up to 14% APY on idle funds, paid daily.
This dual-mode functionality is Nexo's defining advantage and the reason it attracts a specific type of user: someone who holds significant crypto and wants to spend without selling.
Available crypto cards by Nexo in November 2026
Option 1
1. Nexo Dual Card
Credit/Debit Toggle: 2% Rewards + Up to 14% APY on Idle Balance
The Nexo Dual Card defined the crypto-backed credit category. With Free annual fee and 2% cashback, it lets you spend without selling and preserves long-term portfolio growth.
+Toggle Credit/Debit in-app
+No annual fee
+Apple Pay and Google Pay
+Tax-efficient credit spending
Nexo Card Signup Link: How to Apply
Apply through SpendNode's Nexo Card link to open a Nexo account and request the Dual Mode Card. The card has no annual fee and switches between Debit mode for spending available balances and Credit mode for borrowing against crypto; eligible accounts with at least $5,000 in digital assets can earn up to 2% cashback in NEXO tokens.
Offer detail
Current card offer
Nexo Card signup method
SpendNode's Nexo link
Card
Dual Mode Mastercard
Annual fee
$0
Cashback
Up to 2% in NEXO with $5,000+ in digital assets
Debit mode
Spend available fiat, stablecoin, or FiatX balances
Create a Nexo account and complete identity verification.
Add the required balance and open the Card section in the Nexo app.
Activate the virtual card, then choose Debit or Credit mode before spending.
Important qualifier: Cashback on all purchases requires a minimum $5,000 account balance in digital assets. Below $5,000, you earn 0% cashback regardless of tier.
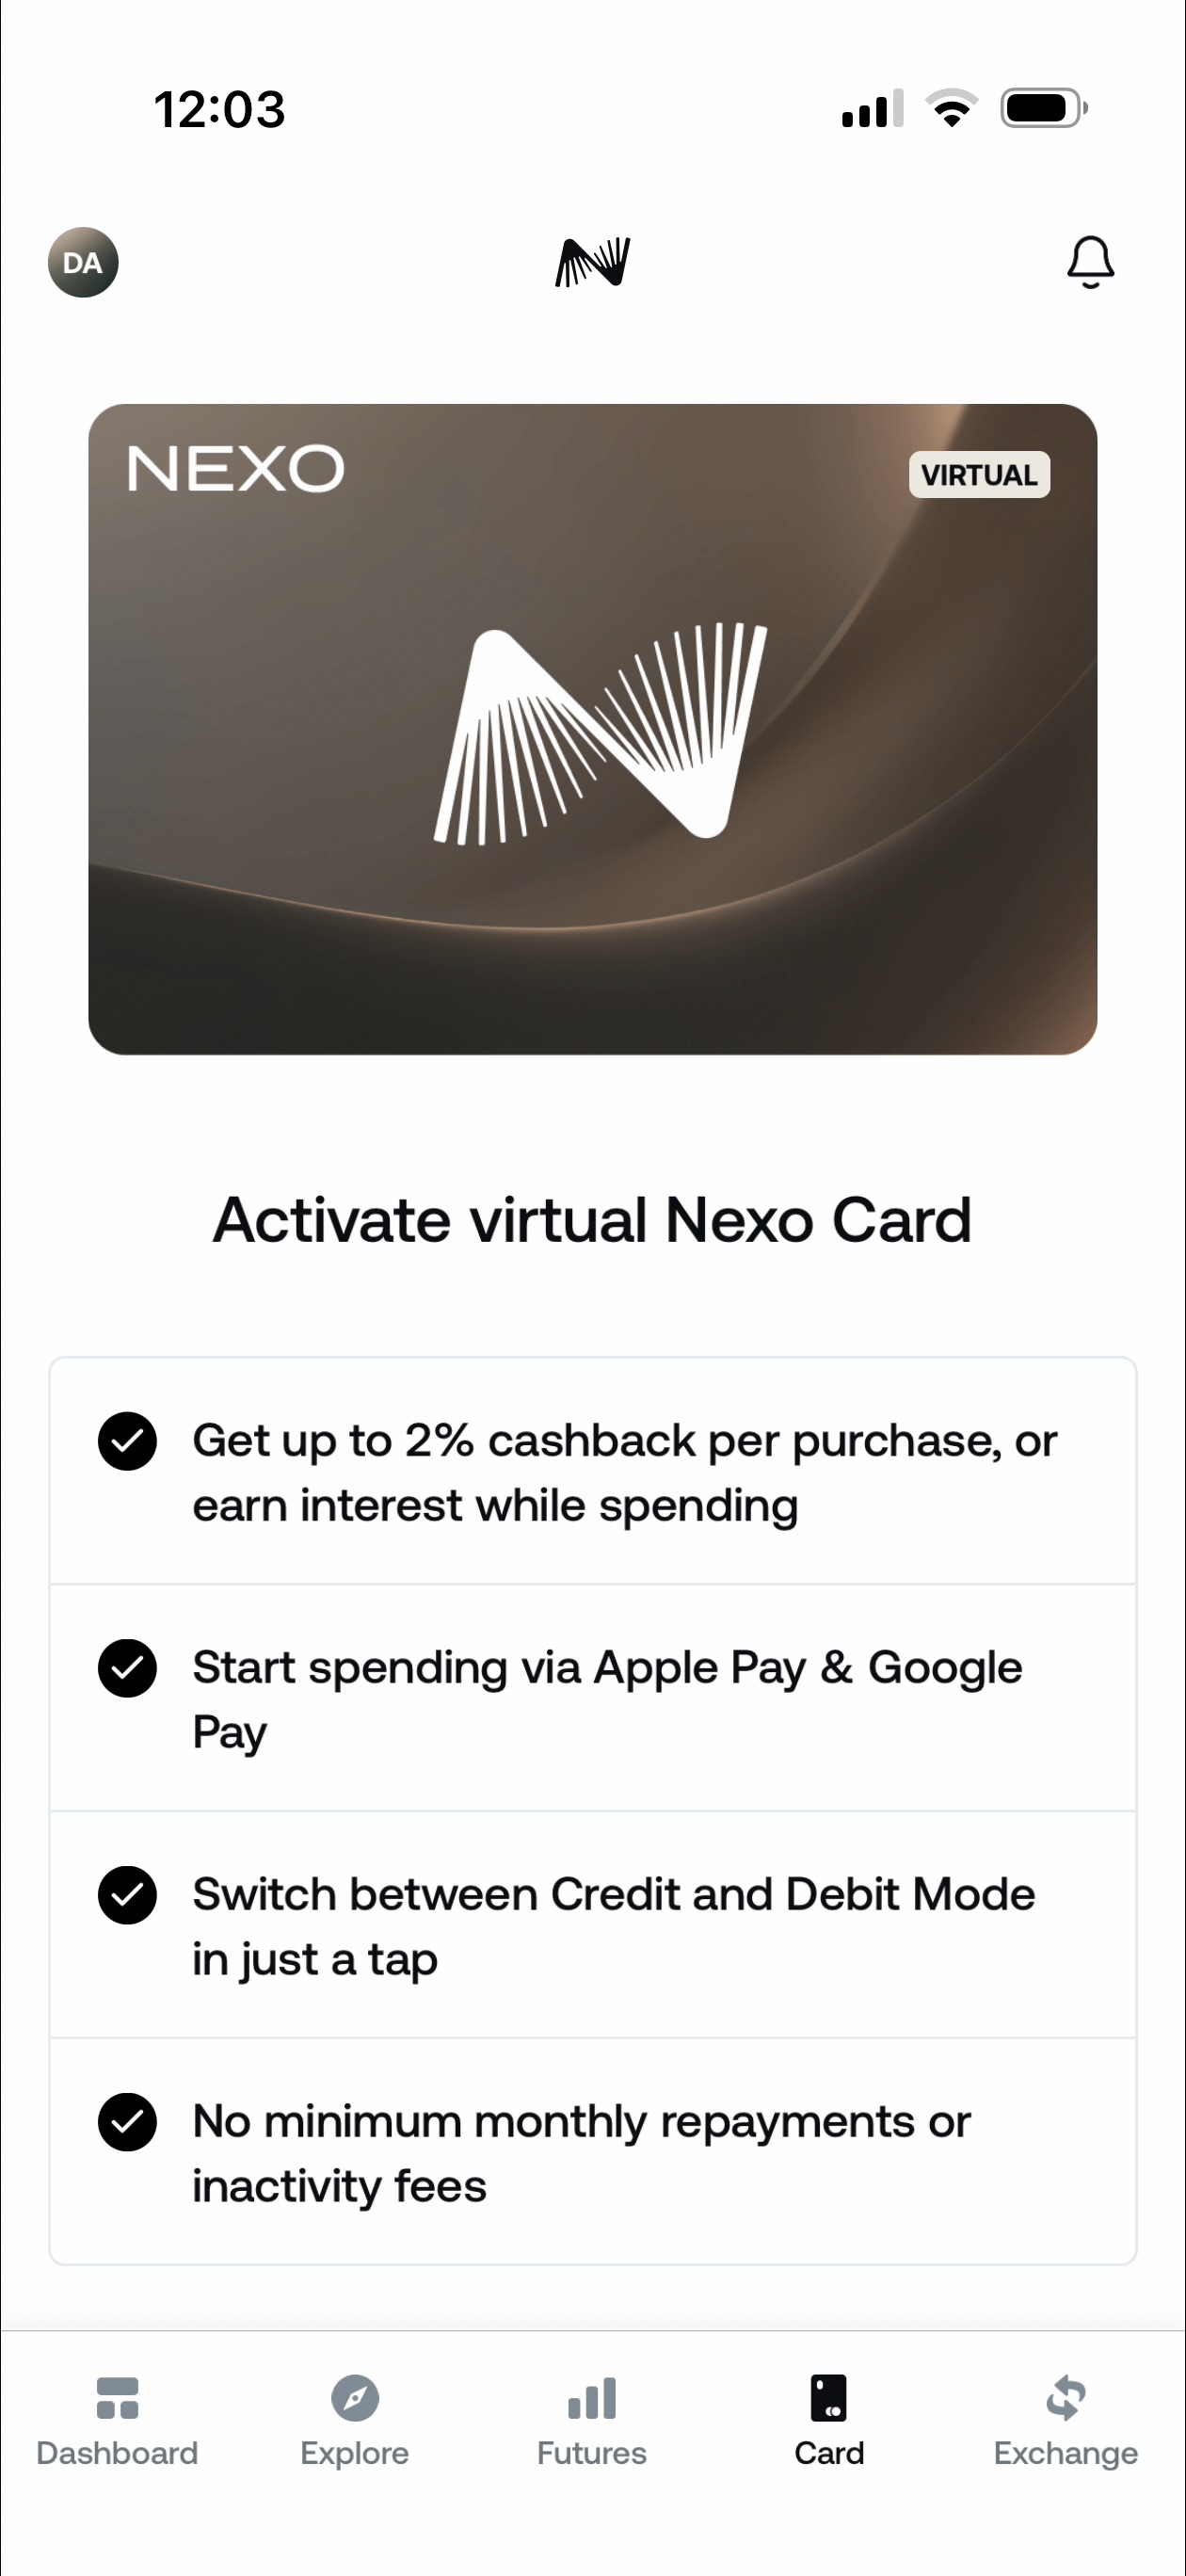
SpendNode app screenshot
Nexo Card - Up to 2% cashback (requires $5,000+ balance), Apple Pay and Google Pay, instant Credit/Debit toggle, and no minimum repayments or inactivity fees.
The Ecosystem: One Card, Two Modes
Nexo Dual Card - Free Mastercard with instant in-app toggle:
Debit Mode: Spend your available EUR, GBP, stablecoin, or FiatX (EURx, USDx, GBPx) balance. Earn up to 14% APY on idle funds, paid daily (rate depends on loyalty tier and asset). Drag-and-drop asset priority lets you choose which assets get spent first. Works like a traditional bank card with yield.
Credit Mode: Nexo uses your crypto portfolio as collateral to open an instant credit line. APR ranges from 1.9% (Platinum) to 13.9% (Base), with low-cost rates requiring LTV below 20%. No selling, no taxable event.
Card availability:
Virtual card: Instant activation with $50 minimum balance
Physical card: Ordering temporarily paused since January 17, 2025. Requires $5,000+ balance and Gold tier minimum when available
Card currency: EUR or GBP, chosen once at activation (cannot be changed)
Network: Mastercard, Apple Pay and Google Pay supported
Fees and Rates
Advertised:
$0 annual fee
Up to 2% rewards
Credit and debit toggle
Actual costs you will encounter:
$0 annual fee. FX: 0.2% weekday / 0.7% weekend (EEA/UK/CH), 2% / 2.5% (ROW) - no tier-based reduction. ATM: free up to EUR 200-2,000/month by tier, then 2% (min EUR/GBP 1.99). Credit APR: 1.9% (Platinum, LTV below 20%) to 13.9% (Base). Cashback requires $5,000 minimum balance. Credit mode loan repayment: 0.26% fee on crypto (stablecoin repayments free).
The true cost is NEXO token exposure - a 30% NEXO price drop on a $5,000 holding wipes out more than a year of net card value. ZiC (Zero-Interest Credit) is a separate collar product for BTC/ETH with 0% interest but capped upside.
Foreign Exchange Fees
FX fees apply to all tiers equally - there is no tier-based reduction:
Region
Weekday FX
Weekend FX
EEA / UK / Switzerland
0.2%
0.7%
Rest of World
2.0%
2.5%
On top of Nexo's FX fee, the Mastercard network rate applies (typically 0.2-0.4% spread vs interbank), making the effective total markup 0.4-1.1% for EEA transactions.
Credit Mode: The Real Cost of Borrowing
Standard Credit mode APR depends on your tier. The Low-Cost Credit rates (shown in the tier table above) require maintaining LTV below 20%.
Non-ZiC Scenario
Spend EUR 3,000/month
Annual Credit APR Cost
Cashback Earned
Net Position
Base (13.9%)
EUR 36,000/year
-EUR 5,004
+EUR 180 (0.5%)
-EUR 4,824
Silver (6.9%)
EUR 36,000/year
-EUR 2,484
+EUR 252 (0.7%)
-EUR 2,232
Gold (3.9%)
EUR 36,000/year
-EUR 1,404
+EUR 360 (1.0%)
-EUR 1,044
Platinum (1.9%)
EUR 36,000/year
-EUR 684
+EUR 720 (2.0%)
+EUR 36
Critical insight: Credit mode barely breaks even at Platinum (1.9% APR) and loses money at every other tier. If you cannot reach Platinum, use Debit mode or choose a different card entirely. Gold at 3.9% APR costs EUR 1,044/year more than the cashback earns.
Zero-Interest Credit (ZiC): A Separate Product
Nexo also offers Zero-Interest Credit (ZiC), a structured borrowing feature confirmed by in-app screenshots. ZiC is NOT the standard card Credit mode - it is a separate product with specific terms:
0% interest, 0% fees on borrowed amount
BTC and ETH collateral only
Fixed duration (not open-ended like standard credit)
Min-Max Repayment Price range - you set a floor and ceiling for your collateral's price at maturity
Below minimum: Your collateral settles at the minimum price (downside protection for you)
Above maximum: Your collateral settles at the maximum price (you give up upside above the cap)
Repay with BTC or USDC at maturity
ZiC is essentially a collar strategy. The "cost" of 0% interest is capping your BTC/ETH upside. If BTC rallies 100% during your ZiC term, you only benefit up to your maximum repayment price.
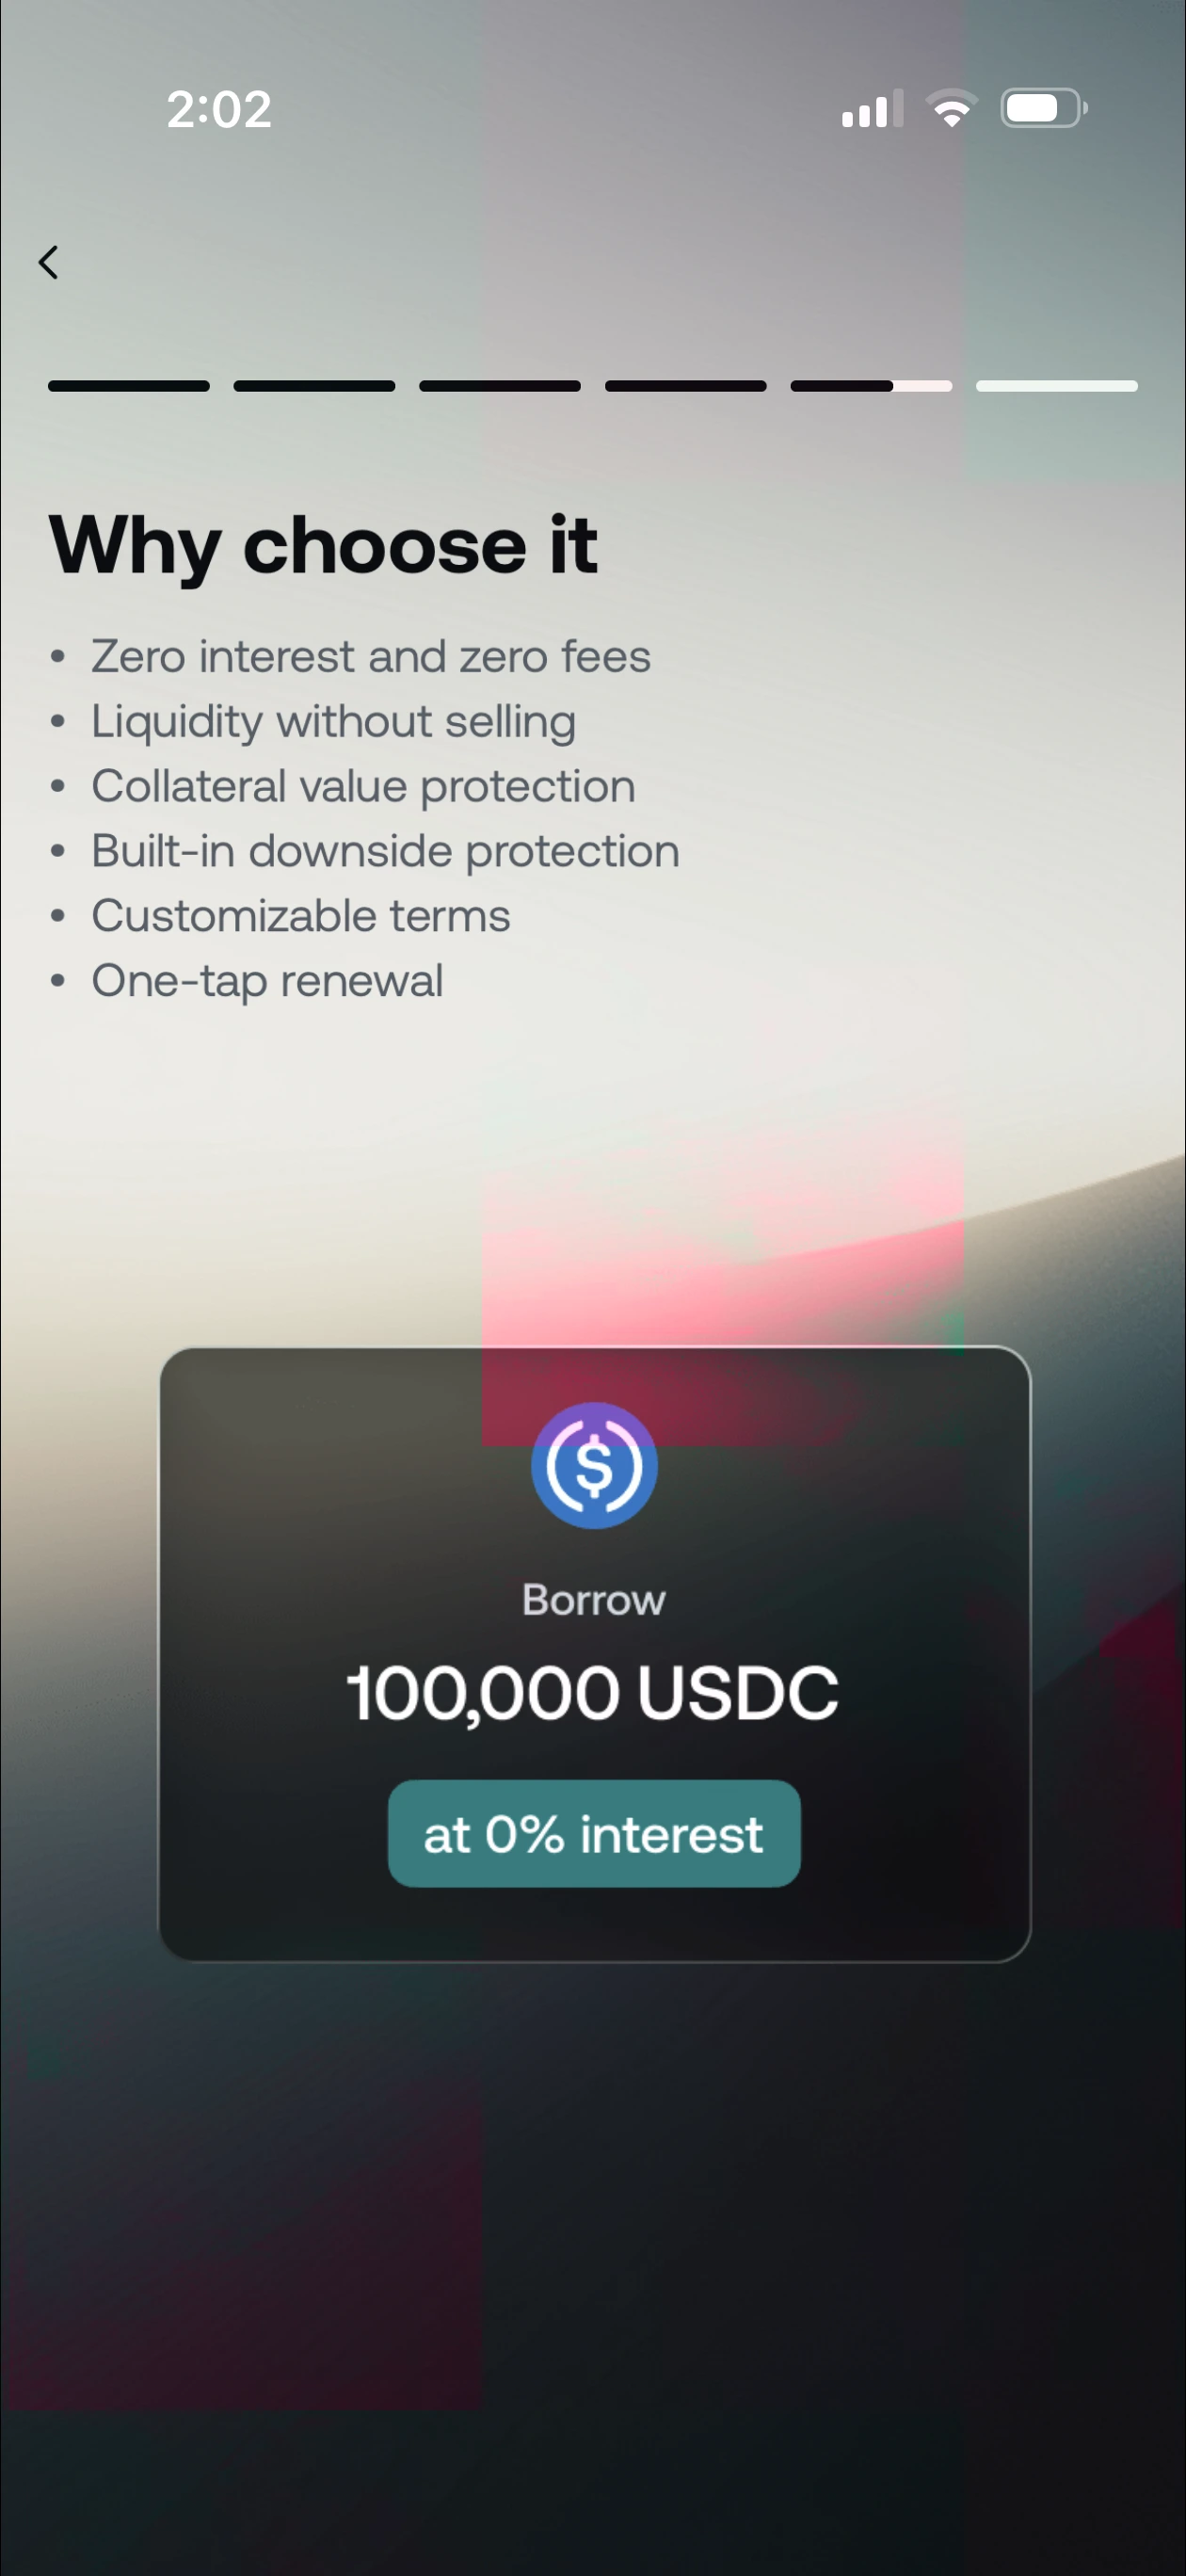
SpendNode app screenshot
Zero-Interest Credit (ZiC) - Borrow at 0% interest against BTC/ETH. The trade-off: a collar strategy that caps your upside. Example shows 100,000 USDC at 0% - but the min-max repayment price range is the hidden cost.
ATM Withdrawals
Free ATM allowance is amount-based (not count-based):
Tier
Free Monthly Limit
Over-Limit Fee
Base
EUR 200 / GBP 180
2% (min EUR/GBP 1.99)
Silver
EUR 400 / GBP 360
2% (min EUR/GBP 1.99)
Gold
EUR 1,000 / GBP 900
2% (min EUR/GBP 1.99)
Platinum
EUR 2,000 / GBP 1,800
2% (min EUR/GBP 1.99)
Loan Repayment
Credit mode purchases generate loans in xUSD. When repaying with crypto (excluding stablecoins and FIATx), a 0.26% flat fee applies. Stablecoin repayments have no fee.
Rewards and Cashback
Cashback is only available on Credit mode purchases and requires $5,000+ account balance.
Tier
NEXO Required
Cashback (NEXO)
Cashback (BTC)
Credit APR
ATM Free Limit
Base
None
0.5%
0.1%
13.9%
EUR 200/mo
Silver
1% of portfolio
0.7%
0.2%
6.9%
EUR 400/mo
Gold
5% of portfolio
1.0%
0.3%
3.9%
EUR 1,000/mo
Platinum
10% of portfolio
2.0%
0.5%
1.9%
EUR 2,000/mo
Low-Cost Credit rates (Gold 3.9%, Platinum 1.9%) require your Credit Wallet LTV to stay below 20%. Above 20% LTV, standard rates apply.
The NEXO token requirement: To reach the 2% Platinum tier, you need 10% of your Nexo portfolio in NEXO tokens. On a $50,000 portfolio, that means holding $5,000 in NEXO - a volatile small-cap token that could lose 50%+ in a downturn.
The Dual-Mode Engine
Nexo's card is powered by its lending platform, which has been operational since 2018:
Instant toggle: Switch between Credit and Debit in the Nexo app
Credit mode settlement: When you tap, Nexo instantly opens a micro-loan against your crypto, converts to fiat, and pays the merchant. Interest accrues on the loan from the moment of purchase.
Debit mode settlement: Standard fiat spending from your EUR/GBP/stablecoin/FiatX balance with drag-and-drop asset priority
3D Secure: Push notification verification for online purchases
Up to 14% APY on idle debit balances (paid daily, depending on loyalty tier and asset type) positions Nexo among the highest-yielding card accounts in the market.
Real User Scenarios
Scenario 1: Henrik (HODLer, EUR 4,000/month spend, Credit Mode)
FX fees (30% international, weekday): EUR 1,200 x 0.2% = -EUR 2.40
Net monthly value: EUR 71.27 in rewards after costs
Tax savings: Avoids capital gains on EUR 4,000/month in BTC sales
His verdict: "The tax efficiency is the real value. In Germany, selling BTC within a year triggers 26% capital gains tax. Credit mode lets me spend without selling. On EUR 48,000/year in spending, I defer thousands in potential taxes. The 2% NEXO rewards are a bonus, though I wish the FX fee were lower."
Risk: His $8,000 in NEXO tokens could lose 50%, wiping out EUR 4,000. The credit line exposes his BTC to liquidation if markets crash 40%+.
Scenario 2: Marie (Conservative, EUR 2,000/month, Debit Mode)
Setup:
Nexo Dual Card in Debit Mode
EUR 15,000 balance earning up to 14% APY (paid daily, rate varies by tier and asset)
Silver tier (1% NEXO = modest holding)
Purely domestic EEA spending
Monthly math:
Rewards: EUR 2,000 x 0.7% = EUR 14 in NEXO
APY on EUR 15K: varies by tier and asset (at Silver on stablecoins, significantly higher than traditional savings; up to EUR 175/month at the top Platinum rate)
FX fees: EUR 0 (domestic only)
Net monthly value: EUR 14 cashback + yield on idle balance = well above traditional card returns
Her verdict: "I use Debit mode exclusively. The daily yield on my idle balance earns more than my cashback rewards alone. I keep a small NEXO position for Silver tier but would not go higher - too much token risk for modest cashback improvement."
Scenario 3: Alex (Mixed Mode, GBP 3,000/month, 40% international)
Setup:
Gold tier (5% portfolio in NEXO)
Toggles between Credit (large purchases) and Debit (daily spending)
GBP 5,000 idle balance for APY
Monthly math:
Rewards: GBP 3,000 x 1.0% = GBP 30 in NEXO
APY on GBP 5K: up to 14% APY paid daily (rate varies by tier and asset; at Gold tier, yield is a meaningful addition to card returns)
FX fees (40% intl, mixed weekday/weekend): GBP 1,200 x 0.35% avg = -GBP 4.20
Credit APR cost (on GBP 1,500 credit spend): GBP 1,500 x 3.9% / 12 = -GBP 4.88
Net monthly value: GBP 30 cashback minus fees plus daily yield on idle balance
His verdict: "Credit mode for big purchases keeps my BTC untouched. Debit mode for groceries. The toggle works as advertised. The 0.2% FX adds up on my international spending, and Gold's 3.9% APR means credit mode is barely worth it."
Lesson: Nexo's value scales with your tier. Base and Silver are underwhelming. Gold breaks even on credit mode. Only Platinum (2% cashback, 1.9% APR) generates meaningful net value.
Nexo vs Other Cards
Feature
Nexo
Crypto.com
Plutus
Kraken
Credit Mode
Yes (1.9-13.9% APR)
No
No
No
Max Cashback
2% NEXO / 0.5% BTC
8% in CRO
9% in PLU
Up to 2% in BTC/EUR (tiered)
Cashback Minimum
$5,000 balance
None
None
None
Token Requirement
10% portfolio in NEXO
$500-$1M CRO stake
PLU stacking
None
APY on Idle
Up to 14% (paid daily)
0%
0%
0%
FX Fee (EEA)
0.2% weekday / 0.7% weekend
0%
0% (paid tier) / 2.5% (free)
0%
Regions
EEA, UK, CH
Global (95+)
UK, EEA
EEA, UK
Best For
Tax-efficient HODLers
Lifestyle + global
UK/EU perk maximizers
Zero-fee simplicity
After reviewing the alternatives:
Nexo wins on:
Only card with instant Credit/Debit toggle (unique in the market)
Tax efficiency in high-tax jurisdictions (Germany, France, UK) - borrowing is not a taxable event
Up to 14% APY on idle debit balances, paid daily (highest yield-on-card in the market)
No staking lockup (hold NEXO, do not stake it - sell anytime, though tier drops)
ZiC structured borrowing at 0% for BTC/ETH holders (separate feature)
Nexo loses on:
Lower reward ceiling (2% max vs 4-9% for competitors)
Requires $5,000 minimum balance for ANY cashback
FX fees on every international transaction (0.2-2.5% vs 0% for Crypto.com and Kraken)
Requires holding volatile NEXO tokens for best rates
vs Crypto.com: Crypto.com offers 2-8% CRO with staking ($500-$1M). Nexo offers 0.5-2% NEXO with portfolio allocation (no lockup). Crypto.com wins on max rewards, lifestyle perks (lounge, rebates), global availability, and 0% FX. Nexo wins on credit mode (tax efficiency), up to 14% APY on idle balances (paid daily), and no staking lockup.
vs Plutus: Plutus offers 3-9% PLU with subscription + stacking (UK/EEA). Both reward in native tokens. Plutus wins on max rewards and subscription rebates. Nexo wins on credit mode, up to 14% APY on idle balances, and no subscription fee.
vs Kraken: Krak offers up to 2% tiered cashback in BTC/EUR with zero fees, zero token requirement, no minimum balance (a variable spread applies when converting crypto or a non-primary balance). Krak wins on simplicity, 0% FX, and accessibility. Nexo wins on credit mode and reaching its 2% without a large balance.
Who Should Use Nexo?
Ideal user profile:
EEA/UK resident with significant crypto holdings ($20K+)
Account balance above $5,000 (otherwise zero cashback)
Wants to spend without selling crypto (tax efficiency)
Comfortable holding 5-10% portfolio in NEXO tokens
Values the Credit/Debit toggle for flexible spending
Lives in a high capital gains tax jurisdiction
Who should avoid:
Users who want maximum cashback (2% ceiling is modest - use Plutus 9% or Crypto.com 8%)
Users with under $5,000 on Nexo (zero cashback - use Kraken for up to 2% with no minimum)
Users who do not want NEXO token exposure (use Kraken for 0% fees and up to 2% cashback with zero token requirement)
Self-custody advocates (Nexo is hybrid custodial - consider Gnosis Pay or MetaMask)
US/APAC/LATAM residents (not available - EEA, UK, and Switzerland only)
Users who need zero FX fees (0.2%+ on every international purchase - use Crypto.com or Kraken for 0% FX)
Our take: Nexo is the most sophisticated crypto card for tax-conscious European investors with $20K+ in crypto. The Credit mode toggle is unique - no other card lets you instantly switch between spending your balance and borrowing against your portfolio. For a Platinum-tier user who spends EUR 4,000/month, the tax deferral alone can save thousands per year in high-tax jurisdictions.
The trade-off: $5,000 minimum for any cashback, 0.2%+ FX fees, holding NEXO tokens for tier benefits, and the complexity of managing a lending-backed card.
Is Nexo Safe?
Licensing:
Nexo operates through multiple EU-licensed entities
Regulated in Bulgaria (Nexo Financial LLC)
MiCA compliance in progress
Previously faced regulatory challenges in the US (settled with SEC in January 2023 over its Earn product)
Card issuance:
Card network: Mastercard
Issuer partner: Not publicly disclosed (third-party white-label)
Custody: Hybrid (fiat in regulated accounts, crypto on Nexo platform)
Operating since 2018, $8B+ in assets under management
What is protected:
Fiat balances in Debit mode (held in segregated accounts per EU electronic money regulations)
Card transactions under Mastercard's dispute resolution
What is NOT protected:
Your crypto used as collateral in Credit mode (liquidation risk is yours)
NEXO token value (volatile, subject to market conditions)
Yield on idle balances (platform-managed, not insured)
Credit mode loans (if Nexo fails during an active loan, collateral recovery is uncertain)
What Happens If Nexo Fails?
Your fiat balance (Debit Mode):
Held in segregated accounts at regulated banks
Protected under EU electronic money regulations
Expected recovery: 90-100% within 30-90 days
Your crypto on Nexo:
Risk level: Moderate-high (hybrid custodial)
Nexo maintains insurance on custodial assets via BitGo and Ledger Vault
In bankruptcy, crypto holders are unsecured creditors
This is the critical risk. If Nexo fails while you have an active loan:
Your collateral is locked on their platform
Bankruptcy proceedings could freeze collateral for months or years
You might owe the loan amount but lose access to collateral
Historical comparison: Celsius users with active loans faced 18+ months of uncertainty
Your NEXO tokens:
Would likely lose 90%+ of value if the platform fails
This compounds losses for high-tier users who hold 5-10% in NEXO
Mitigation strategy:
Keep Credit mode borrowing to amounts you could repay if collateral is frozen
Never hold more NEXO tokens than needed for your target tier
Withdraw BTC rewards to self-custody regularly
Use Debit mode for most spending; reserve Credit mode for tax-strategic large purchases
Nexo stability indicators (2026):
Operating since 2018 (8 years)
Insurance on custodial assets via BitGo and Ledger Vault
$8B+ in assets under management
SEC settlement completed (2023)
MiCA compliance in progress
No major security breaches
Is Nexo a Scam?
Nexo has been operating since 2018 as a crypto lending and earning platform, accumulating $8B+ in assets under management over 8 years. The platform has never experienced a major security breach.
The card is issued on the Mastercard network via a third-party card issuer (not publicly disclosed). Mastercard provides standard chargeback protections and zero fraud liability at 150M+ merchants.
Nexo is regulated in Bulgaria (Nexo Financial LLC) and operates through multiple EU-licensed entities. The company settled with the SEC in January 2023 over its Earn product and is pursuing MiCA compliance for the European market.
Custodial assets are insured via BitGo and Ledger Vault, providing institutional-grade security for crypto holdings on the platform. The company has achieved SOC 2 Type II certification.
The Credit/Debit toggle is a functional feature verified through in-app screenshots and user testing. The dual-mode architecture is unique in the crypto card market and has been operational for multiple years.
Up to 14% APY on idle debit balances (paid daily, tier-dependent) has been verified through app documentation. Rates are variable and depend on loyalty tier and asset type.
What to be aware of
The $5,000 minimum account balance for any cashback is a significant barrier - users below this threshold earn 0% regardless of spending volume.
Credit mode APR ranges from 1.9% to 13.9%, making borrowing-based spending unprofitable at every tier below Platinum.
The NEXO token concentration requirement (10% of portfolio for Platinum) creates token exposure risk.
FX fees apply to all international transactions (0.2-2.5%) with no tier-based reduction.
Physical card ordering has been paused since January 2025.
The card is available only in the EEA, UK, and Switzerland - not globally.
Credit mode carries liquidation risk if crypto collateral drops significantly.
SpendNode Verified: The editorial team reviewed Nexo's issuer identity, product terms, and live card flow per our methodology. Verification is not an endorsement or guarantee.
Countries and Availability
Nexo is available in 32 countries as of November 2026. We count a country here when at least one active Nexo card variant lists it, so individual product pages may be narrower.
Available Regions
Europe
Austria (AT), Belgium (BE), Bulgaria (BG), Croatia (HR), Cyprus (CY), Czech Republic (CZ), Denmark (DK), Estonia (EE), Finland (FI), France (FR), Germany (DE), Greece (GR), Hungary (HU), Iceland (IS), Ireland (IE), Italy (IT), Latvia (LV), Liechtenstein (LI), Lithuania (LT), Luxembourg (LU), Malta (MT), Netherlands (NL), Norway (NO), Poland (PL), Portugal (PT), Romania (RO), Slovakia (SK), Slovenia (SI), Spain (ES), Sweden (SE), Switzerland (CH), United Kingdom (GB)
Major Restricted Markets
These major markets are not currently listed for this vendor. Confirm eligibility with the issuer before applying, especially where card tiers have different country rules.
Africa
Egypt (EG), Kenya (KE), Nigeria (NG), South Africa (ZA)
Americas
Argentina (AR), Brazil (BR), Canada (CA), Chile (CL), Colombia (CO), Mexico (MX), United States (US)
Asia
China (CN), Hong Kong (HK), India (IN), Indonesia (ID), Japan (JP), Malaysia (MY), Philippines (PH), Singapore (SG), South Korea (KR), Taiwan (TW), Thailand (TH), Turkey (TR), United Arab Emirates (AE)
Oceania
Australia (AU), New Zealand (NZ)
Our Verdict on Nexo
Nexo's card is two products on one piece of plastic, and both have an entry price. Cashback of any kind requires $5,000 in digital assets on the platform; below that the card earns nothing. Above it, Debit mode spends balances that keep earning up to 14% APY paid daily, while Credit mode borrows against crypto from 1.9% APR at Platinum with low loan-to-value, up to a punishing 13.9% at Base.
The borrow-instead-of-sell design earns its keep for EEA, UK, and Swiss holders with meaningful portfolios who understand collateral math, and the 0.2% weekday FX is among the lowest around. Respect the two caveats: rewards arrive mostly in NEXO, so a token drawdown can erase a year of card value, and physical cards have been paused since January 2025, so this card lives in your phone.
Is Nexo crypto card available in the United States?
No. Nexo crypto card is not available in the United States.
What is Zero-Interest Credit (ZiC)?
ZiC is a separate structured borrowing feature where you borrow against BTC or ETH at 0% interest for a fixed duration. You set a min-max repayment price range: if the collateral price falls below the minimum, it settles at the floor (downside protection). If it rises above the maximum, it settles at the cap (you give up upside). ZiC is NOT the standard card Credit Mode APR, which is 1.9% (Platinum) to 13.9% (Base).
Is the Nexo Card a credit card or debit card?
Both. The Nexo Dual Card is a hybrid Mastercard that toggles between Debit mode (spend your fiat/stablecoin balance) and Credit mode (borrow against your crypto portfolio). In Credit mode, the APR depends on your loyalty tier: 1.9% for Platinum, 3.9% for Gold, up to 13.9% for Base. No taxable disposal event occurs in Credit mode since you are borrowing, not selling.