
Xplace Crypto Cards Review 2026
Compare Xplace crypto cards and review issuer terms, fees, and availability.
SpendNode Rating for Xplace
xPlace combines Solana self-custody, a Kamino credit line, and tiered USDC cashback in Credit Mode. Rewards run from 0.5% to 2% with monthly caps, so the paid tiers depend on FX and perks rather than rate alone.
The working Kamino credit line, 0% transaction fee, and low FX on paid tiers are useful. Credit Mode cashback is capped and Cash Mode pays none, while annual membership fees narrow the net rewards case. Repeated repricing still weighs on stability.
Issuer Snapshot
Editorial vendor score stays separate from user reviews. Methodology
Product Quality
4.0
Trust & Custody
3.7
Fee Transparency
3.9
Operational Reliability
3.7
Market Relevance
3.8
On This Page
Current cashback for new memberships: Basic earns 0.5% in Credit Mode; Silver, Gold, and Platinum earn 1%, 1.5%, and 2%. Cash Mode earns no card cashback. Paid memberships purchased before 14 September 2026 can retain their earlier rates for up to 12 months from purchase. Current in-app membership screens show monthly cashback limits of $10, $40, $100, and $250 by tier.
What Is Xplace?
Xplace (stylized as x.place) is a non-custodial crypto credit card built on Solana. You deposit assets into Kamino Finance, they earn variable yield and act as collateral, and you borrow USDC against them to spend through the card. Nothing is sold, so you keep your underlying position.
Membership runs across four tiers - Basic (free), Silver ($99/year), Gold ($249/year), and Platinum ($999/year) - with 0.5-2% USDC cashback in Credit Mode for new members, a 0% card transaction fee on every tier, and FX that falls to 0% at the top. Variable borrowing interest and monthly cashback limits affect what cardholders actually keep.
This is a different product from the Solana debit card Xplace launched as. The card is now a borrow-to-spend credit line, closer in shape to ether.fi or Nexo than to a top-up debit card. The card itself is issued through Card Partner Rain (Signify Holdings, Inc.), and the platform is operated by Pontech Group L.L.C-FZ in Dubai, with terms governed by UAE law and DIAC arbitration. The app's own footer draws the same line: the card program is not affiliated with the xPlace protocol and runs under separate issuer terms.
Available crypto cards by Xplace in September 2026
1. Xplace Basic Card
Free Visa Entry, with 10% Off a Paid Upgrade Using SPENDNODE
2. Xplace Silver Card
10% Off Silver with SPENDNODE: Pay $89.10 Instead of $99
3. Xplace Gold Card
10% Off Gold with SPENDNODE: Pay $224.10 Instead of $249
4. Xplace Platinum Card
10% Off Platinum with SPENDNODE: Pay $899.10 Instead of $999
Xplace Card Promo Code SPENDNODE: 10% Off Memberships
xPlace created promo code SPENDNODE for SpendNode readers. It takes 10% off Silver, Gold, or Platinum membership. The free Basic tier has no membership price to reduce.
Paid memberships purchased before 14 September 2026 can keep their earlier rates for up to 12 months from purchase: 2% Credit Mode and 1% Cash Mode on Silver, 3% and 1.5% on Gold, and 4% and 2% on Platinum. The 10% membership discount is still available to new buyers, but it does not confer those protected rates. Check the rate shown for your specific membership before paying.
| Membership | Standard price | Price with SPENDNODE |
|---|---|---|
| Basic | $0 | $0 |
| Silver | $99 | $89.10 |
| Gold | $249 | $224.10 |
| Platinum | $999 | $899.10 |
How to use the Xplace promo code
- Open xPlace through SpendNode's promo-code link. The deep link applies SPENDNODE automatically.
- Create or sign in to your xPlace account and complete the required verification.
- Choose Silver, Gold, or Platinum membership.
- Confirm that the checkout price includes the 10% discount before paying. You can enter SPENDNODE manually if the code is not already shown.
The discount reduces the membership price. Deposit, spending, and eligibility requirements attached to each tier's separate XP and cashback welcome package still apply.
How the Credit Line Works
Every tier shares the same mechanics:
- Deposit supported assets into Main Assets, which routes them into Kamino Finance smart contracts on Solana.
- Earn variable yield on those deposits while they sit as collateral.
- Borrow USDC against the collateral, up to each asset's loan-to-value limit.
- Spend in Credit Mode (drawing on the borrowed USDC) or Cash Mode (spending deposited USDC directly), with no fixed repayment schedule.
Because Kamino holds the assets, Xplace cannot move or access your collateral - and it cannot pause or reverse a liquidation if your collateral value falls below the protocol threshold. That is the core trade-off of a non-custodial credit line: you keep control, but the protocol, not a support desk, enforces the math.
Supported Collateral and LTV
| Asset | Loan-to-Value |
|---|---|
| USDT | 80% |
| cbBTC (Bitcoin) | 70% |
| wETH (Ethereum) | 70% |
| SOL | 65% |
| jitoSOL | 50% |
Deposit $10,000 of SOL and you unlock roughly $6,500 of USDC credit while the SOL keeps earning Kamino yield. Borrow APR is variable, sourced from Kamino's live market, and shown in the app before you draw.

SpendNode app screenshot
The in-app Main Assets view shows each asset's live APY beside its LTV (SOL 65%, wETH and cbBTC 70%, jitoSOL 50%, USDT 80%), with crypto transfer, bank transfer, and Apple Pay deposit options on the same screen.
The Four Membership Tiers
- Basic - Free. Virtual Visa card, 0.5% Credit Mode cashback (up to $10/month), 1% XP, $2,000/month and $1,000/transaction spending limits.
- Silver - $99/year. Physical card, 1% Credit Mode cashback (up to $40/month), 3% XP, 0.5% FX, one lounge visit/year. Xplace's current homepage lists a $20,000 monthly spending limit, while its membership page and our app capture show $10,000; check your account's limit.
- Gold - $249/year. Metal card, 1.5% Credit Mode cashback (up to $100/month), 6% XP, 0.25% FX, four lounge visits and two fast-track passes/year, $200,000/month spending limit.
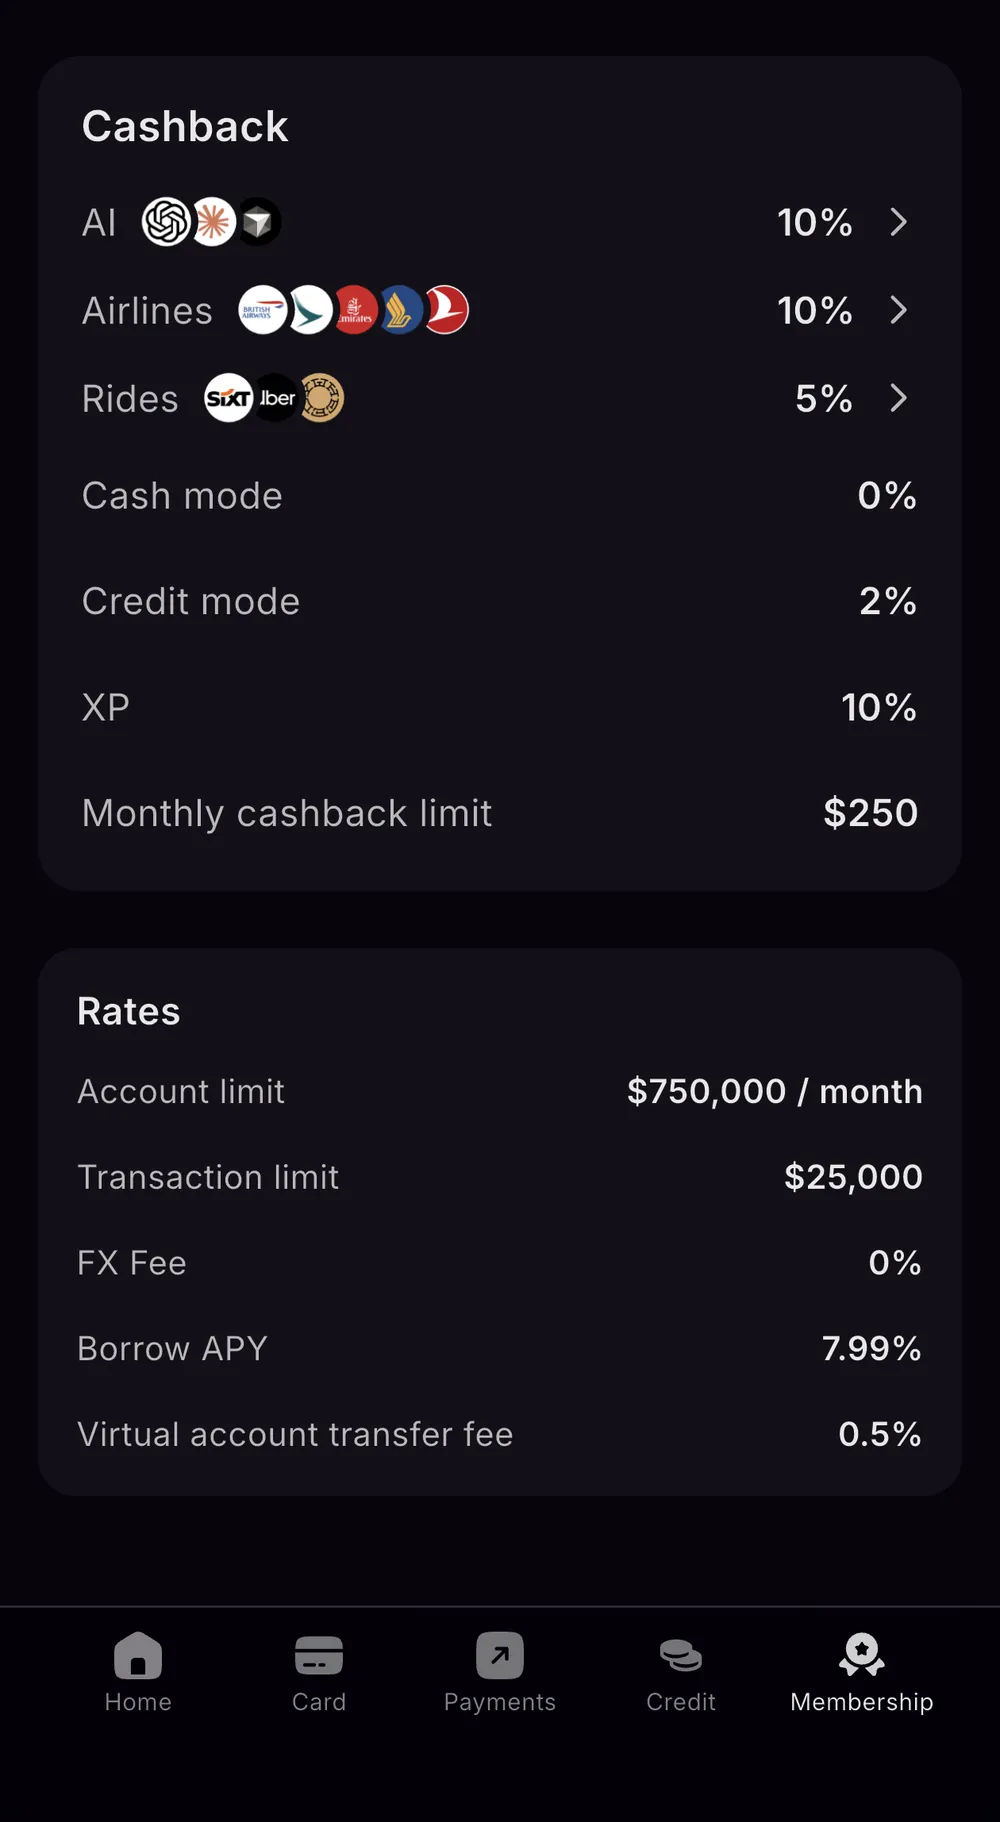
- Platinum - $999/year. Mirror metal card, 2% Credit Mode cashback (up to $250/month), 10% XP, 0% FX, unlimited lounges, five fast-track passes, private concierge, VIP events, $750,000/month spending limit.
Fees and Rates
The fee structure changed completely from Xplace's debit era. The card transaction fee is now 0% on every tier, and FX scales down as you move up. That removes the old drag that used to make the entry tiers net-negative.
| Fee | Basic | Silver | Gold | Platinum |
|---|---|---|---|---|
| Annual fee | $0 | $99 | $249 | $999 |
| Card transaction fee | 0% | 0% | 0% | 0% |
| FX fee | 1% | 0.5% | 0.25% | 0% |
| Credit Mode USDC cashback, new memberships | 0.5% | 1% | 1.5% | 2% |
| Cash Mode cashback, new memberships | 0% | 0% | 0% | 0% |
| Monthly cashback cap | $10 | $40 | $100 | $250 |
| XP cashback | 1% | 3% | 6% | 10% |
| Monthly spending limit | $2K | $10K in app / $20K on homepage | $200K | $750K |
| Per-transaction limit | $1K | $3K | $10K | $25K |
There is no card transaction fee, but that does not make the headline cashback a net return. Basic's 1% FX fee exceeds its 0.5% Credit Mode rate on foreign purchases. Borrowing interest, annual membership fees, category exclusions, and monthly cashback caps also reduce the return. Platinum has no FX fee, though its $999 annual fee still matters.
Cashback is paid in USDC on Credit Mode spending, which is how the card is designed to be used day to day - you spend against your collateral, the purchase clears, and the cashback lands. Per Xplace's Terms (section 6.4), it accrues from Credit Mode transactions and on-platform trading activity.
Cash Mode earns no card cashback for new memberships. Pre-14 September paid memberships may retain their protected Credit Mode and Cash Mode rates for up to 12 months from purchase; check the rate attached to your account rather than assuming the public tier display applies to you.
Tiered booking cashback on hotels and flights is separate (1% Silver, 2% Gold, 5% Platinum). Some merchant categories are excluded from card cashback entirely, including cash and ATM, money transfer, crypto purchases, and securities or insurance.
Category Boosts on the Paid Tiers
The paid tiers add merchant-category boosts on top of the flat rates. Each boost applies to Credit Mode spending at named merchants, with its own monthly spend cap that resets on the calendar month:
| Category | Merchants | Silver | Gold | Platinum | Monthly cap |
|---|---|---|---|---|---|
| Rides | Sixt, Uber, Wheely | 3% | 5% | 5% | $500 of spend |
| AI | ChatGPT, Claude, Cursor | - | 5% | 10% | $250 of spend |
| Airlines | British Airways, Cathay Pacific, Emirates, Singapore Airlines, Turkish Airlines, United | - | - | 10% | $500 of spend |
The caps keep the math honest. Platinum's 10% on airlines is worth at most $50 a month, and the AI boost tops out at $25 (Platinum) or $12.50 (Gold). These are meaningful sweeteners on spend most cardholders already have, not a reason to pick a tier by themselves. Basic gets none of the boosts, and the airline boost applies to direct airline purchases, separate from the in-app hotel and flight booking cashback.
SpendNode app screenshot
The September 2026 membership screen shows the current Platinum rates for new buyers alongside the category boosts, monthly cashback cap, spending limits, and fees. The displayed borrowing APY is a snapshot, not a fixed rate.
Break-Even by Tier
| Tier | Annual fee | New Credit Mode rate | Spend to cover annual fee | Monthly target |
|---|---|---|---|---|
| Basic | $0 | 0.5% | No fee | None |
| Silver | $99 | 1% | $9,900/yr | $825/mo |
| Gold | $249 | 1.5% | $16,600/yr | $1,383/mo |
| Platinum | $999 | 2% | $49,950/yr | $4,163/mo |
These are annual-fee break-evens on eligible Credit Mode purchases, assuming each month's cashback remains below the tier cap. They exclude variable borrowing interest, FX, and the 10% SPENDNODE membership discount. The caps mean more spend does not always produce more cashback: Basic stops at $10, Silver at $40, Gold at $100, and Platinum at $250 each month.
Yield on Deposits
Deposits earn variable yield through Kamino's main market. The rate depends on borrowing demand for each asset, so the APY shown in the app is a snapshot rather than a return you can lock in.
Check the live rate for the asset you plan to deposit; a strong rate on SOL does not imply the same return on cbBTC or USDT.
Yield also carries protocol risk. In early April 2026, before the move to Kamino, Xplace disclosed exposure to the Drift exploit: about $544,000 of collateral and $152,000 of loans, for net TVL near $392,000, including roughly $113,000 of team capital. The savings and credit stack now runs on Kamino, but the lesson stands - depositing into any DeFi protocol means accepting that protocol's exploit, insolvency, and liquidation risk, which Xplace's own Terms disclaim in full.
Rewards and Cashback
Xplace runs two reward tracks. USDC cashback is paid in stablecoins on eligible Credit Mode purchases, at 0.5% to 2% for new memberships, subject to monthly caps. XP is a loyalty point earned through card usage, deposits, and referrals, scaling 1% to 10% by tier.
Not every purchase qualifies, and Xplace does not publish an exclusion list. In our testing, a monthly insurance premium paid with our Xplace card earned no cashback - the same premium did earn on Tria. Assume category exclusions exist (financial services being the usual suspect) and watch your first statements before routing bill-type payments through the card.
Xplace has announced a token generation event (TGE) for Q4 2026, with XP weighting your allocation. The published allocations earmark 5% to ecosystem partners (Seeker, Superteam, cherry.fun) and 2.5% to NFT communities and DAOs (Claynosaurz, MonkeDAO, Lucid Drakes, Solana Sensei, Dead King Society). Xplace's Terms still carry the usual pre-launch hedge that no token has been issued yet, so XP value is not locked in until the event lands - but the TGE has been announced widely, not left vague.
Tier upgrades also carry early-bird XP bonuses (Silver +10,000, Gold +20,000, Platinum +100,000), and each paid tier adds a welcome offer of up to 25,000/100,000/200,000 XP plus a $50-$500 cashback bonus for meeting deposit and spend targets in the first months - the details sit on each tier's review page.
The referral program pays up to $250 per referral depending on the referred user's tier, plus 1% of their transaction activity.
SpendNode app screenshot
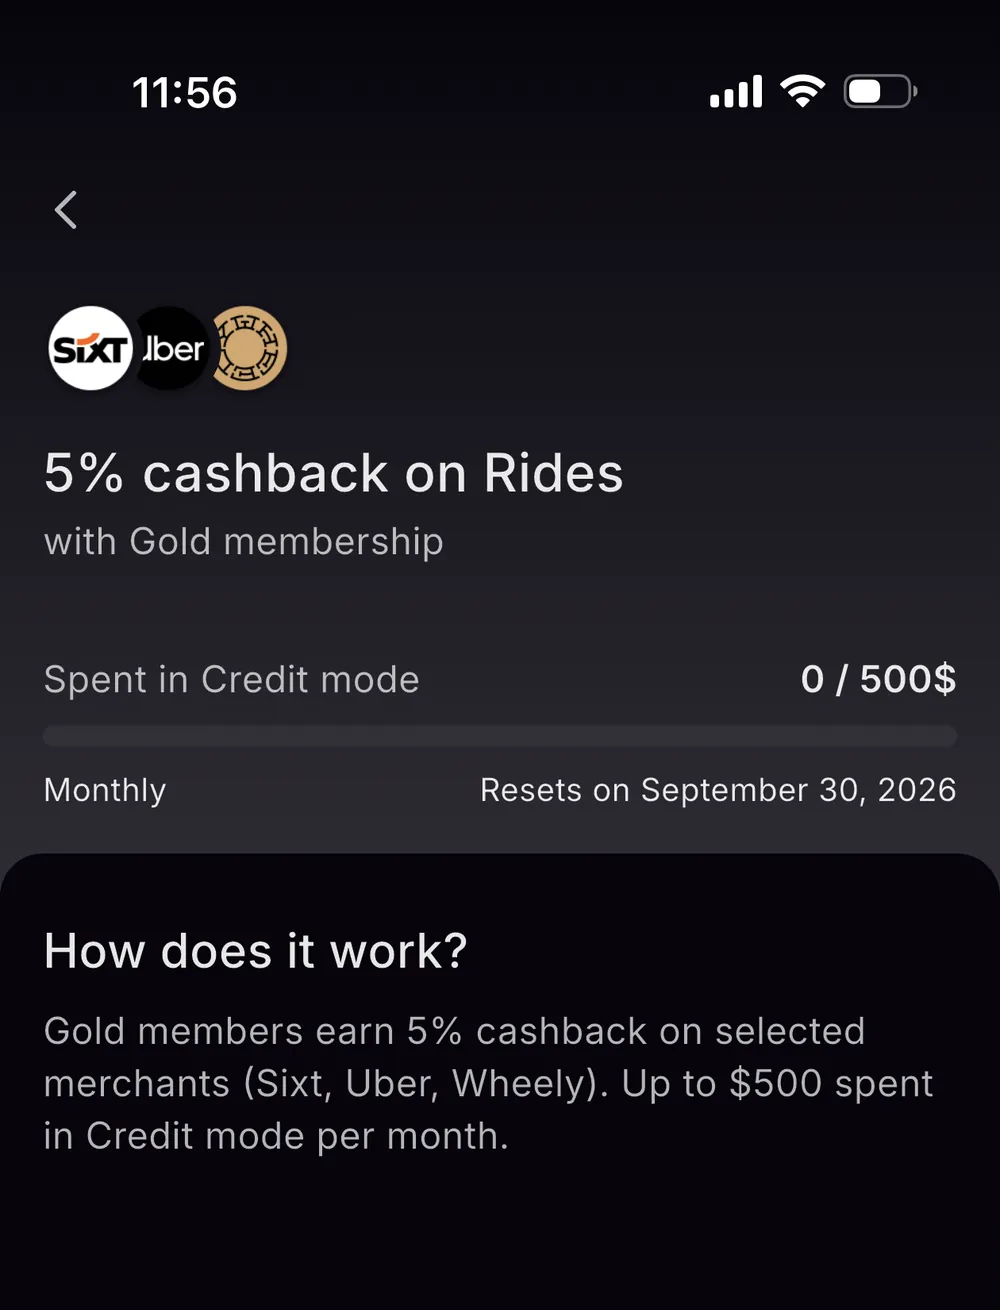
The category boosts get their own tracking screens in the app. Gold's rides boost pays 5% at Sixt, Uber, and Wheely, with a progress bar against the $500 monthly Credit Mode spend cap and a calendar-month reset date.

SpendNode app screenshot
Travel rewards sit alongside the card: up to 5% cashback on in-app hotel bookings (by tier), plus the lounge and fast-track access that scales from Silver to Platinum.
A Global Bank Account Too
Beyond the card, Xplace now offers a banking layer: hold and send in USD, EUR, and BRL with IBAN and local rails across 160+ countries. This pushes Xplace past a pure card product toward an account you can route salary, transfers, and spending through, with the crypto credit line attached. Bank transfer fees are tiered (2% Basic down to 0.5% Platinum).

SpendNode app screenshot
The Global Bank Account screen: hold and transfer USD, EUR, and BRL over IBAN and local rails across 160+ countries, sitting in the same app as the card and credit line.
Field Notes From Testing
Deposit address marked one-time use
Xplace labels USDC deposit addresses as one-time use and tells users not to reuse them. In our testing we deposited once, returned to top up minutes later, and the app still showed the same address; a second deposit to it was credited in our case. That does not mean reuse is safe or intended.
Generate a fresh deposit address for every transfer, wait for the app to refresh, and do not save old Xplace deposit addresses in your wallet's address book. Xplace does not explain why the addresses are one-time, so we would be cautious sending larger amounts to a reused one.
Support responsiveness
In our December testing, Xplace support was not responsive enough for a product moving real money. We raised an account issue, shared the requested username, followed up, were told the team was working on it, and never received a substantive reply. Support quality is part of the product for anything handling deposits and a credit line, so weigh it as a real factor.
What Happens If Xplace Fails?
Xplace is non-custodial, which changes the failure question compared to an exchange card.
Your collateral sits in Kamino Finance smart contracts on Solana, not with Xplace. If the company shut down, your deposited SOL, wETH, cbBTC, jitoSOL, or USDT would still be in Kamino, governed by the protocol rather than by Xplace's solvency. That is the structural advantage over custodial exchange cards, where a platform collapse (FTX, Celsius) can freeze the whole balance.
The exposure that does matter is the protocol. Because the credit line and yield run on Kamino, your risk is a Kamino smart-contract exploit, an oracle failure, or a sharp collateral-value drop that triggers an automatic liquidation Xplace cannot pause or reverse. Xplace disclosed this exact category of risk during its Drift exposure in the April 2026 exploit, before migrating the stack to Kamino.
Your Credit Mode balance is a USDC loan against that collateral. A wind-down would not erase a drawn loan; it stays backed by, and settled against, your on-chain position.
Your XP is the one balance fully dependent on Xplace continuing to operate. It lives in Xplace's systems, so if the company folds before the Q4 2026 TGE, accumulated XP could be worthless.
The card itself is issued through Card Partner Rain (Signify Holdings, Inc.); card access would stop if the program ended, but that does not touch your Kamino collateral.
The net: a company failure is far less damaging here than on a custodial card, because your assets are in Kamino. The trade-off is the DeFi protocol and liquidation risk a custodial card does not carry.
Xplace vs Other Cards
| Feature | Xplace Basic | ether.fi Core | Solflare (paused Jul 2026) | MetaMask Virtual |
|---|---|---|---|---|
| Annual fee | $0 | $0 | $0 | $0 |
| Model | Borrow-to-spend (credit) | Borrow-to-spend (credit) | Spend (debit) | Spend (debit) |
| Credit Mode cashback | 0.5% (up to $10/month) | 3% | Raffle | 1% |
| Card transaction fee | 0% | 0% | 0% | 0% |
| FX fee | 1% | 1% | 1% | 0% |
| Borrowing cost | Variable | Variable | None | None |
| Collateral / yield | SOL, ETH, BTC, USDT via Kamino | Staked ETH | No | No |
| Blockchain | Solana | Ethereum | Solana | Multi-chain |
On raw free-tier cashback, ether.fi Core's 3% headline rate exceeds Xplace Basic's 0.5%. Xplace's case is different: it is a Solana-native credit line with a free entry tier and a broader collateral set. The annual fees, cashback caps, and variable borrowing cost make its paid tiers harder to justify on cashback alone. Solflare has been paused since July 2026.
Real User Scenarios
Maya, a free-tier domestic spender (Basic, about $1,200/month, mostly USD). She deposits USDC and some SOL as collateral and spends in Credit Mode. At 0.5%, $1,200 of eligible spend would produce $6 a month, or $72 a year before borrowing interest. That is below Basic's $10 monthly cashback cap. She pays no annual fee, but the variable cost of her USDC loan could erase the card reward.
Diego, a Gold traveler (about $3,500/month, 40% abroad). He pays $249/year for Gold to get 0.25% FX and four annual lounge visits. At 1.5%, eligible spending would earn $52.50 a month, below Gold's $100 monthly cashback cap. That is $630 a year before $42 of FX on roughly $16,800 of foreign spend and the $249 membership fee. The remaining $339 also has to cover his variable borrowing interest before he comes out ahead.
Lena, an ETH holder using Credit Mode (Platinum, about $6,000/month). She holds wETH and cbBTC and does not want to sell, so she deposits them into Kamino, borrows USDC against her collateral, and spends on Platinum ($999/year) at 2% cashback and 0% FX, with unlimited lounges and concierge.
On $72,000 of eligible yearly spend, 2% cashback is $1,440, or $441 after the annual fee, assuming she stays below the $250 monthly cashback cap. Against that she pays Kamino's variable borrow APR on the drawn USDC and carries liquidation risk if ETH or BTC drops sharply.
These are composite scenarios for illustration.
Who Should Use Xplace?
Use Xplace if:
- You hold SOL, ETH, BTC, or USDT and want to spend against them without selling your position
- You want a Solana-native credit line with a free entry tier and can manage the borrowing risk
- You value FX down to 0% on Platinum for travel
- You want a crypto-linked account with IBAN and multi-currency transfers attached
Look elsewhere if:
- You want the highest free headline cashback: ether.fi Core pays 3%, subject to its own borrowing costs and terms
- You are uncomfortable with DeFi liquidation risk: a price drop in your collateral can trigger an automatic, irreversible liquidation on Kamino
- You are spending abroad on Basic, where its 1% FX fee exceeds its 0.5% Credit Mode cashback
- You are buying XP expecting a locked-in payout: the TGE is targeted for Q4 2026 but not yet live, so XP value is not guaranteed until it happens
Our take: Xplace combines a Solana credit line with card rewards, but 0.5-2% Credit Mode cashback for new memberships must be weighed against monthly caps, annual fees, and variable interest. The larger decision is whether borrowing against collateral fits your finances and risk tolerance.
Basic avoids a membership fee but is not automatically profitable. Silver and Gold need meaningful eligible spend to cover their fees; Platinum's 0% FX, lounge access, and concierge may matter more than its cashback once the $999 fee is counted.
How to Apply for an Xplace Crypto Card
Setting up an Xplace card takes a few minutes in the app, and there is no bank-style credit check anywhere in it. The credit line is opened against your own collateral, not your income or score. Here is the flow from sign-up to first payment:

SpendNode app screenshot
Onboarding starts with a free virtual Visa and a choice of sign-up method: Apple, Google, or email.
- Create your account. Sign up with an email address, or connect a Google or Apple ID for a one-tap start.
- Secure it. Set a six-digit PIN and enable Face ID so logins and payments clear without a password.
- Pick a username. Other Xplace users can send you funds by username, so choose one you are comfortable sharing.
- Choose a membership. Select Basic, Silver, Gold, or Platinum. Your tier sets cashback, FX rate, limits, and lifestyle perks, and you can move up later.
- Pass KYC. Verify your identity with a passport or national ID plus proof of residency. In our run this was a routine document-and-selfie check, not a financial background check.
- Open your credit line. Deposit supported collateral (SOL, jitoSOL, USDT, or ETH and BTC as wETH and cbBTC) into Main Assets. Xplace routes it into Kamino, and one tap shifts part of your balance from cash into collateral so you can borrow USDC against it.
- Issue the card and pay. Set a card PIN and your virtual Visa is created instantly. Add it to Apple Pay or Google Pay, then spend in Credit Mode against your collateral or Cash Mode from your USDC balance.
Countries and Availability
Xplace is available in 98 countries as of September 2026. We count a country here when at least one active Xplace card variant lists it, so individual product pages may be narrower.
Available Regions
Africa
Cameroon (CM), Cote d'Ivoire (CI), Egypt (EG), Ethiopia (ET), Ghana (GH), Kenya (KE), Morocco (MA), Mozambique (MZ), Nigeria (NG), Rwanda (RW), Senegal (SN), South Africa (ZA), Tanzania (TZ), Tunisia (TN), Uganda (UG)
Americas
Argentina (AR), Bolivia (BO), Brazil (BR), Canada (CA), Chile (CL), Colombia (CO), Costa Rica (CR), Dominican Republic (DO), Ecuador (EC), El Salvador (SV), Guatemala (GT), Jamaica (JM), Mexico (MX), Panama (PA), Paraguay (PY), Peru (PE), Puerto Rico (PR), Trinidad and Tobago (TT), United States (US), Uruguay (UY)
Asia
Bahrain (BH), Bangladesh (BD), Cambodia (KH), Georgia (GE), Hong Kong (HK), Indonesia (ID), Japan (JP), Jordan (JO), Kazakhstan (KZ), Kuwait (KW), Lebanon (LB), Malaysia (MY), Mongolia (MN), Oman (OM), Pakistan (PK), Philippines (PH), Qatar (QA), Saudi Arabia (SA), Singapore (SG), South Korea (KR), Sri Lanka (LK), Taiwan (TW), Thailand (TH), United Arab Emirates (AE), Uzbekistan (UZ)
Europe
Albania (AL), Austria (AT), Belgium (BE), Bulgaria (BG), Croatia (HR), Cyprus (CY), Czech Republic (CZ), Denmark (DK), Estonia (EE), Finland (FI), France (FR), Germany (DE), Greece (GR), Hungary (HU), Iceland (IS), Ireland (IE), Italy (IT), Latvia (LV), Lithuania (LT), Luxembourg (LU), Malta (MT), Montenegro (ME), Netherlands (NL), North Macedonia (MK), Norway (NO), Poland (PL), Portugal (PT), Romania (RO), Serbia (RS), Slovakia (SK), Slovenia (SI), Spain (ES), Sweden (SE), Switzerland (CH), United Kingdom (GB)
Oceania
Australia (AU), Fiji (FJ), New Zealand (NZ)
Major Restricted Markets
These major markets are not currently listed for this vendor. Confirm eligibility with the issuer before applying, especially where card tiers have different country rules.
Asia
China (CN), India (IN), Turkey (TR)
Is Xplace a Scam?
Xplace is not a scam. It is a non-custodial crypto credit card on Solana with a named issuer and operator and published terms.
- Non-custodial: deposits sit in Kamino Finance smart contracts on Solana, not with Xplace.
- Named issuer and operator: the card is issued through Rain (Signify Holdings, Inc.); the platform is operated by Pontech Group L.L.C-FZ (Dubai), with UAE governing law and DIAC arbitration.
- Visa network: standard fraud protection and zero liability on card transactions.
- Published terms and fees: transparent tiers from free to $999/year with documented fees, limits, and cashback rules.
- App Store presence: available on iOS (App Store ID: 6739572706).
What to be aware of
- The credit line and yield run on Kamino. A protocol exploit, insolvency, or sharp collateral drop can liquidate your position automatically, and Xplace cannot prevent or reverse it. Xplace disclosed Drift exposure during the April 2026 exploit before migrating to Kamino.
- Cashback accrues on Credit Mode spending and on-platform trading (Terms 6.4).
- "Up to 16% APY" is a variable ceiling. Live Kamino rates we observed ranged from near zero to about 5.6%.
- XP's value depends on the TGE Xplace has targeted for Q4 2026. The Terms (8.3) still hedge that no token is issued yet, so XP is speculative until the event occurs.
- Support was unresponsive in our December testing.
- Deposit addresses are labeled one-time use with no explanation.
SpendNode Verified: The editorial team reviewed Xplace's issuer identity, operator, product terms, and live card flow per our methodology. Verification is not an endorsement or guarantee.
Sources and Verification
Fees, tiers, and restrictions verified against:
- Xplace Official Site
- Xplace Docs
- Xplace Terms and Conditions (effective May 20, 2026)
- Xplace cashback page (monthly caps; percentage display may lag current membership terms)
- Xplace membership-change email received August 21, 2026 (rates effective September 14)
- In-app membership and category-boost screens captured September 2026
Xplace Crypto Card Volume
Real card activity measured from onchain settlement data. Not self-reported.
Latest closed week
Week ending September 13, 2026
Observed spend
$2.4M
Week over week
-14.7%
Frozen seven-day result using the same measurement boundary as the monthly series. Read the weekly report
- Card spend (Aug 2026)
- $9.7M
- Card transactions
- 86.6K
- Active wallets
- 2.8K
- Month over month
- -16.4%
| Month | Card spend | Card transactions | |
|---|---|---|---|
Sep 2026partial through Sep 13 | $4.8M | 40.9K | |
Aug 2026 | $9.7M | 86.6K | |
Jul 2026 | $11.5M | 68.8K | |
Jun 2026 | $6.2M | 42.4K | |
May 2026 | $5.1M | 33.0K | |
Apr 2026 | $3.4M | 15.3K | |
Mar 2026 | $7.9M | 32.9K | |
Feb 2026 | $6.6M | 16.8K | |
Jan 2026 | $1.9M | 17.8K |
Our read: Xplace settled $9.7M in August, down 16% from July, even as transaction count rose 26% and active wallets rose 21%. More wallets used the card more often, but for smaller purchases; both verified Solana payment signers are included.
How this is measured: USDC card debits on Solana authorized by Xplace's payment signer. Each debit is a card transaction settled from a user's Xplace account, so this measures actual card spend (gross of Xplace's per-transaction fee). The series begins January 2026; earlier Solana data is not yet reliably queryable. Active wallets are distinct Xplace user accounts debited per month.
Chains: Solana - Source: Direct chain data, Dune indexed tables, and public chain explorers; queries by www.spendnode.io - Updated 2026-09-14 - Methodology
Written by Aleksandar Dukic
Frequently Asked Questions
Are Xplace crypto cards available in the United States?
Yes. Xplace crypto cards are available in the United States.
Is the Xplace Card a credit card?
Yes. Xplace is a crypto-backed credit card. You deposit assets into Kamino Finance on Solana and borrow USDC against them through Credit Mode, then spend that credit line via the card. There is no traditional credit check or fixed repayment schedule. A separate Cash Mode lets you spend deposited USDC directly instead of borrowing.
Which network and protocol does Xplace use?
Card spending runs on the Visa network. Collateral, yield, and the credit line are handled on-chain by Kamino Finance on Solana. Xplace can transition to a different protocol in future under its Terms.
Is Xplace custodial?
No. Xplace is non-custodial. Your deposits sit in Kamino Finance smart contracts on Solana, not with Xplace, and the card is issued through Card Partner Rain (Signify Holdings, Inc.). Xplace cannot move or access your collateral, and it cannot prevent or reverse a protocol liquidation if your collateral value falls.
Which assets can I deposit, and what can I borrow against them?
Supported collateral and loan-to-value rates are USDT 80%, cbBTC 70%, wETH 70%, SOL 65%, and jitoSOL 50%. Deposits earn variable Kamino yield (advertised up to 16%, though live rates are typically lower) while backing a USDC credit line you spend through the card.
What is XP, and is there an Xplace token?
XP is a non-monetary loyalty point earned through card usage, deposits, and referrals. Xplace has announced a token generation event (TGE) for Q4 2026, with XP weighting your allocation.
Published allocations earmark 5% to ecosystem partners (Seeker, Superteam, cherry.fun) and 2.5% to NFT communities and DAOs (Claynosaurz, MonkeDAO, Lucid Drakes, Solana Sensei, Dead King Society). The Terms carry the usual pre-launch hedge that no token is issued yet, so value is not locked in until the event lands. KYC is required to use the card, but Xplace does not run a traditional bank-style credit check.
What are the Xplace category boosts?
Paid tiers earn extra cashback at selected merchants, all counted against Credit Mode spend with monthly caps. Rides (Sixt, Uber, Wheely): 3% on Silver, 5% on Gold and Platinum, on up to $500 of monthly spend. AI (ChatGPT, Claude, Cursor): 5% on Gold and 10% on Platinum, on up to $250 of monthly spend. Airlines (British Airways, Cathay Pacific, Emirates, Singapore Airlines, Turkish Airlines, United): 10% on Platinum only, on up to $500 of monthly spend. Basic gets none of the boosts.
What is the difference between Credit Mode and Cash Mode cashback?
Credit Mode (spending borrowed USDC against your Kamino collateral) pays the card cashback: 0.5% Basic, 1% Silver, 1.5% Gold, 2% Platinum for new memberships, subject to monthly cashback limits of $10, $40, $100, and $250 by tier. Cash Mode (spending deposited USDC directly) earns no card cashback for new memberships. Paid memberships purchased before September 14, 2026 can retain their earlier rates for up to 12 months from purchase.
Does Xplace have a welcome bonus?
Yes. Promo code SPENDNODE gives 10% off Silver, Gold, or Platinum membership and is applied automatically through SpendNode's Xplace link. Paid tiers also carry separate welcome packages: up to 25,000 XP plus a $50 cashback bonus on Silver, up to 100,000 XP plus $125 on Gold, and up to 200,000 XP plus $500 on Platinum, subject to their deposit and spend targets.
User Reviews
Reviews are moderated and may take a moment to appear.
Latest Page Changes to the Xplace Review
- xPlace disclosed Drift exposure figures for its savings and credit stack, while card spending remained live during the migration away from the affected protocol
- xPlace app screens label top-up addresses as one-time use; users should generate a fresh address before each transfer