
Solid Card Review 2026
Solid Card is a free Core virtual Visa with 3% USDC cashback, rising to 4% on Prime and 5% on Ultra. It uses a non-custodial Safe wallet and supports Apple Pay and Google Pay.
SpendNode Rating for Solid Card
The Solid Card is a free virtual Visa on a Safe smart account: 3% USDC cashback from day one (up to 5% via points tiers), zero card fees beyond 1% FX, and Borrow Mode so savings keep earning vault yield while you spend. We tested the full onboarding and card issuance from Malaysia in August 2026.
Custody and cost are the strengths; the trade-offs are a virtual-only card with no ATM path, modest cashback caps ($50/month in Core), a young platform, and savings yield that runs below the up-to-6% marketing (4.4% observed).
Also relevant for Stablecoin Spending.
How It Competes
Cost Efficiency
4.4
Product Utility
3.6
Custody & Trust
4.2
Reliability & UX
3.6
Transparency
3.9

CASHBACK
Verified

YIELD LINKED
Verified

SELF CUSTODY SPEND
Verified
Solid Card Overview
Free Non-Custodial Visa - 3% USDC Cashback From Day One, Up to 5% With Prime or Ultra
The Solid Card is a free Core virtual Visa on a non-custodial Safe wallet, paying 3% USDC cashback up to $50/month. Prime pays 4% with a $100 cap for $199/year or a 70,000 FUSE lock, while Ultra pays 5% up to $200 and requires 600,000 FUSE locked. The higher tiers now include live category rewards and yield boosts. Rain or Wirex issues the card by residence, and eligible Wirex cards can spend EURC in euros without FX.
Fees & Charges
Annual Fee
Free
Published FX Fee
1%
SpendNode Tested FX Fee
~1.59%All-in vs mid-market
ATM Fee
Not available
Published FX fee is the card's stated charge. SpendNode Tested FX Fee measures the all-in difference from mid-market, including the network conversion rate and any transaction or conversion charges.
Eligibility & Funding
Supported Regions
NA, EEA, LATAM, APAC, MEA
Spendable Assets
USDC, USDT
The Solid Card is a virtual Visa issued by Rain or Wirex for Solid (solid.xyz), a non-custodial stablecoin savings platform built on Safe smart accounts. Free Core pays 3% USDC cashback, Prime pays 4%, and Ultra pays 5%. Solid markets the card in 105 countries, including the UK and EEA, subject to its legal restrictions and the in-app country check.
Savings stay invested while the card spends
Solid separates savings from the card's spending balance. Stablecoins can remain in a yield vault while a wallet float funds purchases over Visa. An optional Borrow Mode can instead draw against savings as collateral, but its terms must be checked in-app.
Core has no annual card fee and every verified member starts with 3% USDC cashback. Prime costs $199/year or requires 70,000 FUSE locked for 12 months; Ultra requires 600,000 FUSE locked for 12 months. Points no longer unlock the higher tiers.
We tested the full flow from Malaysia in August 2026: passkey signup, KYC in about 2 minutes, and a live virtual Visa the same morning, added to Apple Pay before lunch.
Solid Card specs
Physical and Virtual Cards
The Solid Card is virtual-only. It is created in-app after identity verification, with no order step or shipping wait. There is no physical card and no ATM access, so it does not suit anyone who needs cash withdrawals.
Payment Network
The card runs on Visa and is accepted at 200M+ merchants online and in-store. Its Visa Platinum benefits include 24/7 Visa customer service, purchase protection, price protection, extended warranty, and global auto rental insurance. Visa provides these benefits, not Solid.
Apple Pay and Google Pay provision with one tap on mobile. On the web app (app.solid.xyz), you add the card manually using its details.
Security Features
Freeze and unfreeze work instantly in-app, with real-time payment notifications and a live transaction view showing merchant, category, and the exact cashback earned per purchase. Account access is passkey-based through Turnkey: keys never leave your device's secure hardware, and there is no password or seed phrase to phish. Large transfers can require a second approval factor.
Getting the Card
Sign up through SpendNode's Solid link - our promo code 75LP9 rides in the link and pays you $25 worth of FUSE once the card is activated and you spend $150 across at least 3 different merchants within 30 days. Eligible purchases must qualify for cashback; the reward reaches Solid Savings approximately 30 days after qualification. Create a passkey (no password, no seed phrase), pick a username, and your Safe wallet deploys automatically.
From the Card tab, tap Get your card and run identity verification; Solid quotes about 2 minutes, which matches what we saw. The card activates immediately after KYC and adds to Apple Pay or Google Pay with one tap. Fund with USDC or USDT on any of six networks, or via your Virtual Account's ACH and wire details, and you can spend the same morning.

SpendNode app screenshot
Issuance in one sitting - This is the screen we hit the same morning we started KYC from Malaysia. Verification to live card, no order step, no fee.
How Spending Works: Transaction Flow
Example: an RM212 (about $50) grocery run in Kuala Lumpur
Step 1: Fund. You have previously deposited USDC and moved it to Savings, where it sits as soUSD earning vault yield (4.4% APY at the time of our test).
Step 2: Tap. Apple Pay authorizes against your balance (Savings Mode) or against savings collateral (Borrow Mode). On our Rain-issued Core card, Visa converted the ringgit purchase and the app disclosed a 1% non-USD FX fee. Eligible Wirex cards have a separate EURC route for fee-free euro purchases.
Step 3: Cashback calculates. At the Core tier, 3% of $50 is $1.50 in USDC, assuming you are under the $50 monthly cashback cap. The pending amount is visible in the transaction's details immediately.
Step 4: Cashback lands. About 14 days after the transaction settles, $1.50 USDC credits to your Solid account. If the purchase is refunded, the cashback is removed.
The 14-day lag is the one part of the flow that feels slow against competitors that credit weekly or instantly. It exists because cashback waits for merchant settlement to clear reversals.
The Three Tiers: Core, Prime and Ultra
Everyone starts in Core. Prime and Ultra are optional upgrades purchased annually or activated through a 12-month FUSE lock; points no longer unlock either tier.
| Core | Prime | Ultra | |
|---|---|---|---|
| Access | All members | $199/year or 70,000 FUSE locked | 600,000 FUSE locked |
| General cashback | 3% | 4% | 5% |
| Monthly cap | $50 | $100 | $200 |
| Streaming, music and AI | 3% | 10% | 20% |
| Rides | 3% | 8% | 10% |
| Airlines | 3% | 4% | 10% |
| Savings yield boost | None | +2% APY on up to $10,000 | +3% APY on up to $25,000 |
| Bank deposit / swap | 0.5% / 0.5% | 0.25% / 0.25% | Free / free |
SpendNode app screenshot
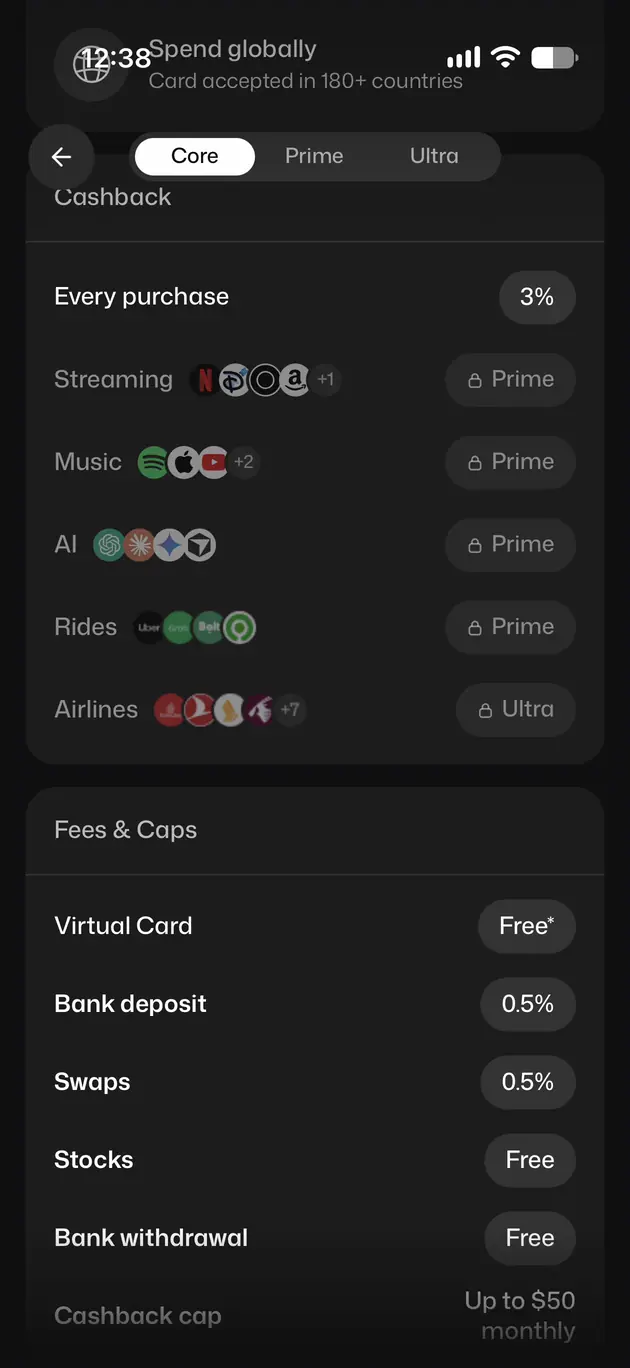
Core - Free virtual card, 3% general cashback and a $50 monthly cap. The app lists 0.5% bank-deposit and swap fees.
SpendNode app screenshot
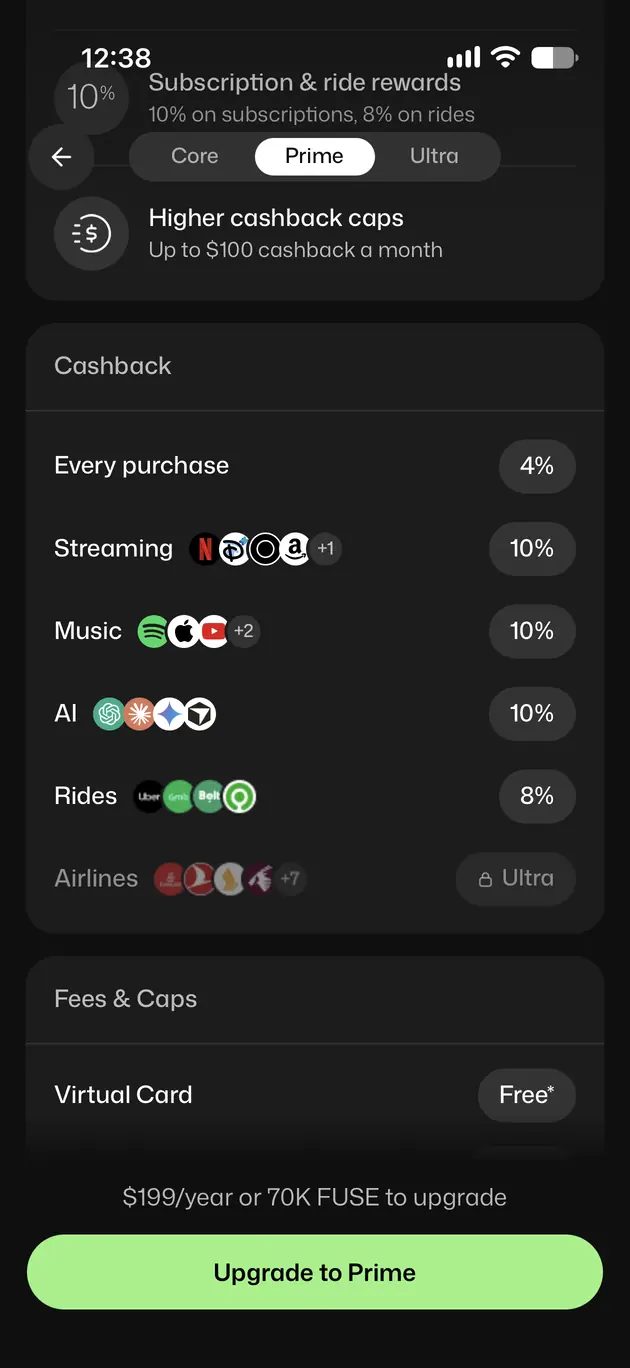
Prime rewards - The higher category rates apply to eligible purchases, not just one subscription charge per month.
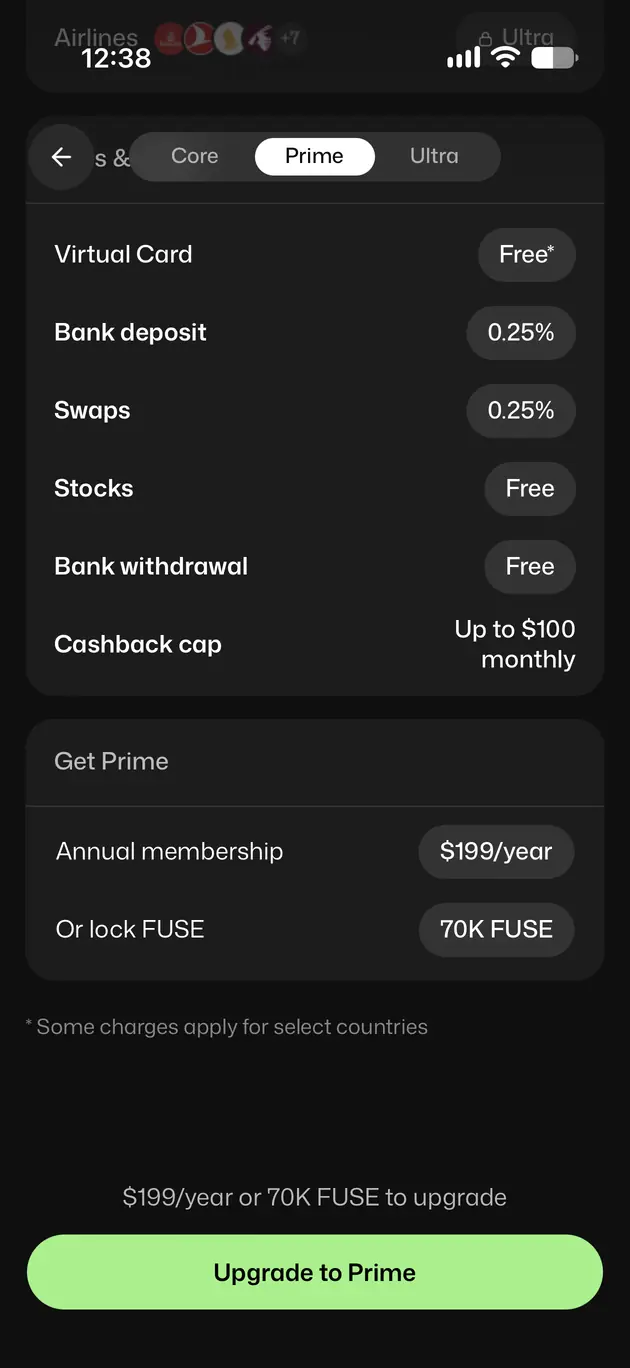
SpendNode app screenshot
Prime access and fees - $199/year or 70,000 FUSE locked, with 0.25% bank-deposit and swap fees.
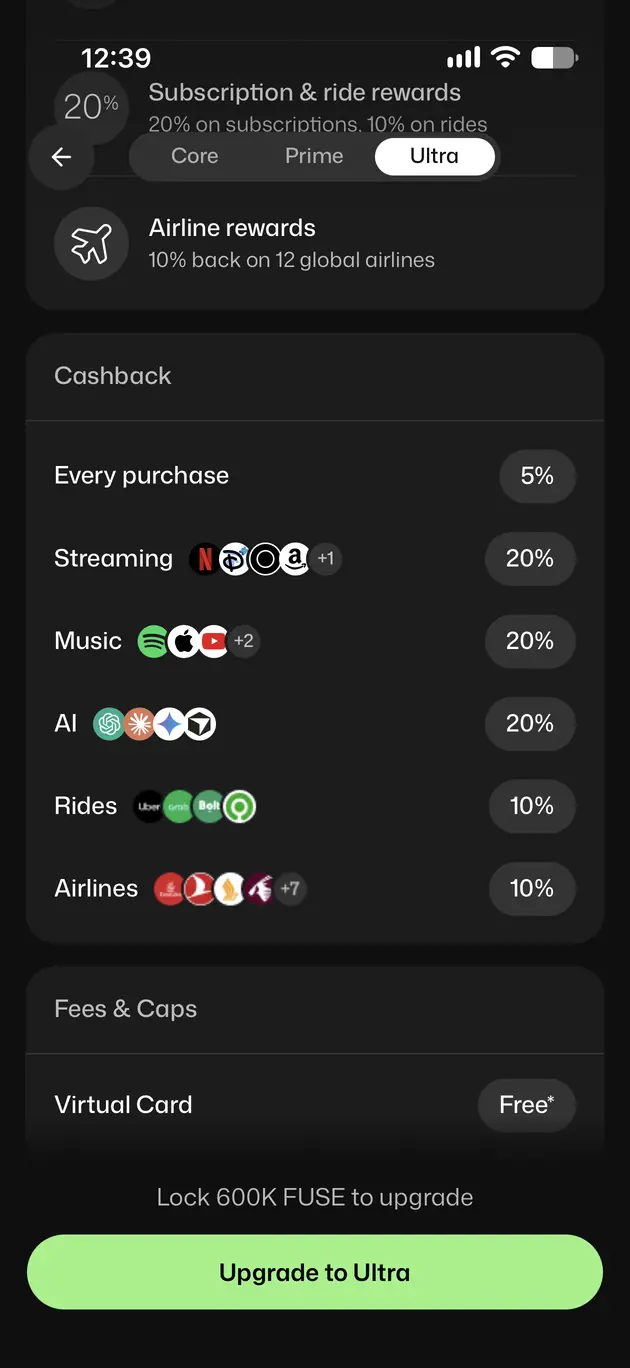
SpendNode app screenshot
Ultra rewards - 5% general cashback and the highest category rates, still subject to the $200 monthly cashback cap.
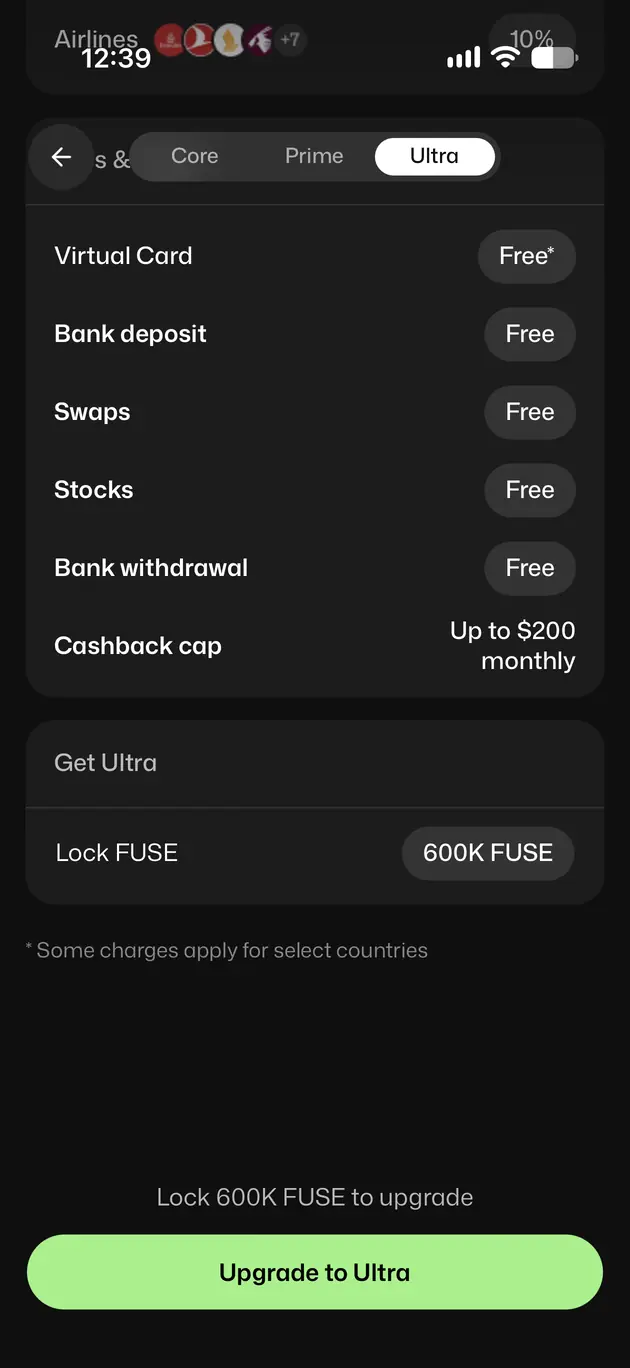
SpendNode app screenshot
Ultra access and fees - 600,000 FUSE locked for 12 months. The app lists bank deposits and swaps as free at this tier.
The lock route introduces token-price and liquidity risk. FUSE remains in the user's address and can earn yield, but the committed amount cannot be treated as liquid spending money during the 12-month term. Prime's paid route avoids that token exposure; Ultra has no annual-payment alternative in the current app.
Borrow Mode: Promising, but Read the Terms In-App
Savings Mode spends your balance directly. Solid describes Borrow Mode as borrowing against savings so the vault position remains invested while transactions authorize against collateral.
The collateral is a dollar-denominated vault position rather than volatile crypto. Solid's public documentation does not publish the borrowing cost, loan-to-value ratio, repayment mechanics, or treatment of unpaid balances.
Check those terms in-app before using Borrow Mode. The scenarios below use a wallet spending float instead.
The conservative way to use the card, and the one our scenarios below assume, is simpler: keep your savings earning in the vault, hold a spending float in your wallet, and spend from balance. The yield on the parked savings continues either way.
Foreign Exchange and Euro Spending
FX treatment now depends on the program partner, tier and transaction currency. Our Rain-issued Core card disclosed 1% FX on non-USD transactions. Eligible Wirex-issued cards can separately enable EURC spending and pay euro purchases one for one from a sufficient EURC balance, with no conversion or FX fee. Solid shows Enable EURC spending on the Card page when that route is available.
Our live Malaysian-ringgit test measured the full result. A RM29.56 purchase settled at $7.36 when the mid-market reference was RM4.08 per dollar. At that reference rate, the purchase would have cost about $7.25, leaving roughly $0.11, or 1.59%, as the all-in difference from mid-market. That result is consistent with Solid's published 1% fee plus the network conversion difference; it does not establish an additional undisclosed Solid fee.
The euro route is specific: the purchase must be charged in euros and the eligible EURC balance must cover it, unless the card's Credit mode is handling the purchase from soUSD. Other currencies can still follow the ordinary card conversion route. Check the fee shown in-app for your assigned issuer rather than assuming every Solid card has the same FX treatment.
For our Malaysian test, Core cashback on $1,000 of comparable ringgit spend would be $30 before the $50 monthly cap, while a 1% published FX charge would cost about $10 plus any network conversion difference. Compare that honestly:
- RedotPay charges no FX markup on its rate but pays far lower base cashback.
- Plasma One Lite also charges 1% FX with 2% cashback on the first $500 - Solid's 3%/$50-cap beats it on net rate for spend between $500 and $1,667.
- A traditional Malaysian bank card charges 1-3% FX with no cashback at all.
The measured 1.59% result remains a useful Rain/Core reference, not a universal rate for every issuer, tier or currency.
Limits and Restrictions
| Item | Value |
|---|---|
| Daily / monthly spend limit | None published - authorized against available balance or collateral |
| ATM withdrawals | Not available (virtual-only card) |
| Cashback exclusions | Refunds, reversals, cash advances |
| Bank deposit / swap fee | Core 0.5%; Prime 0.25%; Ultra free, according to the current tier screen |
| Minimum recommended deposit | $10 (Solid covers gas above this) |
Solid markets card access across 105 countries, including the UK and every EU and EEA member state. Its stricter legal policy still prohibits issuance to residents of Belarus, mainland China, Cuba, India, Iran, Iraq, Israel, Myanmar, Nepal, Nicaragua, North Korea, Russia, Syria, Turkey, Ukraine, Venezuela and Vietnam. Card spending is prohibited while physically in Cuba, Iran, North Korea, Russia, Syria, Ukraine or Venezuela, including the Crimea, Donetsk and Luhansk regions.
The regional help page and legal list conflict on Israel, Turkey, Ukraine and Vietnam. This review applies the stricter legal list. Country support can change; the app's Card section is the final eligibility check.
If Solid shuts down
Funds held in the Safe smart account are not pooled in a custodial exchange balance. That limits the bankruptcy exposure associated with an exchange holding customer assets.
Access is the unresolved issue. Signing depends on passkeys and Turnkey's key infrastructure, and Solid has not published a self-recovery procedure for reaching the Safe without its app. The assets remain on-chain, but recovery after a shutdown is untested.
Savings-allocated funds carry strategy risk. soUSD represents shares in DeFi vaults (BoringVault infrastructure, ERC-4626 with withdrawal queues and automated risk controls, monitored by Check Point). An exploit in an underlying strategy could impair Savings balances specifically. Wallet balance held outside Savings is not exposed to this.
Pending cashback is program risk. With a 14-day settlement lag and monthly caps, your maximum unpaid cashback exposure is small - two weeks of accrual, at most a few hundred dollars for a capped Ultra user, typically under $25 for a Core user.
The card program uses Rain or Wirex. Solid assigns the partner automatically by residence. If either issuer or Solid ended the relevant card program, spending would stop while the self-custodial wallet remained onchain. No deposit insurance applies anywhere in this stack; balances are crypto assets, not bank deposits.
Real User Scenarios
Core user spending $1,200 per month
At 3%, $1,200 of eligible general spend earns $36 before FX and remains below Core's $50 monthly cap. The free tier is the rational default when the extra Prime rewards would not recover its $199 annual cost.
Prime user spending $2,500 per month
General spending at 4% reaches Prime's $100 monthly cap. Against the $199 annual subscription, the maximum general-rate uplift over Core is $600 per year before category rewards and fees. Prime can therefore pay for itself without a FUSE lock, but only for someone who consistently uses the higher cap or the 10% subscription and 8% ride categories.
Eligible euro user
A Wirex-issued cardholder who sees Enable EURC spending can fund EURC and pay a fully covered euro purchase one for one without conversion or FX. That advantage does not automatically extend to non-euro purchases or every Solid card, so the issuer and card-page setting matter.
How the Solid Card Compares
For LatAm, Africa, and Southeast Asia: RedotPay is the custodial incumbent with physical cards and ATM access; Solid beats it on cashback rate and custody model but cannot dispense cash. Rizon competes in the same emerging-market footprint on the paid Emerald tier; Solid's 3% is free.
For self-custody purists: Plasma One offers a similar self-custodial architecture with higher headline rates but pays in volatile XPL. Gnosis Pay is Safe-based and euro-first. Solid now overlaps both in the EEA and UK while retaining broader coverage across Latin America, Africa, Asia and the Caribbean.
For yield-first savers: ether.fi pays banded ETHFI cashback with deeper caps. Solid's Core reward is simpler and paid in USDC, while Prime and Ultra add an annual-payment or FUSE-lock decision.
Where Solid differs: it combines a free virtual Visa, a Safe smart account, USDC cashback, and a dollar-denominated savings vault. Borrow Mode can use that vault as collateral, subject to terms shown in-app.
Who the Solid Card suits
The Solid Card suits people who already hold stablecoin savings and want a self-custodial card in its expanded international footprint. Core is free and pays 3% in USDC from day one. Eligible Wirex users gain a useful EURC route for euro spending; everyone else should price the card using the issuer- and tier-specific fee shown in-app.
Skip it if you need cash: there is no physical card and no ATM path. Skip it too if you spend far beyond the caps, if a $199 annual payment or 12-month FUSE lock does not fit your risk tolerance, or if DeFi strategy risk on savings is a dealbreaker.
Our Verdict on Solid Card
The Solid Card offers a strong free starting rate: 3% USDC cashback with a $50 monthly cap, equivalent to the full headline rate on roughly the first $1,667 of monthly spend. Prime raises the rate and cap for $199/year or a 70,000 FUSE lock, while Ultra requires 600,000 FUSE locked. Their live category rewards can materially improve the result for subscription, AI, ride and airline spending, but the monthly caps still apply.
SpendNode measured about 1.59% all-in FX cost on a Rain-issued Core card against the mid-market rate. Eligible Wirex cards can avoid FX on fully funded euro purchases through EURC, so issuer and currency now matter. The honest starting point remains the free 3% Core tier; upgrade only when the added rewards justify $199 a year or the risk of locking FUSE.
Sources and Verification
All card specs, fees, and limits verified from:
- Solid Official
- Solid Help Center
- Solid Rewards Reimagined
- Solid Euro Cards
- Solid and Wirex Expansion
- Solid Referral Rewards Announcement
- Solid Referral Qualification Rules
- Solid Legal - Privacy Policy, Terms and Conditions
Card mechanics, current tier access, category rewards, fees and caps verified from fresh in-app screens on October 30, 2026. Issuer assignment, euro spending and availability were checked against Solid's help center and legal restrictions. The app remains the final country and fee check.
User scenarios are composite illustrations based on published rates, caps, and fees; individual results vary with spend mix, FX exposure, and the variable savings yield.
Written by Aleksandar Dukic
FAQ
What is the total FX fee for the Solid Card?
The total FX fee for the Solid Card is ~1.59% when tested by SpendNode. This measures the all-in difference against the mid-market exchange rate, including the published FX fee, network conversion rate, and any transaction or conversion charges. Actual results can vary by currency and transaction timing.
Does the Solid Card have a promo code or discount?
Yes. SpendNode's Solid promo code is 75LP9, and it is applied automatically when you sign up through SpendNode's Solid link. A new user earns $25 worth of FUSE after activating the card and spending $150 across at least 3 different merchants within 30 days. The reward is credited to Solid Savings approximately 30 days after qualification.
What does the Solid Card cost?
Core card issuance is free and has no annual card fee. The app currently lists 0.5% bank-deposit and swap fees for Core, 0.25% for Prime, and zero for Ultra. Prime costs $199/year or requires 70,000 FUSE locked for 12 months; Ultra requires 600,000 FUSE locked. FX treatment depends on tier, issuer and currency. Eligible Wirex-issued cards can spend a funded EURC balance in euros without FX.
How does the cashback work?
Eligible purchases earn USDC cashback at your current tier rate: 3% in Core (capped at $50 per calendar month), 4% in Prime ($100 cap), 5% in Ultra ($200 cap). The Core cap binds once you spend about $1,667 in a month. Cashback is credited roughly 14 days after the transaction settles, and each purchase shows its exact cashback in the transaction details.
Can I get the 4% or 5% rate right away?
Yes, but not through points. Prime can be activated for $199/year or by locking 70,000 FUSE for 12 months. Ultra requires 600,000 FUSE locked for 12 months. Everyone starts in the free Core tier at 3%.
Is the Solid Card really non-custodial?
Yes. Your funds sit in a Safe smart account that only you control, secured by passkeys through Turnkey rather than seed phrases. Solid cannot move your assets, and the balance stays in your wallet until a card transaction settles against it. Rain or Wirex issues the Visa card depending on residence.
Can I spend without giving up my savings yield?
Solid describes Borrow Mode as drawing against savings collateral while the soUSD position remains invested. However, its public documentation does not publish the borrowing cost, loan-to-value ratio, repayment terms, or liquidation mechanics. Check the current terms in-app before relying on Borrow Mode; the conservative alternative is to keep savings in the vault and fund card spending from a separate wallet balance.
Is the Solid Card available in my country?
Solid markets the card in 105 countries, including the UK, EU and EEA, Latin America, the Caribbean, Africa, Asia, the Middle East, Oceania and 30+ US states. Its stricter legal issuance policy excludes Belarus, mainland China, Cuba, India, Iran, Iraq, Israel, Myanmar, Nepal, Nicaragua, North Korea, Russia, Syria, Turkey, Ukraine, Venezuela and Vietnam. Availability can change, so check the Card section in the app before relying on the list.
This is a debit card. Some merchants with pre-authorization holds (hotels, car rentals) may temporarily hold funds beyond the transaction amount.
You retain custody of your funds until the moment of spending. Your balance is not exposed to provider insolvency risk.
Fees shown above are the card's disclosed fees. Additional costs may apply: Visa/Mastercard network spread (typically 0.5-0.9%), crypto-to-fiat conversion spread at point of sale, and blockchain gas fees for on-chain top-ups.
Found any issues?
User Reviews
Reviews are moderated and may take a moment to appear.