
COCA Visa Card Review 2026
Non-custodial Visa card with 1-8% uncapped cashback by tier, monthly claim capacities of $15-$350, 0% FX, 5% APY on USD balances, 50% subscription rebates by category, personal IBAN, and Apple Pay. Issued by Wirex.
SpendNode Rating for COCA Visa Card
COCA scores well on usability for travel spending, which often matters more than headline rewards rates.
Starter tier needs no staking and has no annual fee plus 0% FX, which is the travel case. Higher tiers require $COCA staking, and rewards are metered by monthly claim capacities of $15 to $350, which trims the extractable value at every paid tier even though earning is uncapped. The tier mechanics and capacities are openly published, which supports the transparency score.
Also relevant for Rewards / Cashback.
How It Competes
Cost Efficiency
3.9
Product Utility
4.1
Custody & Trust
3.6
Reliability & UX
3.9
Transparency
4.0

CASHBACK
Verified

YIELD LINKED
Verified

SELF CUSTODY SPEND
Verified
COCA Visa Card Overview
Self-Banking: 8% Cashback + 5% APY + 0% FX
The COCA Visa Card packs 8% cashback, 0% FX, 5% APY, and 50% subscription rebates into a single non-custodial wallet. Earning is uncapped, but withdrawing rewards is metered by a Monthly Claim Capacity of $15 to $350 depending on tier, so heavy spenders should size their tier around what they can actually extract. Six tiers from Starter (free) to Elite (stake 30K COCA) with 30-day cooldown to unstake. Card issued by Wirex with personal IBAN and broad country coverage.
Fees & Charges
Annual Fee
Free
FX Fee
0%
ATM Fee
0%
Requirements
Supported Regions
EEA, UK, APAC, LATAM, GLOBAL
Spendable Assets
USDC, USDT, ETH, BTC
On This Page
What Is the COCA Visa Card?
The COCA Visa Card is a non-custodial Visa debit card issued by Wirex, offering 1-8% cashback across six staking tiers (Starter through Elite) with no cap on earning, 0% FX fees, and 5% APY on USD balances via Morpho lending markets with Gauntlet risk management. Each tier carries a Monthly Claim Capacity of $15 to $350 that limits how much reward value can be withdrawn per month.
On top of that sit the 50% subscription rebates - one service per category, up to four categories by tier, worth at most $35 back each - alongside a personal IBAN with SEPA bank transfers, $200/month free ATM withdrawals worldwide, a smart contract wallet powered by Privy (ERC-4337/EIP-7702) with biometric recovery, and 76-country availability with 1M+ users.
The card bundles cashback, stablecoin yield, subscription rebates, up to 50% hotel discounts, and a personal IBAN into a single non-custodial product. No other single card combines all of these.
COCA charges 0% FX on all currencies - your cashback rate is your net return regardless of where you spend. At Elite tier, 8% cashback means 8% net on every eligible purchase. At Starter tier (no tokens needed), 1% cashback plus 5% APY on the USD balance makes the free tier a workable baseline. Reward claims are metered at $15 to $350 per month by tier, so the withdrawal capacity matters as much as the earning rate.
The catch is the $COCA token. Six staking tiers from Starter (free) to Elite (stake 30,000 COCA) determine your cashback rate, monthly claim capacity, and subscription access. The token is small-cap, traded on MEXC, BitMart, and DEXes. At Starter you carry zero token risk. At Elite you're exposed to a micro-cap asset that could lose significant value in a downturn.
Staked tokens are locked for the duration of your tier membership. To unstake, you cancel your tier (downgrades to Starter) and wait 30 days before claiming tokens. No partial unstaking is allowed.
Card Specs
Physical and Virtual Cards
- Virtual card: Free for all tiers, instant issuance
- Physical card: $5 for Starter/Standard/Standard+; free for Premium/Premium+/Elite
- Design: COCA-branded Visa debit card
- Mobile wallets: Apple Pay, Google Pay
Payment Network and Security
- Network: Visa (issued by Wirex)
- Acceptance: 150M+ merchant locations worldwide
- Contactless: NFC tap-to-pay
- 3D Secure: Supported for online transactions
- PCI DSS and ISO compliant
- Freeze/unfreeze: Instant via COCA app
- Authorization model: Each transaction approves only the specific amount for that specific merchant - COCA cannot access your full balance
- Visa zero liability: Standard fraud protection for unauthorized transactions
Wallet Architecture
- Non-custodial smart wallet powered by Privy (ERC-4337/EIP-7702)
- You control the keys - COCA cannot move, freeze, or access your funds
- Biometric recovery: Recover wallet via face/fingerprint if you lose your device (no seed phrase needed)
- Private key export: Available (irreversible - you lose COCA wallet access after export)
- Privy security: SOC 2 Type I and II certified, audited by Cure53, Zellic, and Doyensec, bug bounty program
Banking Features
- Personal IBAN: SEPA bank transfers in EUR
- Salary deposit: Share your COCA IBAN with your employer
- Top-up options: Bank transfer (IBAN/SEPA), debit/credit card, stablecoins on multiple blockchains
- Fiat-to-stablecoin: Coming soon
- Crypto-backed loans: Coming soon
How Spending Works: Transaction Flow
Example: EUR 85 dinner in Barcelona (Standard+ tier, EUR base currency)
Step 1: Fund your Banking Account
- Options: SEPA bank transfer (via your personal IBAN), debit/credit card top-up, or stablecoin deposit
- Stablecoins in your smart wallet convert automatically at the time of purchase
- COCA says deposit addresses changed with the COCA 3.0 upgrade. Before sending crypto, copy the current address from Add Money > Crypto Deposit in the COCA app; funds sent to an old address may not arrive.
Step 2: Pay
- Tap your COCA Visa or Apple Pay
- Restaurant charges EUR 85
Step 3: Fees
- FX fee: 0% (all currencies)
- Total fees: EUR 0
Step 4: Cashback (Standard+ tier, 4%)
- 4% of EUR 85 = EUR 3.40 cashback, credited in stablecoins after a 14-day pending period
- Net: +EUR 3.40 (4.0% net)
- Earning is uncapped; withdrawing it counts against Standard+'s $35/month claim capacity
Same transaction at other tiers:
| Tier | Cashback | FX Fee | Net Return |
|---|---|---|---|
| Starter (1%) | EUR 0.85 | 0% | +1.0% |
| Standard (3%) | EUR 2.55 | 0% | +3.0% |
| Standard+ (4%) | EUR 3.40 | 0% | +4.0% |
| Premium (5%) | EUR 4.25 | 0% | +5.0% |
| Premium+ (6%) | EUR 5.10 | 0% | +6.0% |
| Elite (8%) | EUR 6.80 | 0% | +8.0% |
With 0% FX on all currencies, your cashback rate equals your net return regardless of spending currency. Every eligible purchase earns the full tier rate; what is limited is how fast you can withdraw the rewards, via each tier's monthly claim capacity ($15-$350).
Fees and Rates
| Limit | Amount |
|---|---|
| Per transaction | 30,000 EUR |
| Daily spending | 30,000 EUR |
| Monthly spending | 30,000 EUR |
| Quarterly spending | 75,000 EUR |
| Semi-annual spending | 100,000 EUR |
| ATM free monthly | $200 |
| ATM daily max | 850 EUR (5 transactions) |
| ATM monthly max | 5,000 EUR |
| ATM fee above free | 2% |
| Annual fee | $0 |
| FX fee | 0% on all currencies |
| Supported assets | USDC, USDT, ETH, BTC |
Rewards on This Tier
The tier's rate applies to every eligible purchase with no earning cap. The lever that actually sizes your rewards is the Monthly Claim Capacity: the maximum reward value you can withdraw per calendar month, shared across cashback, subscription rebates, referrals, and campaigns. Rewards pend 14 days, pay out in stablecoins (USDC/EURC) to your USD or EUR account, carry over if unclaimed, and expire 12 months after becoming claimable.
Standard Tier - 3% cashback on all eligible spend, claims up to $25/month, 1 Video Streaming rebate. Stake 300 $COCA to unlock.
| Tier | $COCA Staked | Cashback | Monthly Claim Capacity | Plastic Card | Subscription Categories |
|---|---|---|---|---|---|
| Starter | 0 | 1% | $15/mo | $5 | None |
| Standard | 300 | 3% | $25/mo | $5 | 1: Video Streaming |
| Standard+ | 1,000 | 4% | $35/mo | $5 | 2: Video, AI |
| Premium | 3,000 | 5% | $60/mo | Free | 2: Video, AI + card issue rebate |
| Premium+ | 10,000 | 6% | $140/mo | Free | 3: Video, AI, Music + card issue rebate |
| Elite | 30,000 | 8% | $350/mo | Free | 4: Video, AI, Music, Marketplaces + card issue rebate |
All tiers share: $0 annual fee, free virtual card, 0% FX fees, 0% trading fees, free cross-chain swaps, 5% APY on USD balances. Claim capacity grows $1/month per extra 100 $COCA staked; claims run one per 24 hours, $1 minimum, oldest first. Each subscription category covers one service per month at 50% rebate, on subscriptions priced up to $70 (max $35 back per category). Video Streaming includes Netflix, Disney+, Paramount+, YouTube Premium.
How tier staking works:
- Stake $COCA tokens in the COCA app to upgrade your tier
- Staked tokens are locked for the duration of your tier membership
- To unstake: cancel your tier (downgrades to Starter), then wait 30-day cooldown, then claim tokens
- No partial unstaking - cancelling returns all staked COCA and resets to Starter
- Staking COCA does not earn APY - staking is solely for tier access
- Tier upgrades during cooldown period are not available
Annual Claimable Value at Different Spending Levels (0% FX, Steady State)
Cashback accrues at the full tier rate on all spend; this table shows what can be withdrawn per year once the monthly claim capacity ($15/$25/$35/$60/$140/$350 by tier) binds. Figures assume steady monthly spend, base staking, and no subscription, referral, or campaign rewards drawing from the same capacity.
| Monthly Spend | Starter (1%, $15 cap) | Standard (3%, $25 cap) | Standard+ (4%, $35 cap) | Premium (5%, $60 cap) | Premium+ (6%, $140 cap) | Elite (8%, $350 cap) |
|---|---|---|---|---|---|---|
| $500 | $60/yr | $180/yr | $240/yr | $300/yr | $360/yr | $480/yr |
| $1,000 | $120/yr | $300/yr (capped) | $420/yr (capped) | $600/yr | $720/yr | $960/yr |
| $2,500 | $180/yr (capped) | $300/yr (capped) | $420/yr (capped) | $720/yr (capped) | $1,680/yr (capped) | $2,400/yr |
| $5,000 | $180/yr (capped) | $300/yr (capped) | $420/yr (capped) | $720/yr (capped) | $1,680/yr (capped) | $4,200/yr (capped) |
Where a cell says "capped", spending accrues rewards faster than capacity lets you claim them; the excess queues (12-month expiry) or calls for staking extra $COCA ($1 capacity per 100 tokens) or upgrading tiers.
Subscription Rebate Value (50%, by Category and Tier)
One subscription per category per month at 50% rebate; only subscriptions priced $70 or less qualify, so the ceiling is $35 back per category. The first eligible payment in each category per month receives the rebate, and rebates draw from the same monthly claim capacity as cashback.
| Category | Eligible Services | Available From | Example Monthly Savings |
|---|---|---|---|
| Video Streaming | Netflix, Disney+, Paramount+, YouTube Premium | Standard | $7.75 (Netflix) |
| AI Assistants | ChatGPT, Cursor, others | Standard+ | $10.00 (ChatGPT) |
| Music | Spotify, Apple Music, others | Premium+ | $6.00 (Spotify) |
| Marketplaces | Amazon Prime, others | Elite | $7.50 (Amazon) |
Annual savings by tier (example services):
- Standard: approx. $93/yr (1 Video sub)
- Standard+: approx. $213/yr (1 Video + 1 AI sub)
- Premium: approx. $213/yr (same categories as Standard+, plus card issue rebate)
- Premium+: approx. $285/yr (+ Music sub)
- Elite: approx. $375/yr (+ Marketplaces sub)
USD Balance APY: 5% via Morpho + Gauntlet
COCA pays a variable 5% APY on USD banking balances, generated from borrowing demand on Morpho lending markets and risk-managed by Gauntlet. It is not a COCA-funded promotional rate.
How it works:
- Accrues in real time on the spendable balance; no staking or lock-up, funds stay liquid
- Claimed manually once accrued earnings reach $1; the APY claim sits outside the monthly claim capacity
- Morpho's audited codebase (OpenZeppelin, Spearbit) handles lending
- Gauntlet provides curated allocations, market caps, and ongoing monitoring
- EUR balances earn no APY
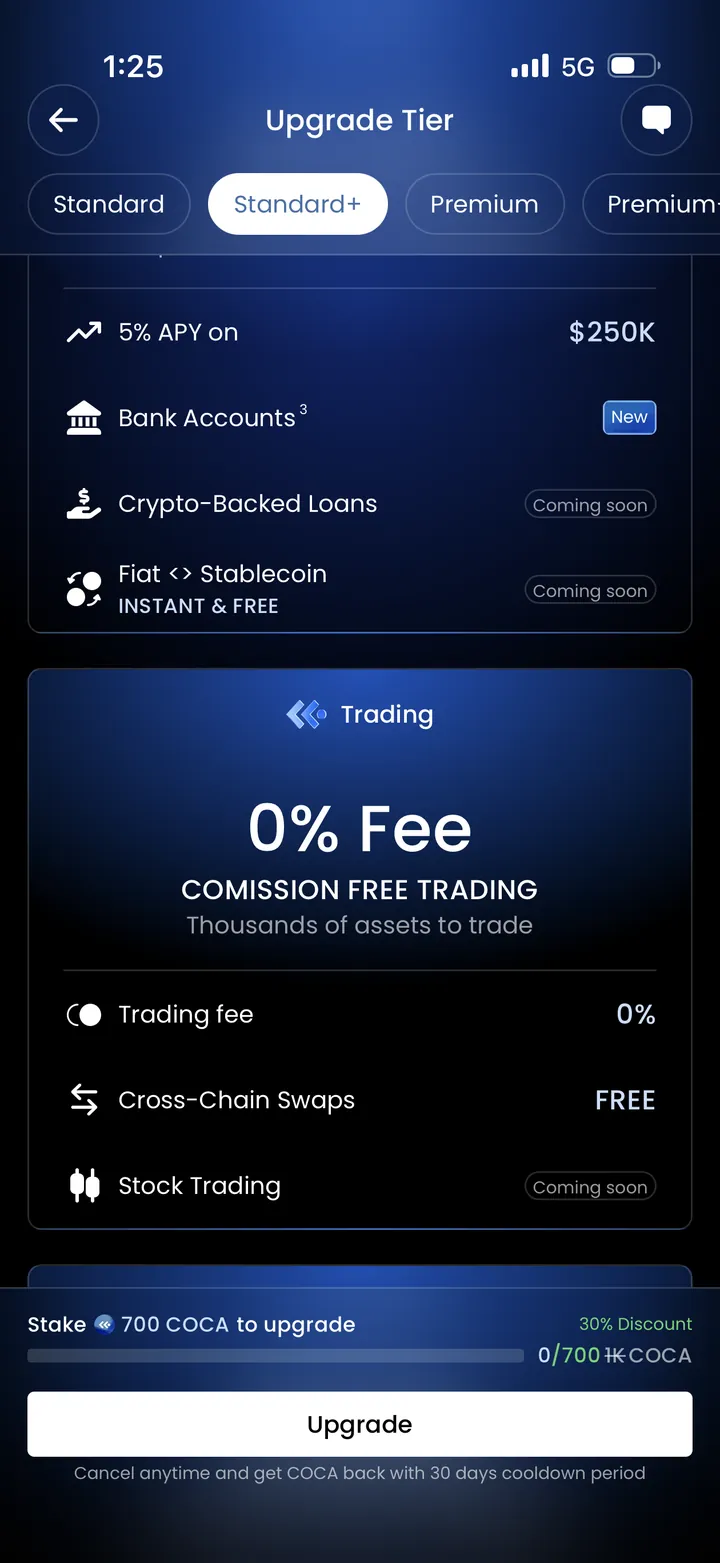
The terms table lists the 5% as unlimited, but the app is more specific and we treat the app as controlling: our September 2026 tier screens show "5% APY on $50K" at Standard and "$250K" at Standard+, with 2% applying above the cap per the terms, and Starter's home screen displays the rate as a 3% base plus a 2% boost. Illustratively at 5%: $5,000 earns ~$250/year and $25,000 earns ~$1,250 within your tier's cap. Check the app for the live figure before parking large sums.
SpendNode app screenshot
Standard+ banking screen (September 2026) - the app states the APY cap per tier: 5% on up to $250,000 at Standard+ ($50,000 at Standard).
The $COCA Token: Risk Analysis
$COCA is a small-cap token. This is the single most important factor for anyone considering tiers above Starter.
Where to buy: MEXC, BitMart, Uniswap, 1inch (via WalletConnect in COCA app).
The risk calculation at each tier:
| Tier | $COCA Needed | If Token Drops 50% | If Token Drops 80% | Annual Claimable ($3K/mo spend) |
|---|---|---|---|---|
| Starter | $0 | $0 loss | $0 loss | $180 (capacity-capped) + APY |
| Standard | 300 tokens | Depends on entry price | Depends on entry price | $300 (capacity-capped) + APY |
| Elite | 30,000 tokens (~$47,000) | Significant loss | Severe loss | $2,880 + subs (within $350/mo capacity) + APY |
Break-even logic: Your annual claimable rewards from cashback + APY + subscriptions must exceed any $COCA token depreciation for the tier to be worth it. At Starter, there's zero token risk. At Elite, the claimable rewards are substantial (up to $4,200/year from the loyalty pool) but you're holding a roughly $47,000 position in a micro-cap asset - a 10% token move swings more value than a whole year of rewards.
Mitigations:
- 30-day cooldown to unstake: cancel tier, wait 30 days, claim tokens (benefits continue during cooldown)
- Starter tier: fully functional card with 1% cashback, 0% FX on all currencies, 5% APY on the USD balance, and zero token exposure
- Private key export: move $COCA to external wallet if concerned about platform risk (but tokens must be in COCA wallet and staked for tier benefits)
How This Tier Compares
For high-cashback seekers:
- Crypto.com: Up to 8% CRO with a 12-month staking lockup at the top tiers. COCA's 8% needs only a 30-day unstake cooldown, though its $350 monthly claim capacity meters the payout. Crypto.com wins on track record, airport lounges, and 100% subscription rebates. COCA wins on 0% FX and balance APY
- Plutus: 3-9% PLU with subscription (GBP 6.99-19.99/month, no free tier). 2.5% FX on non-domestic. EEA/UK only. COCA wins on FX (0% vs 2.5%), broader availability, IBAN, no subscription fee, and APY. Plutus wins on max cashback rate (9%) for domestic perk optimizers
- KAST: 1.5% USD cashback on first $2K/mo at the free Standard tier with 0.5-1.75% FX. Premium and Luxe tiers raise the cap and add KAST Points but require paid card costs. KAST wins on zero token requirement and widest availability. COCA wins on max cashback rate (8% vs 1.5-3%), 0% FX, APY, and subscription rebates, with the claim-capacity throttle as the trade
For lighter onboarding:
- COCA uses a reduced-verification flow, while MetaMask uses streamlined ID checks. RedotPay and KAST require full KYC but typically complete it in about two minutes. COCA combines lighter onboarding with up to 8% cashback, 0% FX, and APY.
For APY seekers:
- COCA's 5% via Morpho is a competitive card-linked stablecoin yield in a Privy-managed non-custodial wallet. Nexo offers up to 14% APY (tier-dependent, custodial with KYC). Bybit offers yield on USDT but is custodial
For international spenders:
- COCA's 0% FX on all currencies means cashback rate = net return on all spending. Gnosis Pay also charges 0% FX but caps at 4% cashback. Crypto.com charges 0-2% FX depending on plan
Real User Scenarios
Scenario 1: Viktor (Tallinn Developer, EUR 3,500/month, Premium tier)
Setup:
- COCA Visa (EEA, Premium tier - stakes 3,000 COCA)
- 25,000 USDC earning 5% APY on the USD balance
- 80% EUR domestic, 20% international travel
- Uses ChatGPT Plus and Netflix (50% rebate at Premium - 2 categories: AI + Video)
- 0% FX on all currencies
- Premium monthly claim capacity: $60
Results after 12 months:
- Cashback accrued (EUR 42,000/yr at 5%, 0% FX): EUR 2,100 earned, plus roughly EUR 215 of subscription rebates
- Claimable through Premium's $60/mo capacity: approx. EUR 660 actually withdrawn
- Queue at year end: EUR 1,650+ of rewards waiting behind the cap, oldest facing the 12-month expiry
- APY on 25,000 USDC (5%): EUR 1,150
- Total annual value extracted: approx. EUR 1,810
His verdict: "The 5% rate is real on every purchase, but at EUR 3,500 a month I out-earn my $60 claim capacity almost 3-to-1. The queue just grows, and the oldest rewards will start expiring. Either I stake thousands more COCA for capacity, or I accept that Premium's honest yield on my spending is about 1.6%, not 5. The APY and the salary IBAN are the parts that work exactly as advertised."
Scenario 2: Priya (London Content Creator, GBP 2,200/month, Starter tier)
Setup:
- COCA Visa (UK, Starter tier - zero staking)
- 5,000 USDC earning 5% APY on the USD balance
- 60% GBP domestic, 40% international (travel content)
- No subscription rebates at Starter
- 0% FX on all currencies; Starter claim capacity $15/mo
Results after 12 months:
- Cashback accrued (GBP 26,400 at 1%, 0% FX): GBP 264 earned
- Claimable through Starter's $15/mo capacity: approx. GBP 142 withdrawn, the rest queued
- APY on 5,000 USDC (5%): GBP 198
- Total annual value extracted: approx. GBP 340
Her verdict: "At Starter with zero staking, 1% with 0% FX is still fine for a free card, but the $15 monthly claim cap means I cannot even withdraw all of my 1%. Standard (stake 300 COCA) would triple my rate and lift the cap to $25 - which is the real number to compare, since at my spending both tiers are capacity-bound. Staking means locking tokens with a 30-day cooldown to exit."
Scenario 3: Rafael (Mexico City Founder, $5,000/month, Elite tier)
Setup:
- COCA Visa (LATAM, Elite tier - stakes 30,000 COCA, locked during membership)
- 50,000 USDT earning 5% APY on the USD balance
- 55% MXN domestic, 45% USD international, all at 0% FX
- Elite monthly claim capacity: $350 (his 8% on $5,000/mo accrues $400)
- All 4 subscription categories at 50% rebate (Video + AI + Music + Marketplaces)
- Uses COCA Travel for hotel bookings
Results after 12 months:
- Cashback accrued ($60,000/yr at 8%, 0% FX): $4,800 earned, plus ~$375 of subscription rebates
- Claimable through Elite's $350/mo capacity: $4,200 withdrawn; roughly $975 queued at year end
- APY on 50,000 USDT (5%): $2,500
- COCA Travel savings: approx. $600
- Total annual value extracted: approx. $7,300
His verdict: "At $5,000 a month I slightly out-earn Elite's $350 claim cap once the subscription rebates stack on top, so a queue builds - manageable, since a lighter month lets me catch up before anything expires. Staking a few thousand extra COCA would close the gap entirely. The bigger question stays the same: 30,000 locked tokens, roughly $47,000 of micro-cap exposure, to run this card at full power. The $7,000+ a year is real, but so is the position."
Is the COCA Visa Card Safe?
Your wallet funds: Non-custodial via Privy smart contracts. COCA cannot access or move your funds. However, Privy key reconstruction depends on Privy's infrastructure. You can proactively export your private keys (irreversible - loses COCA wallet access) as insurance. This is stronger than custodial exchange cards but weaker than pure seed-phrase self-custody (Gnosis Pay, Ledger CL).
Your $COCA tokens: Would likely lose most value (utility tied to the platform). Sell pressure would be immediate.
Your card: Stops working (Wirex card program depends on COCA). Pending cashback and subscription rebates lost.
Your IBAN/banking: SEPA functionality depends on COCA's banking partner arrangements.
Mitigation: Withdraw earned rewards regularly. Keep minimum $COCA for your target tier. Export private keys if concerned. Don't store more than your active spending + yield balance in the COCA wallet.
Who Should Choose This Tier
- Starter (zero staking): If you want a fully functional crypto card with 1% cashback, 0% FX on all currencies, and 5% APY on the USD balance, with zero token risk. The $15/month claim cap covers up to $1,500 of monthly spend at 1%.
- Standard (stake 300 COCA): If you spend up to about $833/month - that is where 3% fills the $25 claim capacity. Low token risk, meaningful uplift over Starter.
- Standard+ to Premium (1,000-3,000 COCA): If you want the AI Assistants rebate and capacity of $35-$60/month, which 4-5% fills at roughly $875-$1,200 of monthly spend. Medium token exposure.
- Premium+ to Elite (10,000-30,000 COCA): If you spend $2,300-$4,400/month and want the 6-8% rate with capacity ($140-$350) to actually claim it, plus three or four subscription categories. High token risk that only makes sense for users who have already done the math on $COCA downside scenarios.
- Any tier: If you want a non-custodial crypto card with IBAN banking, DeFi yield, and a real Wirex card issuer behind it. The right tier is the one whose claim capacity comfortably covers your monthly spend.
Our view: No single competitor bundles this many reward streams into one card, though the claim-capacity system and staking requirements add planning overhead that simpler cards do not have. The rates are real and earning is uncapped, but the capacity decides what reaches your account: $180 a year at Starter up to $4,200 at Elite, with everything beyond that queuing toward a 12-month expiry. At Starter with zero staking, 1% cashback, 0% FX, and 5% APY is still a solid free baseline.
The Privy wallet security is audited and certified. The Morpho yield reflects actual lending demand, not a subsidized rate. The Wirex card issuance has an 11-year track record. But staked COCA tokens are locked during membership with a 30-day cooldown to unstake, and $COCA the token carries meaningful risk at higher tiers.
Start at Starter for 1% cashback, 0% FX, and 5% APY with zero staking and zero risk. Move up only when your monthly spend consistently out-earns your current tier's claim capacity, and be aware that staking locks your tokens until you cancel your tier and wait the 30-day cooldown.
Sources and Verification
All card specs, fees, tiers, and limits verified from:
- COCA Official Site
- COCA Docs
- COCA Loyalty Program Terms & Conditions (September 2026)
- First-party app screenshots (February 2026)
Written by Aleksandar Dukic
FAQ
Does the COCA Visa Card have a promo code or discount?
Yes. The COCA Card promo code is T8kJtJtodTb. Sign up through SpendNode's COCA link on our promo codes page, order a COCA Card, and spend $100 across three merchants within 30 days to receive a $10 welcome bonus. The code is applied automatically through the link.
This is a debit card. Some merchants with pre-authorization holds (hotels, car rentals) may temporarily hold funds beyond the transaction amount.
You retain custody of your funds until the moment of spending. Your balance is not exposed to provider insolvency risk.
Fees shown above are the card's disclosed fees. Additional costs may apply: Visa/Mastercard network spread (typically 0.5-0.9%), crypto-to-fiat conversion spread at point of sale, and blockchain gas fees for on-chain top-ups.
Found any issues?
User Reviews
Reviews are moderated and may take a moment to appear.
Latest Page Changes to the COCA Visa Card Review
- Added COCA's 3.0 deposit-address reminder warning users to copy a fresh crypto deposit address before sending funds