
Best Crypto Cards in Russia (2026)
Russia is not a domestic crypto-card market anymore. This guide covers the limited offshore options that still matter for Russian nationals abroad, where sanctions, KYC friction, and destination-country tax rules shape the real card choice more than nominal rewards do.
Diaspora use only
No crypto card works for domestic purchases inside Russia: Visa and Mastercard suspended operations in March 2022. The cards below are for Russian nationals living abroad, applied for with a non-Russian address and destination-country residence.
Verified for Russia
12 crypto cards shown
Local currency: RUB
If you bank with Sberbank, Tinkoff, Alfa-Bank, or any Russian financial institution, the fundamental reality is this: Visa and Mastercard suspended all operations in Russia in March 2022. Every crypto card we track runs on Visa or Mastercard rails. This means no crypto card will work for domestic purchases inside Russia - not at Pyaterochka, not on Wildberries, not at any Russian merchant terminal.
This page exists to document exactly what that means, what limited options exist for Russian nationals living abroad, and how the regulatory framework shapes crypto ownership and spending in one of the world's most active crypto markets.
Russia ranks consistently in the top 5 globally for cryptocurrency adoption. Chainalysis placed Russia second worldwide in its 2023 Global Crypto Adoption Index. An estimated 17-20 million Russians hold cryptocurrency, representing roughly 12-14% of the population. The paradox is sharp: massive adoption, zero ability to spend via card domestically. The crypto card opportunity for Russia is therefore almost entirely a diaspora story.
The Two Relocation Waves
The first wave came in late February 2022, immediately after the invasion of Ukraine. IT workers, entrepreneurs, journalists, and opposition-aligned professionals left primarily for Georgia (Tbilisi became a de facto Russian tech hub), Turkey (Istanbul, Antalya), Armenia (Yerevan), and UAE (Dubai).
Many left within days, carrying laptops and cryptocurrency but little else. Traditional banking in destination countries required weeks or months to establish, making crypto-funded spending cards an immediate lifeline.
The second wave followed the partial military mobilization announced on September 21, 2022. An estimated 300,000-700,000 men of military age left Russia within weeks, primarily to Kazakhstan (visa-free for Russians), Georgia, Mongolia, and Finland (before Finland closed its border).
This wave was younger, less financially prepared, and more likely to rely on P2P crypto markets and USDT as a portable store of value.
Combined, an estimated 500,000-1,000,000 Russians now live abroad with varying degrees of permanence. Many hold dual financial lives: ruble-denominated income from remote Russian employers or freelance clients, and local-currency spending needs in their destination countries. A crypto card funded with stablecoins bridges this gap without requiring a full local banking relationship.
The USDT Shadow Economy
Tether (USDT) has become Russia's parallel dollar system. After Visa/Mastercard suspension and SWIFT disconnection cut most Russians off from the global dollar economy, USDT filled the void. Russian-language P2P USDT volume on Telegram alone is estimated at billions of dollars monthly.
USDT is used for cross-border freelance payments (Russian developers billing foreign clients), remittances (sending money to family members abroad or receiving money from abroad), savings (preserving purchasing power against ruble depreciation - the ruble fell from 75/USD to over 100/USD between 2022 and 2025), and import/export settlement (small and medium businesses using USDT to pay Chinese and Turkish suppliers when bank transfers fail or take weeks).
Rent and large purchases in some relocation destinations (landlords in Tbilisi, Yerevan, and Istanbul sometimes accept USDT directly) further expand the use case.
This means many potential Russian crypto card users are not converting from rubles to crypto for the first time. They already hold USDT. The crypto card is the last mile: converting their existing USDT holdings into Visa/Mastercard spending power. This is why KAST (USDT/USDC support) is the most relevant card for this population.
Summary:
Which crypto cards are best in Russia?
The best crypto cards in Russia in October 2026 are Tria Signature Card, ether.fi Core Card, and KAST K Card. The detailed ranking below explains the local tax, fee, and availability trade-offs.
| Crypto card | Base reward | Net after fees | Annual fee | FX fee | Type |
|---|---|---|---|---|---|
| 4.5% base4.5% on the first $1,000/mo, then 1% | 3% | $109/year | 1% | Debit | |
| 3% base3% on the first $2,000/month, then 1% and 0.5% | 2.5% | Free | 0.5% | Crypto Backed Credit | |
| 1.5% base | 1% | Free | 0.5% | Prepaid |
Critical caveat: every card above requires a non-Russian address for KYC verification. Russian passport alone is insufficient for most issuers. Russian nationals living in UAE, Turkey, Georgia, Armenia, Kazakhstan, or other countries with local residency permits can typically complete verification using their foreign address documentation.
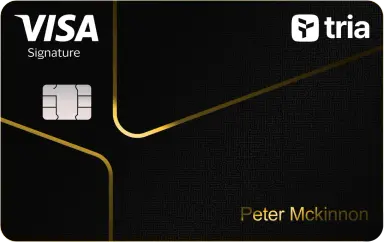
KAST offers quick onboarding for eligible diaspora applicants with foreign residence documents. Tria Signature pays 4.5% on the first $1,000/month (then 1%) in USDT, with 1% FX and 0.5% per payment.
At that mix of fees, its $109 annual fee breaks even around $303/month of eligible spending. Neither card will work for domestic purchases inside Russia.
Best Card For Every Need in Russia
Top 3 Crypto Cards in Russia
Russia's Visa and Mastercard suspension in March 2022 means every card recommendation here is a diaspora infrastructure decision - cards that work for 500,000-1,000,000 relocated Russians who already hold USDT and need the last mile to Visa/Mastercard spending power.
Tria Signature at 4.5% on the first $1,000/month (then 1%), 1% FX plus 0.5% per payment (about 3% net), is the strongest no-stake, self-custody pick for diaspora members in Turkey, Georgia, or UAE who have settled into stable spending patterns - the $109/year fee breaks even at about $303/month.
ether.fi Core matters most for the Georgia and Armenia diaspora, where destination-country tax varies. It pays stepped ETHFI rewards, accepts supported stablecoins for direct spending, and offers eligible users collateral-backed credit. The tax outcome depends on the user's residence and financing arrangement.
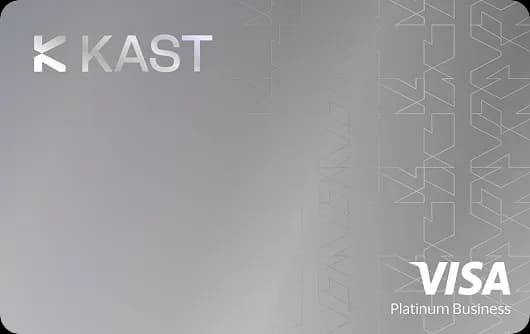
KAST sits in the middle of the stack: rewards math is modest after the May 2026 cashback restructure (1.5% USD capped at the first $2,000/month of spend, 0.5-1.75% FX), but the 2-minute Sumsub KYC flow clears the verification barrier with a Russian zagranpassport plus foreign address faster than most alternatives, which still matters when speed-to-first-purchase is the priority.
1. Tria Signature Card
High-Yield Self-Custody: 15% APY + Visa Signature Perks
2. ether.fi Core Card
3% Back on the First $2,000 Each Month, No Stake Required
3. KAST K Card
Free USD Cashback: 1.5% on First $2K/Month
Complete list:
All 12 crypto cards available in Russia in October 2026
This table includes every crypto card we currently track for Russia. Rows marked Top pick are ranked and reviewed above.
| Crypto card | Max rewards | Annual fee | FX fee | Type | Custody |
|---|---|---|---|---|---|
1 Tria Signature CardTop pick | Up to 4.5% rewards | $109/year | 1% | Debit | Self-custody |
2 ether.fi Core CardTop pick | Up to 3% rewards | Free | 0.5% | Crypto Backed Credit | Self-custody |
3 KAST K CardTop pick | Up to 1.5% rewards | Free | 0.5% | Prepaid | Custodial |
| Up to 6% rewards | $250/year | 1% | Debit | Self-custody | |
| Up to 4% rewards | Free | 0% | Crypto Backed Credit | Self-custody | |
| Up to 3% rewards | Free | 0.25% | Crypto Backed Credit | Self-custody | |
| Up to 3% rewards | Free | 0% | Crypto Backed Credit | Self-custody | |
| Up to 3% rewards | $10000 | 0.5% | Prepaid | Custodial | |
| Up to 2% rewards | $1000 | 0.5% | Prepaid | Custodial | |
| Up to 1.5% rewards | Free | 0.5% | Prepaid | Custodial | |
| Up to 1.5% rewards | $20/year | 1% | Debit | Self-custody | |
| none | Free | 1% | Prepaid | Self-custody |
Crypto Card Regulation in Russia
Russia's crypto regulatory framework is a study in contradictions. The country simultaneously legalized crypto mining, banned crypto as a payment method, developed a Central Bank Digital Currency, and hosts one of the world's most active P2P crypto trading ecosystems.
The Digital Financial Assets Law (Federal Law No. 259-FZ, January 2021)
The Federal Law on Digital Financial Assets (No. 259-FZ) took effect in 2021. It treats digital currency as property and bars its use as consideration for goods and services within Russia.
Residents can own and trade cryptocurrency, subject to the later rules on intermediaries, mining, and tax. They cannot use it to pay a domestic merchant directly.
This distinction is critical: crypto card spending is a payment, and payments in crypto are illegal under 259-FZ. Even if Visa/Mastercard rails were available, the act of converting crypto to rubles to pay a Russian merchant through a card could be interpreted as using cryptocurrency as a payment method.
Mining Legalization (Federal Law No. 221-FZ, November 2024)
Russia brought cryptocurrency mining into a registration and reporting framework through Federal Law No. 221-FZ in 2024. Legal entities and individual entrepreneurs must register to mine; individuals may mine without joining the register within the government's electricity-consumption limit. Miners also face reporting obligations to the Federal Tax Service.
Russia is the second-largest Bitcoin mining country globally after the United States, with an estimated 16-18% of global hashrate. Since the law's passage, active mining farms have grown 44% to nearly 197,000 as of early 2025. Putin also signed a law recognizing digital currencies as property and exempting crypto mining and sales from VAT.
The Central Bank of Russia (CBR, Bank Rossii)
The CBR has shifted from outright hostility to structured regulation. Building on a December 2025 CBR proposal, the State Duma passed the "On Digital Currency and Digital Rights" law on July 21, 2026 (approved by the Federation Council on July 24 and signed by President Putin on August 4, 2026), with most provisions taking effect September 1, 2026.
The law treats crypto as an investment asset rather than legal tender: domestic crypto payments stay banned, while cross-border settlement and mining are permitted. The CBR is the primary regulator, licensing exchanges and custodians and whitelisting eligible tokens, with service providers required to hold a CBR license by July 1, 2027.
Non-qualified investors can purchase up to 300,000 rubles ($3,300) worth of crypto per intermediary annually (risk-awareness test required), while qualified investors face no volume caps.
In March 2025, Russia launched a crypto experimental legal regime for international trade settlements, explicitly designed to bypass sanctions on cross-border payments. Separately, 2026 fines for using crypto as domestic payment were enacted: 100,000-200,000 rubles ($1,100-2,200) for individuals, up to 1 million rubles ($11,000) for companies. In practice, the CBR has pressured banks to flag and block transactions to crypto exchanges, though P2P workarounds remain widely used.
Sanctions Impact on Card Infrastructure
Visa and Mastercard suspended all operations in Russia effective March 10, 2022, following the US, EU, and UK sanctions packages imposed after the invasion of Ukraine. This suspension means:
- Domestic: Russian-issued Visa and Mastercard cards stopped working at Russian merchant terminals. The National Payment Card System (NSPK, Natsionalnaya Sistema Platezhnykh Kart) and its MIR network (Mir) absorbed domestic card payments. MIR cards work inside Russia, at some merchants in Turkey, Vietnam, and a handful of other countries, but are not accepted globally and no crypto card issuer uses MIR.
- International: Russian-issued cards stopped working abroad. Foreign-issued cards stopped working inside Russia. This is why crypto cards from global issuers will not process transactions at Russian merchant terminals regardless of the user's nationality.
- SWIFT restrictions: Major Russian banks were disconnected from SWIFT, complicating international transfers and making it harder for Russian nationals to fund offshore crypto accounts through traditional banking channels.
Several Russian banks have issued UnionPay cards as an alternative, but UnionPay's international acceptance is limited outside of China and Southeast Asia, and no crypto card issuer partners with UnionPay.
The EU's 19th sanctions package (October 2025) further tightened the squeeze: from January 25, 2026, EU entities are prohibited from connecting to MIR or the Fast Payments System (SBP), effectively eliminating MIR's already-limited acceptance in EU countries. The same package specifically sanctioned the ruble-backed A7A5 stablecoin (which processed $93.3 billion in less than a year), signaling that EU authorities are now targeting crypto-based sanctions evasion directly.
On April 23, 2026, the EU adopted its 20th sanctions package. It restricts Russian-established crypto-asset service providers and some associated routes for moving funds.
The package adds two entries to Annex LIII (the EU's list of prohibited crypto-assets): the private ruble stablecoin RUBx and the digital ruble itself, with the prohibition taking effect 24 May 2026. The package also designates the Kyrgyzstan-based exchange TengriCoin (operating as Meer.kg), where significant volumes of the A7A5 ruble stablecoin are traded, as an anti-circumvention target.
For EU-licensed crypto card issuers and exchanges, the practical effect is that any transaction routing through a Russian-established service provider, the digital ruble, or these named ruble stablecoins is sanctionable under MiCA's screening obligations.
Digital Ruble (Tsifrovoy Rubl)
The CBR began piloting the digital ruble in 2023. From September 1, 2026, the largest banks and retailers must offer the relevant infrastructure, widening access beyond the pilot. The digital ruble is a CBR-issued payment instrument on a CBR-controlled platform, not a public-chain cryptocurrency.
It is designed to complement, not replace, cash and bank deposits. The CBR has stated that the Digital Ruble will enable programmable payments, government-to-person transfers, and cross-border settlement (potentially with China's e-CNY). The Digital Ruble is not cryptocurrency and does not interact with the crypto card ecosystem.
Since the EU's 20th sanctions package adopted it onto Annex LIII, the digital ruble is also formally on the bloc's list of prohibited crypto-assets, with the EU-side prohibition effective from 24 May 2026.
For Russian nationals abroad, the practical regulatory takeaway is this: owning and trading cryptocurrency is legal under Russian law. Using it as a payment method inside Russia is not. Mining is legal if registered. Tax obligations apply regardless of where transactions occur. The Visa/Mastercard suspension eliminates all practical crypto card usage within Russian territory.
Tax Treatment of Card Rewards in Russia
Cryptocurrency is taxed in Russia under the personal income tax (NDFL, Nalog na Dokhody Fizicheskikh Lits) framework. The Federal Tax Service (FNS, Federalnaya Nalogovaya Sluzhba) treats cryptocurrency as property. Disposing of crypto - selling for rubles, exchanging for another cryptocurrency, or spending through a card - triggers a taxable event.
Tax Rates
- 13% NDFL on the relevant annual tax base up to 2.4 million rubles
- 15% NDFL on the portion of that base above 2.4 million rubles
The Federal Tax Service states these rates for individual income from the sale and other disposal of digital currency. Documented acquisition costs matter. Other income can affect the rate, but the calculation depends on which tax bases are aggregated in the taxpayer's circumstances.
Worked Example
You acquired 1 BTC for 5,000,000 RUB. If you sell 0.1 BTC for 700,000 RUB to fund spending abroad, its proportionate acquisition cost is 500,000 RUB and the gain is 200,000 RUB. At a 13% marginal rate the tax would be 26,000 RUB; it would be higher if that gain falls above the 2.4-million-ruble threshold.
If instead you fund a crypto card with USDT purchased at 92 RUB per USDT and spend when USDT is at 93 RUB, your gain on a 500,000 RUB spend is approximately 5,400 RUB (the 1 RUB appreciation per USDT across approximately 5,400 USDT). Tax owed: approximately 700 RUB. The stablecoin route reduces the taxable gain by over 97%.
Mining Income
Under the 2024 mining law (221-FZ), mined cryptocurrency is taxable at the fair market value on the date of receipt. If you mine 0.01 BTC and its value at receipt is 50,000 RUB, that 50,000 RUB is income subject to NDFL. When you later spend or sell that mined crypto, you owe additional NDFL on any appreciation above the receipt value.
| Cashback Type | Tax When Received | Tax When Spent via Card | Total Tax Burden |
|---|---|---|---|
| BTC cashback | Depends on reward classification | Gain or loss may arise | Case-specific |
| USDC/USDT cashback | Depends on reward classification | RUB value may change | Case-specific |
| Points | Unclear under RF law | Unclear | Uncertain |
Reporting and Filing
Tax declarations (forma 3-NDFL) are filed annually by April 30 for the preceding calendar year. Tax payment deadline is July 15. The FNS has not yet implemented automated crypto transaction reporting from exchanges (unlike the EU's DAC8), but voluntary declaration is legally required.
- Foreign wallet reporting: Under the digital-assets framework taking effect September 1, 2026, Russian residents are expected to report their crypto holdings to the Federal Tax Service by balance and turnover rather than by disclosing specific foreign wallet addresses. The CBR and FNS are still finalizing the implementing rules, so the exact reporting mechanics are not yet settled.
Russian tax treaties (SODN, Soglasheniya ob Izbezhanii Dvoynogo Nalogooblozheniya) with many countries have been suspended or modified since 2022, creating potential double-taxation risks for Russian nationals with tax obligations in multiple jurisdictions.
Russians who relocated to countries such as the UAE, Georgia, or Armenia should evaluate their tax residence and the source of their income. Citizenship alone does not mean Russia automatically taxes all foreign income for a full year after residence ends.
The optimal strategy for Russian nationals spending crypto abroad is to fund cards with stablecoins (USDC or USDT), minimizing the taxable gain per transaction. Track every transaction for 3-NDFL filing. If you hold dual tax residency, evaluate which jurisdiction's tax treaty (if any) still applies.
How to Apply from Russia
For Russian nationals applying to globally available crypto card issuers from abroad, the KYC process depends entirely on your current country of residence, not your citizenship.
Russian internal passport (vnutrenniy pasport): Not accepted by any international crypto card issuer. This document is for domestic Russian use only and has no international validity.
Russian international passport (zagranichnyy pasport, zagranpassport): Accepted as proof of identity by most issuers including KAST and Crypto.com. However, issuers also require proof of address, and a Russian address will trigger rejection or enhanced due diligence at most platforms due to sanctions compliance screening.
Required for successful verification:
- Zagranpassport (international passport) as identity document
- Proof of address in your current country of residence (utility bill, bank statement, or lease agreement dated within the last 3 months)
- Local residency permit or visa in the country where you reside (UAE residence visa, Georgian temporary residence permit, Turkish ikamet, Armenian residence card, etc.)
Verification timeline: 1-3 business days for most issuers. KAST offers the fastest verification (under 2 minutes for basic tier).
Physical card shipping: Only to your registered address in your country of residence. No issuer ships physical cards to Russian addresses. Virtual cards (e.g., KAST Standard) are available immediately after verification and do not require physical delivery.
INN (Individualnyy Nomer Nalogoplatelshchika): Your Russian taxpayer identification number is not required by any international crypto card issuer but may be needed for Russian tax filing purposes if you maintain Russian tax residency.
Sanctions screening: All Visa and Mastercard-issuing platforms run sanctions screening against OFAC (US), EU, and UK sanctions lists. Being a Russian national does not automatically trigger rejection, but being a Russian Politically Exposed Person (PEP), having addresses in Crimea, Donetsk, Luhansk, Zaporizhzhia, or Kherson, or having financial connections to sanctioned entities will result in automatic rejection.
Standard Russian citizens with clean backgrounds and non-Russian residency addresses typically pass compliance screening.
Spending Tips for Russia
The Core Reality: Crypto Cards Are a Diaspora Tool
For the estimated 500,000-1,000,000 Russians who relocated after February 2022, crypto cards solve a financial infrastructure gap. Many relocated with cryptocurrency as their most portable asset. Traditional banking in destination countries often requires months of residency before full account access. A crypto card funded with USDT or USDC provides immediate Visa/Mastercard spending power while banking infrastructure catches up.
Destination-Specific Strategies
UAE (Dubai, Abu Dhabi): The absence of personal income tax can improve the card economics for a UAE tax resident, but residence and any continuing Russian tax obligations still matter. At $2,200/month of spend, Tria Signature earns 4.5% on the first $1,000 and 1% above it; FX, per-payment, and membership fees reduce the return.
Losing Russian tax residence changes the treatment of foreign income, though Russian-source income may remain taxable. Tria Signature pays 4.5% on the first $1,000/month (then 1%), with 1% FX and 0.5% per payment.
Crypto.com Icy adds 4% rewards and airport lounge access at DXB/AUH. See the UAE guide for local eligibility and tax context.
Turkey (Istanbul, Antalya): Turkey has no specific capital gains tax on cryptocurrency as of 2025. The TCMB (Turkiye Cumhuriyet Merkez Bankasi) banned crypto as a payment method in April 2021 but did not ban ownership, trading, or conversion to fiat. This means a Russian national with Turkish ikamet spending via a crypto card funded with USDT faces zero Turkish crypto capital gains tax on the card spend itself.
Turkey is also uniquely valuable as a banking intermediary for Russians: Turkish banks (Ziraat, Halkbank, IS Bank) still accept Russian passport holders, and some Russian-to-Turkish bank transfer corridors remain operational. The practical flow is: ruble income in Russia → transfer to Turkish bank (or P2P USDT) → load crypto card → spend in lira at Turkish merchants.
Istanbul has broad Visa/Mastercard acceptance at restaurants, supermarkets, and online merchants. KAST pays 1.5% USD cashback on the first $2,000/month of spending with no annual fee and 0.5-1.75% FX.
For higher spend, Tria Signature pays 4.5% on the first $1,000/month (then 1%) and charges 1% FX plus 0.5% per payment. Eligibility still depends on a supported residency and address.
Monthly costs in Istanbul (Kadikoy/Besiktas neighborhoods, mid-range): rent 25,000-40,000 TRY ($750-$1,200), utilities 2,000-3,000 TRY, groceries 8,000-12,000 TRY, transportation 2,000 TRY (Istanbulkart + occasional taxi). Total: approximately $1,400-$2,000/month. Antalya is 20-30% cheaper. See our Turkey guide for full tax and card details.
Georgia (Tbilisi, Batumi): Georgia has become the single most important destination for Russian crypto card users. The combination of factors is difficult to match: 1% tax under the small business regime (maltsodne biznesi) for individuals earning under 500,000 GEL (approximately $185,000), visa-free entry for Russian nationals (1 year stay, renewable), fast temporary residency permits, and low cost of living.
Full Visa/Mastercard acceptance in Tbilisi and a tech-friendly culture that emerged from the influx of Russian and Ukrainian IT workers since 2022 complete the picture.
Tbilisi has a large Russian-speaking community and active crypto trading. Bank of Georgia and TBC Bank may offer accounts to qualifying Russian nationals with Georgian residency documents.
Funding a Crypto.com or ether.fi card through a bank transfer depends on the issuer and bank account; do not assume every transfer is instant.
Monthly costs in Tbilisi (Saburtalo/Vake neighborhoods): rent 1,500-3,000 GEL ($550-$1,100), utilities 200-400 GEL, groceries 600-1,000 GEL, transportation 100-200 GEL (metro + Bolt). Total: approximately $900-$1,700/month.
A Russian relocant spending $1,200/month via KAST at 1.5% USD cashback (capped at the first $2,000/mo) and 0.5-1.75% FX earns modest rewards on every transaction. Batumi on the Black Sea coast is cheaper still and popular for remote workers.
Georgia's 1% small-business regime applies to qualifying business turnover, not automatically to a personal card reward. The regime does not establish a universal 1% tax on cashback.
For a Russian national living in Georgia, determine tax residence and classify any reward separately. The Georgia guide covers the local rules in more detail.
Armenia (Yerevan): Armenia taxes personal income at a flat 20% but crypto-specific guidance remains limited. The Central Bank of Armenia (CBA) has not issued specific crypto card regulations and there is no dedicated crypto tax regime. This ambiguity works in users' favor for now but could change.
Armenian residency is easy to obtain for Russian nationals: visa-free entry, temporary residency permit obtainable within 2-3 weeks, and a well-established Russian-speaking community in Yerevan. Card acceptance in Yerevan is strong at SAS Supermarket, Carrefour, Yerevan Mall, and most restaurants in the city center. Smaller shops and regional towns may be cash-preferred.
Monthly costs in Yerevan (Center/Arabkir neighborhoods): rent 200,000-400,000 AMD ($500-$1,000), utilities 30,000-60,000 AMD, groceries 80,000-120,000 AMD, transportation 15,000-30,000 AMD. Total: approximately $700-$1,400/month. Armenia's main drawback compared to Georgia is the higher tax rate (20% vs 1%) and less developed crypto infrastructure.
Kazakhstan (Almaty, Astana): Kazakhstan is unique among Russian diaspora destinations because it established a dedicated crypto regulatory framework through the Astana International Financial Centre (AIFC). The AIFC operates under English common law (separate from Kazakh civil law) and licenses crypto exchanges and service providers. Binance held an AIFC license before its Russia exit.
Russian nationals relocate to Kazakhstan in large numbers due to visa-free entry, shared language (Russian is widely spoken), geographic proximity (you can drive from southern Russia to Almaty), and the AIFC's regulatory clarity. Kazakhstan taxes crypto gains at 10% for individuals, below Russia's 13-15% NDFL and well below Armenia's 20%.
Monthly costs in Almaty (Bostandyk/Medeu districts): rent 200,000-400,000 KZT ($400-$800), utilities 30,000-50,000 KZT, groceries 100,000-150,000 KZT, transportation 20,000-40,000 KZT. Total: approximately $650-$1,200/month. Astana is comparable or slightly cheaper.
KAST works in Kazakhstan with local Visa/Mastercard acceptance at Magnum supermarkets, Glovo delivery, and major shopping centers. The tenge fluctuates against the dollar, making USDT-funded crypto cards a hedge against local currency depreciation. See our Kazakhstan guide for the AIFC framework details.
Funding Your Card: The Cross-Border Money Problem
The fundamental challenge for every Russian crypto card user is the same: how do you get value from inside the Russian financial system into a form that can fund a globally usable crypto card? The Visa/Mastercard suspension and SWIFT disconnection mean there is no direct, legal, low-friction path from a Sberbank account to a KAST card balance. Every route involves friction, fees, risk, or some combination of all three.
Route 1: P2P Ruble-to-USDT (Inside Russia)
The most common fiat on-ramp for Russian users. Telegram-based OTC bots and channels handle ruble-to-USDT trades at 0.5-2% above market rate. The transaction occurs peer-to-peer: you send rubles via SBP (Sistema Bystrykh Platezhey) or card-to-card transfer, and USDT is sent to your wallet address. This method avoids direct bank-to-exchange transfers that trigger compliance flags.
BestChange.ru aggregates hundreds of exchangers with reputation ratings, volumes, and reserve levels. The typical flow is: Sberbank/Tinkoff rubles → SBP transfer to P2P counterparty → USDT to your Tron (TRC-20) or Ethereum wallet → load onto crypto card.
P2P risks are serious and underreported. The single biggest danger is receiving a bank transfer from a counterparty whose rubles originate from fraud, theft, or other criminal activity. When the victim reports the fraud, Russian banks trace the money chain and freeze every account that touched those funds, including yours, even if you had no knowledge of the origin.
Tinkoff (T-Bank) is particularly aggressive with account freezes, sometimes blocking accounts for months during investigation with no communication about the timeline or reason. Sberbank and Alfa-Bank also freeze accounts but tend to resolve faster (typically 2-4 weeks vs Tinkoff's potential months).
To mitigate this risk: use only established OTC desks with long track records and high BestChange ratings (look for exchangers with 5,000+ completed trades), never accept transfers from unknown individuals directly, and prefer SBP transfers (which have per-transaction limits of 1 million rubles that cap your exposure) over large card-to-card transfers.
Keep your P2P trading account separate from your primary salary account so a freeze does not cut off all your finances, and break large conversions into multiple smaller transactions across different days.
Route 2: Turkish Bank Intermediary
Russian nationals with Turkish ikamet (residence permit) can open bank accounts at Turkish banks (Ziraat Bankasi, Halkbank, IS Bank, Garanti BBVA). Many Turkish banks still accept Russian passport holders and process ruble-denominated incoming transfers from Russian banks via SWIFT alternatives or correspondent banking relationships that remain operational.
Once funds arrive in a Turkish lira or USD account, the user can transfer to a crypto exchange (Binance Turkey remained operational longer than Binance Russia), buy USDT, and load a crypto card. The conversion chain is: Russian bank → Turkish bank (ruble or USD) → crypto exchange → USDT → crypto card. Total friction cost is typically 3-5% across FX spreads and transfer fees, but the route avoids P2P counterparty risk entirely.
Route 3: Georgian Banking Bridge
Georgia's banking system (Bank of Georgia, TBC Bank) accepts Russian nationals with Georgian residency. Some Russian-to-Georgian bank transfers still process, though with delays and compliance scrutiny.
The key advantage of the Georgian route is that once funds are in a Georgian bank account, the user has full access to SEPA transfers (Georgia is not in the EU but Georgian banks have SEPA connectivity), global exchanges, and direct card funding. Russian freelancers in Georgia often receive client payments directly to Georgian bank accounts, bypassing the Russian banking system entirely.
Route 4: Direct Crypto Loading (No Banking Required)
For users who already hold crypto from mining, airdrops, DeFi yield, or prior trading, loading a KAST card with USDT from a self-custody wallet bypasses the banking system entirely. No bank account is needed at any step. This is the cleanest route for Russian users: the entire flow from crypto asset to card spending happens outside any banking system.
Route 5: Offshore Exchange Accounts
Russian nationals with non-Russian bank accounts (UAE, Turkey, Georgia, Armenia, Kazakhstan) can fund exchanges like Crypto.com, OKX, or Bybit directly via bank transfer from their foreign accounts, then load crypto cards from the exchange balance. This is the cleanest route for established diaspora members who have already set up foreign banking.
Route 6: Employer/Client Payments Directly in Crypto
A growing number of Russian freelancers and remote workers negotiate crypto payments directly. The employer or client sends USDT or USDC to the worker's wallet, skipping the entire ruble-to-crypto conversion process.
Russian developers on platforms like Upwork, Fiverr, and direct client relationships increasingly receive stablecoin payments, especially from clients who do not want to deal with bank transfers to Russian or post-Russian banking jurisdictions. The crypto card then converts these stablecoin earnings into everyday spending power.
Spending Scenarios
Scenario: Russian developer in Dubai, $3,000/month spend
| Funding Method | Card | Monthly Cashback | Annual Cashback | Tax (UAE) | Net Annual Gain |
|---|---|---|---|---|---|
| USDC from freelance income | Tria Sig 4.5% to $1K/mo | $20 net | $780 gross - $540 fees - $109 = $131 | 0% | $131 |
| USDC from freelance income | Crypto.com Icy 4% | $120 | $1,440 | 0% | $1,440 + lounges |
| BTC from mining | KAST 1.5% USD cashback (cap $2K/mo) | $30 (capped) | $360/yr | 0.5-1.75% FX | ~$60-300/yr net after FX |
Scenario: Russian relocant in Tbilisi, 150,000 RUB/month spend (approx. $1,650)
| Funding Method | Card | Monthly Cashback | Annual Cashback | Tax (Georgia 1%) | Net Annual Gain |
|---|---|---|---|---|---|
| USDT via P2P | KAST 1.5% USD cashback (capped at $2K/mo) | $24.75 (1.5% of $1,650) | $297/yr | approx. $3 | ~$50-200/yr net after FX |
Common Mistakes and How to Avoid Them
Mistake 1: Using your primary Sberbank/Tinkoff account for P2P crypto trading. If your P2P counterparty's funds turn out to be linked to fraud, your account gets frozen. If that account holds your salary, rent money, and savings, you lose access to everything.
How to avoid it: Open a separate account at a different bank specifically for P2P trades. Keep only the amount needed for the next trade in this account. SBP transfers between your own accounts at different banks are instant and free up to 100,000 RUB/month.
Mistake 2: Assuming your Russian tax obligations disappear when you leave. Check the days that determine Russian tax residence and whether continuing Russian-source income must be reported. A Russian passport alone does not extend worldwide taxation for a fixed year after departure.
How to avoid it: File 3-NDFL for any year where you had Russian-source income, even if you lived abroad for most of it. Consult a Russian tax advisor (nalogovyy konsultant) about the specific transition rules for your departure year.
Mistake 3: Loading a crypto card with volatile assets instead of stablecoins. A Russian developer in Tbilisi loads 0.5 ETH onto a card when ETH is $3,200, planning to spend over the month. ETH drops to $2,800, and the card balance is now worth 12.5% less. On a $1,600 monthly budget, that is a $200 loss before any spending occurs.
How to avoid it: Convert volatile crypto to USDC or USDT before loading your card. The 0.1% stablecoin spread is negligible compared to the potential 10-20% drawdown on BTC or ETH during a bad week. KAST supports direct USDT loading.
Mistake 4: Neglecting to save proof of your crypto acquisition cost. When the FNS eventually implements automated crypto reporting (DAC8 equivalent is under discussion), you will need to prove your cost basis for every disposal. Without records, the FNS can assess tax on the full sale/spend amount with zero cost basis deduction, effectively taxing you on 100% of the transaction value instead of just the gain.
How to avoid it: Screenshot or export every buy/trade from exchanges and P2P platforms. Save wallet transaction hashes. Use a crypto tax tracker that supports Russian NDFL reporting.
Local Payment Infrastructure Inside Russia
For context on what crypto cards would need to compete with domestically (if they ever became functional):
- MIR (Mir): The National Payment Card System processes all domestic card payments. MIR cards work at every terminal in Russia. International acceptance is limited to a handful of countries (Turkey partially suspended MIR in September 2022 under US pressure, Vietnam and some CIS countries still accept).
- SBP (Sistema Bystrykh Platezhey): The CBR's fast payment system enables instant bank-to-bank transfers and QR code payments. SBP has grown rapidly since 2022, processing over 2 billion transactions in 2024. Many Russian merchants now prefer SBP QR payments over card payments due to lower merchant fees.
- Yandex Pay and SberPay: Domestic mobile payment wallets that work with MIR cards. Apple Pay and Google Pay stopped supporting Russian cards in March 2022.
- Cash: Despite rapid digitalization, cash remains important. The CBR reports that cash in circulation reached 18.3 trillion rubles by end of 2024, with cash representing approximately 18% of consumer payments.
The Self-Custody Argument for Russian Users
Given the geopolitical risk environment, self-custody carries particular weight for Russian users. Centralized exchanges have frozen Russian user accounts in response to sanctions pressure (Binance sold its Russian operations to CommEX in September 2023, which itself later shut down in March 2024, causing disruption for users).
Self-custodial wallets reduce reliance on an exchange account, although card issuers and compliance providers can still restrict card access. For users who have experienced account freezes, self-custody is a practical consideration rather than just a philosophical preference.
Russian nationals who relocate to EEA countries may gain access to self-custody card options such as Gnosis Pay using qualifying host-country documents. Ready was another option, but its card program is currently unavailable after its issuer began winding down.
Supported Exchanges & Wallets in Russia
The Russian crypto card market is defined by absence. No major crypto card issuer explicitly targets Russian residents inside Russia, because the Visa/Mastercard suspension makes domestic card transactions impossible.
Who Left Russia
Binance: Once the dominant exchange in Russia by trading volume, Binance sold its Russian operations to CommEX in September 2023 under regulatory pressure. CommEX operated for approximately six months before shutting down in March 2024, leaving former Binance Russia users scrambling to withdraw funds. Binance no longer serves Russian residents and its card (Brazil-only) was never available in Russia.
Visa and Mastercard: Suspended all Russian operations effective March 10, 2022. Russian-issued Visa/Mastercard cards stopped working both domestically and internationally. Foreign-issued Visa/Mastercard cards stopped working inside Russia. This single event is the reason crypto cards do not function in the Russian market.
Coinbase, Gemini, Kraken: Never meaningfully served Russia. Coinbase is US-only. Gemini is US-only. Kraken served some Russian users but restricted Russian accounts in 2022.
Who Technically Serves Russian Nationals Abroad
Crypto.com: Does not explicitly serve Russian addresses, but Russian nationals with verified non-Russian residency may access the platform. Compliance screening applies. Six card tiers available, from Midnight Blue (free, no cashback) through Obsidian ($500K CRO stake, 5% cashback, lounge access).
KAST: Global availability with fast KYC (2 min) requirements. Card lineup spans four tiers (Standard, Premium, Limited, Luxe) plus the Pudgy Penguins-branded Pengu collection. USD cashback ranges from 1.5% (Standard) to 3% (Luxe) within tier-specific monthly caps. The 2-minute Sumsub verification makes it one of the most accessible options for Russian nationals with non-Russian addresses.
ether.fi: Four tiers: Core, Luxe, Pinnacle, and VIP. Core pays stepped ETHFI rewards and supports direct stablecoin spending or optional borrowing against eligible collateral. For Russian users abroad, access depends on host-country residence documents, and any tax benefit from borrowing depends on that jurisdiction.
Tria Signature: 4.5% on the first $1,000/month (then 1%) in USDT cashback with a $109/year fee, a 1% FX fee, and 0.5% per payment (about 3% net). Breaks even at about $303/month of spending. For settled diaspora in UAE, Turkey, or Georgia earning stable income, this is the strongest no-stake, self-custody pick on net return. Visa Signature perks include auto rental CDW, baggage delay/loss coverage, and concierge.
Local Russian Exchanges
Garantex: Was Russia's largest domestic crypto exchange by volume until it was sanctioned by the US Treasury (OFAC) in April 2022 and by the EU in February 2024. Garantex continued operating despite sanctions, processing an estimated $96 billion in transactions by 2024. In March 2025, Garantex was seized by international law enforcement. Using Garantex or its successor platforms carries serious legal risk for anyone with connections to Western financial systems.
Local P2P ecosystem: With Garantex gone and major international exchanges withdrawn, Russia's crypto trading has become overwhelmingly P2P and Telegram-based. The ecosystem operates in layers: BestChange.ru sits at the top as an aggregator, listing hundreds of independent exchange services with their rates, reserves, and reputation scores.
Below that, Telegram channels operate as OTC desks, some with automated bots handling trades up to millions of rubles. The larger channels use escrow mechanisms (a trusted third party holds USDT until the ruble transfer clears), rating systems, and dispute resolution. At the bottom layer, informal face-to-face trading persists in Moscow and St. Petersburg, though volumes are small compared to the digital ecosystem.
The post-Garantex market has also pushed some volume to exchanges that maintain ambiguous compliance postures. Several exchanges registered in jurisdictions with minimal KYC requirements continue to serve Russian users. We do not name or link to these platforms because their regulatory status is uncertain and their longevity is unpredictable.
The safest approach for Russian users remains: convert rubles to USDT via established P2P channels, move USDT to a self-custody wallet, and load a globally available crypto card from there.
The Outlook for Russian Crypto Card Users
Foreign-issued Visa and Mastercard crypto cards do not presently work at Russian domestic merchants. MIR does not supply an equivalent crypto-card route, and the digital ruble is a separate central-bank payment instrument. The cards on this page are for eligible Russian nationals spending abroad.
For the diaspora, the picture is more optimistic. As Russian nationals establish themselves in destination countries, their access to crypto cards improves: local bank accounts enable exchange funding, residency permits satisfy KYC requirements, and the growing ecosystem of self-custody cards and minimal KYC cards reduces barriers.
The most financially efficient long-term setup for a Russian relocant is: local bank account in destination country + Tria Signature or Crypto.com Icy for daily spending + a self-custody wallet holding USDT/USDC that no platform can freeze.
The core lesson from the Russian experience is that financial sovereignty matters. When Visa, Mastercard, SWIFT, and exchanges can all be turned off simultaneously, the ability to hold assets in self-custody and spend them through decentralized channels is not a philosophical preference but a practical necessity. Russia's 17-20 million crypto holders learned this in real time.
Written by SpendNode Editorial
Frequently Asked Questions
Do crypto cards work inside Russia?
No, not for domestic purchases. Visa and Mastercard suspended operations in Russia in March 2022. Russian nationals living abroad can use globally available crypto cards (KAST, Tria Signature, ether.fi, Crypto.com) if they have a non-Russian address for KYC verification. Starting 2026, domestic crypto payments carry fines of 100,000-200,000 rubles for individuals.
Is cryptocurrency legal in Russia?
Ownership and mining are legal. Federal Law No. 259-FZ recognizes crypto as property. Law No. 221-FZ (Nov 2024) legalized mining - active farms have grown 44% to nearly 197,000. Putin signed a law recognizing digital currencies as property and exempting mining and sales from VAT.
In July 2026 the State Duma passed the 'On Digital Currency and Digital Rights' law (effective September 1, 2026), which treats crypto as an investment asset under CBR oversight and permits cross-border trade and mining. Domestic crypto payments remain banned.
How is crypto taxed in Russia?
Crypto gains are taxed as personal income (NDFL) at 13% on annual income up to 5 million rubles and 15% above that threshold. A 2024 amendment specifically addressed mining income, classifying mined crypto as taxable at market value when received. The disposal of crypto (selling or spending) triggers NDFL on the gain. Losses can offset gains within the same tax year. Tax declarations are filed annually by April 30 via the FNS (Federal Tax Service).
The July 2026 digital-assets law legalizes cross-border crypto trade but leaves individual crypto tax treatment unchanged.
What alternatives do Russians have to crypto cards?
Inside Russia: MIR cards (domestic payment system), SBP (Sistema Bystrykh Platezhey, fast payments via QR codes), bank transfers, and cash.
For cross-border: UnionPay cards from select Russian banks, Turkish bank accounts (popular among Russian expats), and P2P crypto trading via Telegram OTC bots for direct ruble-to-USDT conversion.
Russian nationals who relocated to UAE, Turkey, Georgia, Armenia, or Kazakhstan after 2022 can access the full global crypto card market with local residency documents.
Other Countries
View all 112 countries →


Latest Page Changes to the Best Crypto Cards in Russia Guide
- RedotPay removed from the recommended cards as it does not serve Russia
- EU 20th sanctions package (April 23, 2026), which moves from listing individual Russian crypto firms to a sectoral ban on every Russian-established crypto-asset service provider and decentralized platforms
- Annex LIII listing of the RUBx ruble stablecoin and the digital ruble itself, with the EU prohibition effective 24 May 2026
- Designation of Kyrgyzstan-based exchange TengriCoin (Meer.kg), where A7A5 ruble stablecoin volumes trade, as an anti-circumvention target
- April 22, 2026 State Duma first-reading vote on a bill that would allow crypto for foreign-trade payments
- Kept the Russia page conservative by stating clearly that the bill is not enacted yet and domestic crypto payments remain banned
- Russia's 2026 draft foreign-wallet reporting proposal would require notices for foreign-hosted crypto wallets
- The July 1, 2026 foreign-wallet reporting date remains a pending legislative target, not an enacted rule
- MAJOR regulatory updates: Mining farms grown 44% to 197,000 (since Nov 2024 legalization). Putin signed law recognizing crypto as property, VAT-exempt. CBR proposed comprehensive framework for July 2026 with 'currency asset' status and investor tiers (300K rubles/yr for non-qualified). March 2025 crypto experimental legal regime for international trade settlements (sanctions bypass)