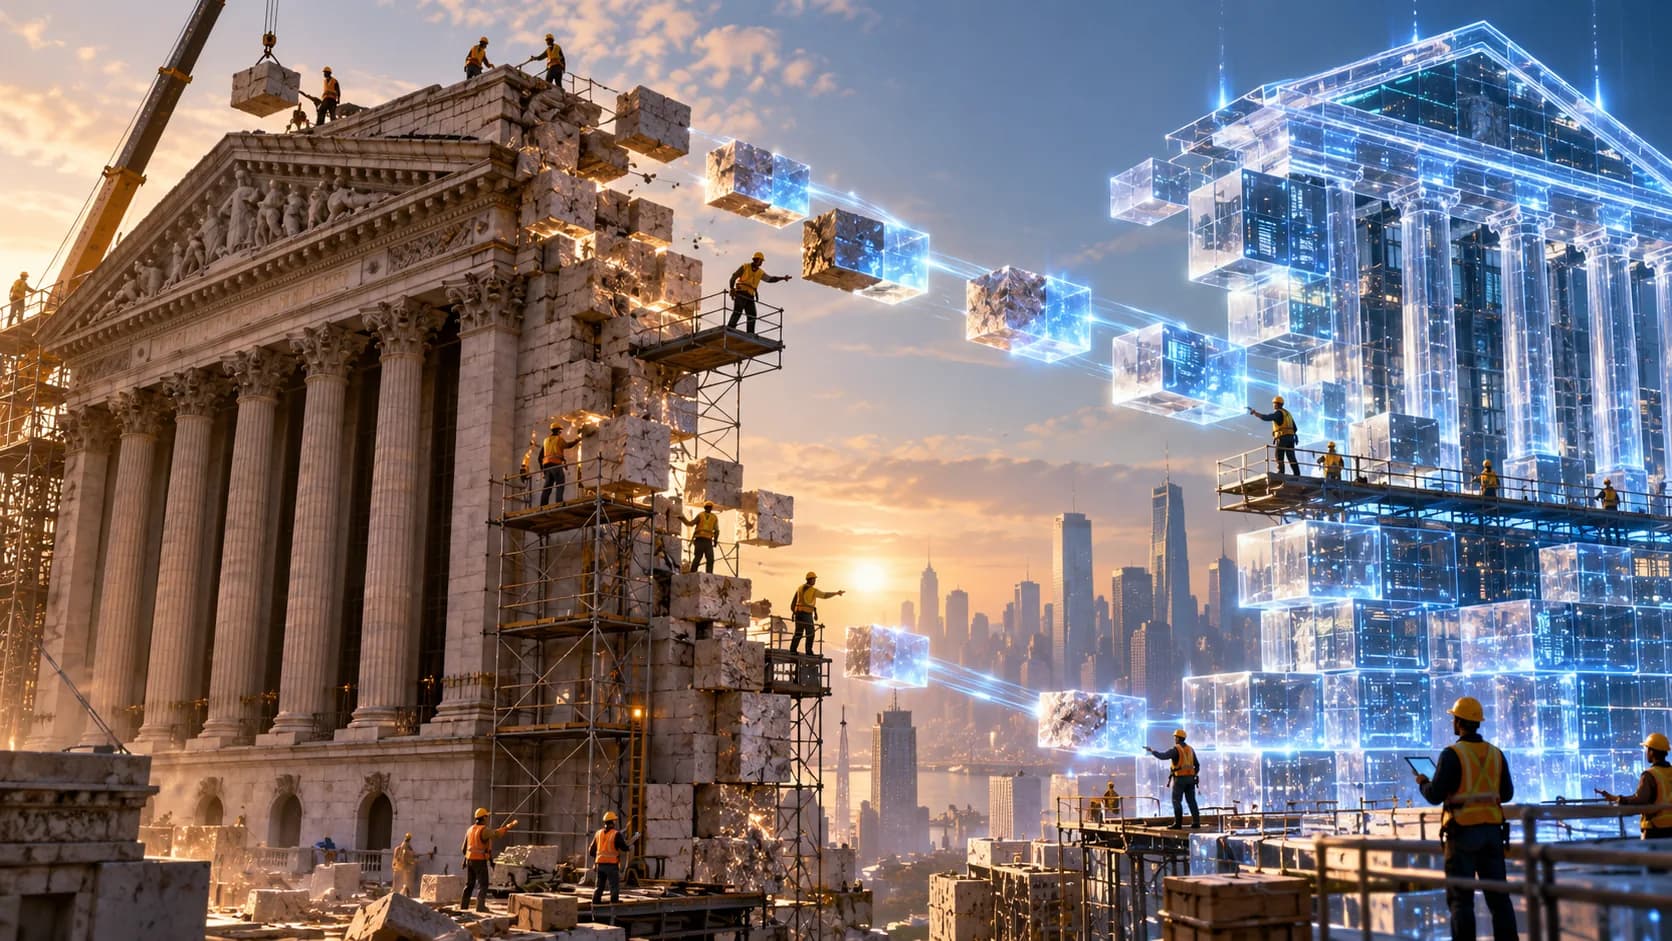
South Korea has published the official rules that let stocks, bonds and funds be issued and traded on a blockchain, according to a report shared on October 3, 2026. The move takes one of Asia's largest capital markets past the pilot stage and writes tokenized securities directly into the regulatory framework.
The headline is simple: three of the core building blocks of public markets, equities, fixed income, and fund units, are now eligible to live on-chain under a defined set of rules rather than in a regulatory grey zone. That distinction matters. Plenty of jurisdictions have run tokenization experiments or granted one-off sandbox exemptions. A published rulebook is a different signal. It tells issuers, brokers and custodians what they can build against without guessing where the line sits.
From sandbox to rulebook
For years, tokenized securities in most markets have depended on temporary waivers or narrow pilot programs. That approach caps ambition. A bank or asset manager is not going to rebuild settlement plumbing around an exemption that might lapse. South Korea putting the structure into formal rules removes that uncertainty, at least for the asset classes named.
The practical effect is that a stock, a bond, or a fund unit can be represented as a token whose ownership and transfer are recorded on a blockchain rather than through the traditional chain of central securities depositories and transfer agents. The claim on the underlying asset is the same. The record-keeping and settlement layer underneath it changes.
This is the same direction of travel visible elsewhere. Base recently shipped an upgrade adding issuer controls for tokenized assets, and platforms have started listing perpetuals on tokenized stocks. The difference here is jurisdiction and weight: this is a national regulator setting terms for its own equity and bond markets.
Settlement speed and programmable compliance
The appeal of moving securities on-chain is not speculation. It is settlement speed and programmability. Traditional securities settlement still runs on a delay, commonly a day or two after the trade, during which counterparty and operational risk sits open. A tokenized security can in principle settle closer to instantly, with the asset and the payment leg moving together.
Programmable securities also let rules travel with the asset. Dividend logic, transfer restrictions, eligibility checks, and reporting can be encoded rather than handled by separate intermediaries after the fact. That is attractive to a regulator precisely because compliance can be built into the instrument instead of bolted on.
The trade-off is that putting regulated securities on a blockchain forces hard questions about who runs the ledger, how investor identity is verified, and what happens when something goes wrong on-chain. Those are exactly the questions a formal rulebook has to answer, which is why getting one published is harder and more meaningful than running a demo.
Measured market backdrop
The announcement landed in a quiet market rather than a frenzied one. As of October 3, 2026, Bitcoin traded near $84,613, down 0.6% on the day, and Ether sat around $2,680, off 1.4%. The CoinMarketCap Fear and Greed Index read 67, in "Greed" territory, but prices were flat across the majors over the prior 24 hours.
That matters for how to read the story. This is not a price catalyst that sent tokens higher on the day. It is a structural development in regulated finance. The relevant beneficiaries are the infrastructure layers, the issuers, custodians, exchanges and chains that would carry tokenized Korean securities, not a single ticker reacting in real time.
South Korea has been active on several fronts. The country has been weighing market maker rules after a stablecoin traded at four times its peg, a reminder that regulators there are willing to intervene on market structure when they see distortion. A securities-tokenization framework fits that pattern: set the rules first, then let the market build.
The starting gun, not the finish line
The published rules are the starting gun, not the finish line. Several things will determine whether this becomes real volume or stays a well-documented option:
- Which blockchains and custody arrangements qualify under the rules, and whether they favor permissioned infrastructure over public chains.
- How quickly major Korean brokers and asset managers issue a first tokenized stock, bond, or fund under the framework.
- Whether retail investors get access or whether early issuance is gated to institutions and accredited participants.
- How the rules handle cross-border holding, since foreign demand for tokenized Korean assets depends on who is allowed to hold the tokens.
Those details decide the difference between a landmark framework and a lightly used one. For now, the signal is that a major capital market has moved tokenized securities from experiment to regulation.
Overview
South Korea has published official rules allowing stocks, bonds and funds to be issued and traded on a blockchain, moving tokenized securities out of the pilot stage and into its formal framework. The change targets the settlement and record-keeping layer rather than the assets themselves, promising faster settlement and programmable compliance. It arrived in a flat market, with Bitcoin near $84,613 and Ether near $2,680 as of October 3, 2026, underlining that this is a structural regulatory development, not a short-term price event. The open questions are which infrastructure qualifies, how fast issuers move, and who gets access.