A yen-pegged stablecoin called JPYC traded at as much as four times its intended value, according to Cointelegraph, and the dislocation has become the trigger for a regulatory rethink in South Korea. Instead of debating why a stablecoin fell below its peg, the more familiar failure mode, officials are looking at why one climbed so far above it, and what that says about who is allowed to keep prices in line.
A peg that broke in the wrong direction
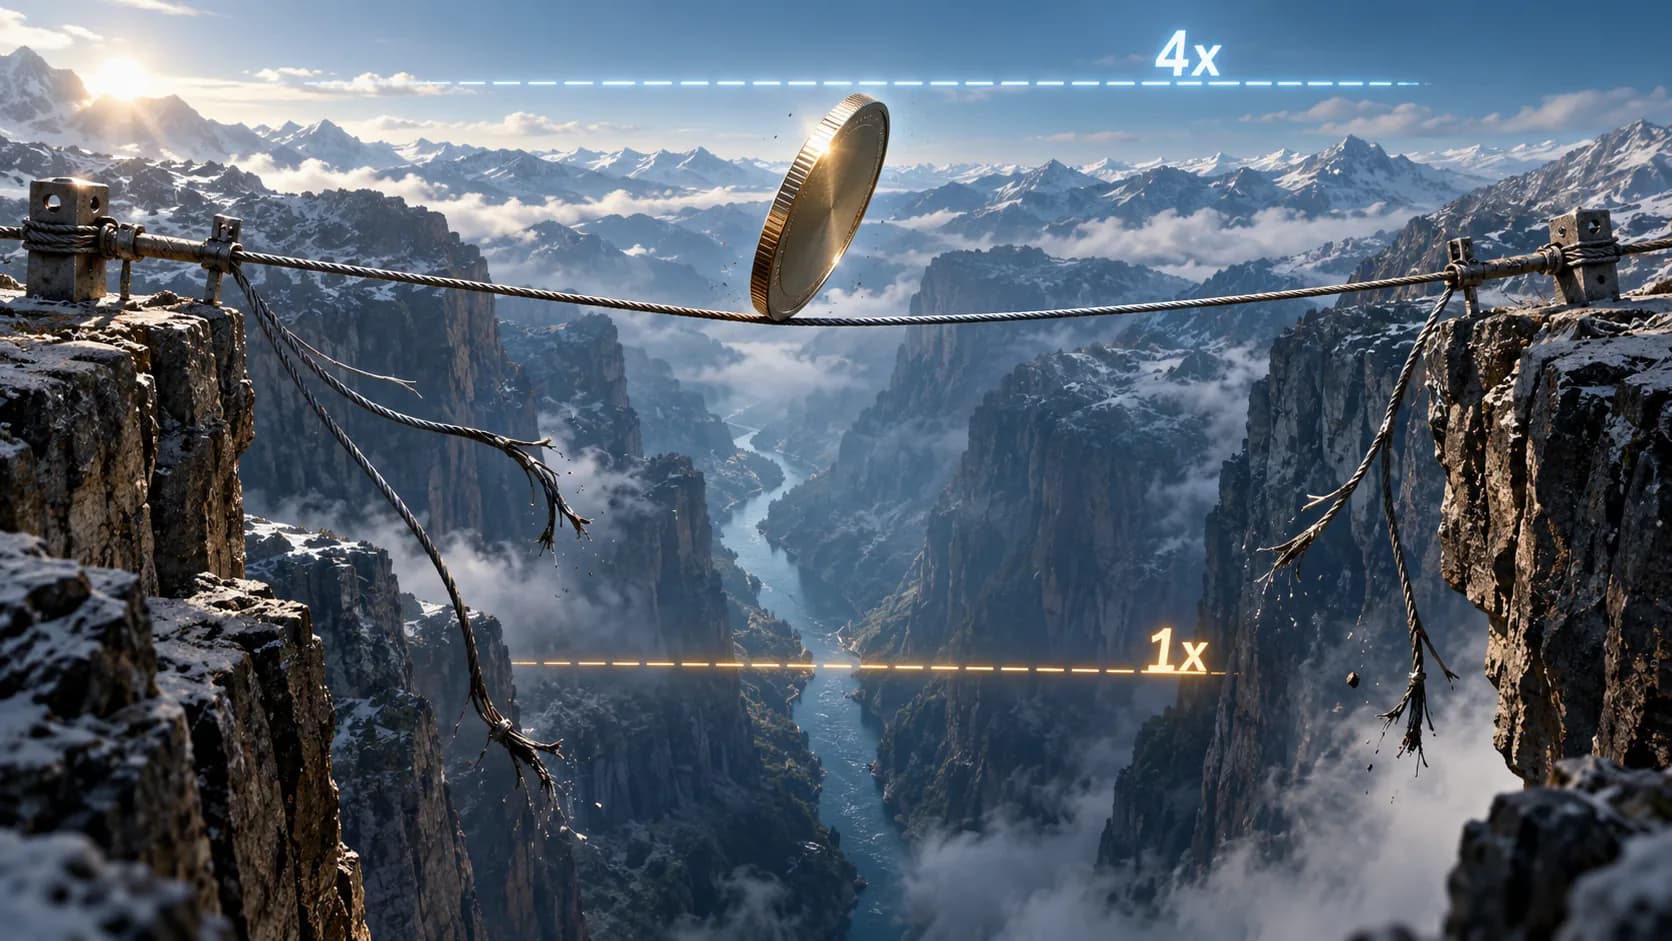
Most stablecoin scares involve a coin losing value: a token meant to hold at one dollar slips to 90 cents, holders rush the exit, and the depeg feeds on itself. JPYC's episode ran the other way. A token designed to track the Japanese yen changed hands at roughly four times where it should have, a sign that buyers wanted exposure and there was almost nothing on the other side of the trade to sell it to them at a fair price.
An upside dislocation like that is not a solvency problem in the usual sense. It points to a plumbing problem. When only a handful of participants quote a market, a burst of one-directional demand has nothing to push against, and the price detaches from the asset it is supposed to mirror. The number that stands out here is the multiple: 4x is not a rounding error or a brief wick, it is a market with no depth.
The market makers who were not there
The party that normally prevents this is a market maker, a firm that continuously posts both buy and sell quotes and profits from the spread while keeping prices tethered to fair value. In a functioning market, a stablecoin trading at 4x would be an obvious opportunity: sell the overpriced token, hedge the exposure, collect the gap. That arbitrage is exactly what drags a runaway price back toward its peg.
Per Cointelegraph, crypto market making is effectively restricted under South Korea's market manipulation rules. Provisions written to stop wash trading and price rigging also catch the routine, two-sided quoting that legitimate market makers do, which leaves local order books thinner than they would otherwise be. The JPYC blowout is being read as the visible cost of that gap: without professionals standing ready to fade extreme moves, an ordinary imbalance turned into a 4x print.
Regulators reconsidering the rulebook
South Korea's response is to weigh formal market maker rules, a framework that would carve out and license the activity rather than leave it in a legal grey zone. The regulatory question is how to permit genuine liquidity provision while still policing the manipulation the current rules were built to stop. Those two goals sit close together, since both involve firms trading heavily and on both sides of a book, and drawing the line between them is the hard part.
For a market as active as South Korea, where retail participation runs high and local premiums on crypto assets have a long history, the stakes are practical. Thin, poorly-made markets produce exactly the kind of volatile, hard-to-exit prices that regulators say they want to protect retail traders from. The JPYC event turns an abstract rule debate into a concrete example of what happens when nobody is contractually there to quote the other side.
A peg is only as reliable as the market around it
The takeaway is not specific to one yen token. It is a reminder that a stablecoin's peg is only as reliable as the market around it. The issuer's reserves and redemption promise set the fair value, but on any given venue the traded price depends on liquidity, on whether there are enough participants to absorb a lopsided flow. A coin can be fully backed and still print an absurd number on an exchange that lacks depth.
That distinction matters for anyone who treats stablecoins as a cash-like holding, including the growing set of users who spend them through crypto-linked cards. The redemption value at the issuer and the screen price on a thin exchange are not the same thing, and JPYC's 4x reading is a clean illustration of the gap. If South Korea does license market makers, the intended result is fewer of these dislocations, tighter spreads, and prices that stay closer to what the underlying asset is actually worth.
For now, the story is a regulatory one: a peg broke upward, the fix that would normally close it was sitting outside the rules, and a major market is deciding whether to bring it inside.
Overview
JPYC, a yen-pegged stablecoin, traded at as much as four times its intended value on thin liquidity, per Cointelegraph. Market making, the activity that would normally arbitrage such a gap away, is effectively restricted under South Korea's manipulation rules, leaving local books shallow. Regulators are now weighing a formal market maker framework that permits two-sided quoting without reopening the door to manipulation. The episode is a reminder that a stablecoin's peg holds only where the market around it is deep enough to defend it.