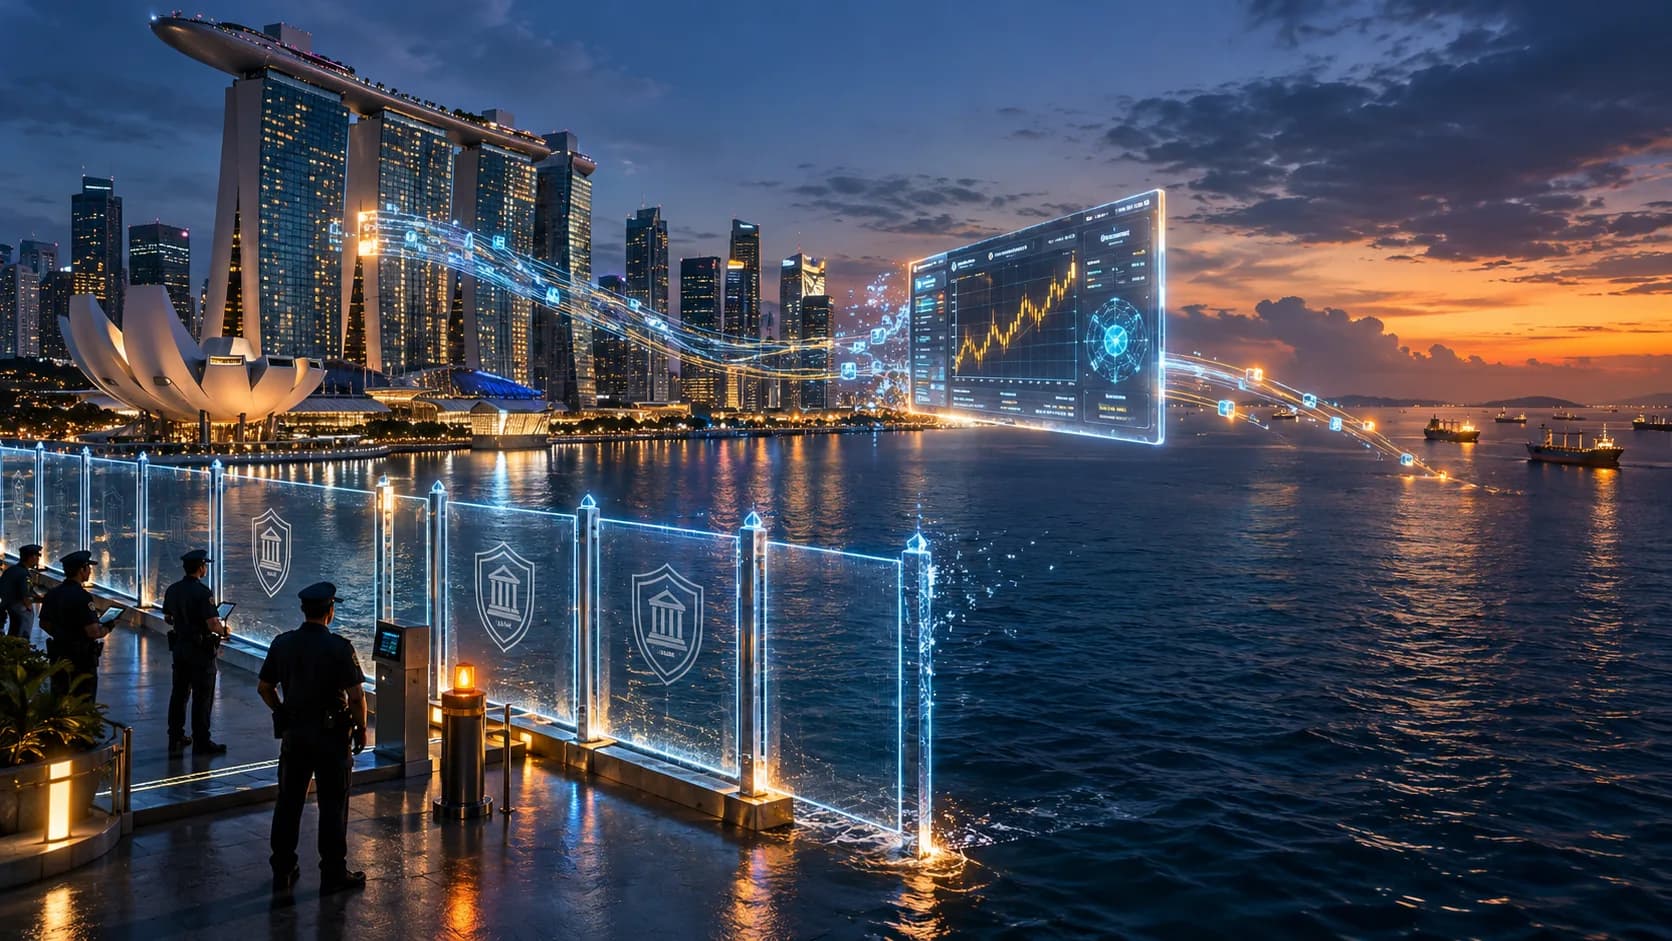
Singapore's financial regulator has signaled that Hyperliquid, one of the largest decentralized derivatives platforms in crypto, may fall outside its regulatory reach even though the firm is based in the city-state. The assessment was reported by the Financial Times and surfaced in crypto media on October 7, 2026, through industry tracker Wu Blockchain.
The core tension is straightforward. A company can have a physical address in Singapore while the product it operates lives on a blockchain that answers to no single office. That mismatch is now a live question for one of the busiest venues in onchain perpetual futures trading.
The jurisdiction gap at the center of the story
Traditional financial oversight attaches to a legal entity: a licensed broker, a registered exchange, a custodian with a known headquarters. Regulators supervise the entity, and the entity controls the service.
Decentralized platforms break that chain. Order matching, settlement, and custody can run through smart contracts and distributed infrastructure rather than through a company's internal systems. When a regulator looks for the thing it supervises, it can find a corporate shell in one place and the actual market running somewhere it cannot easily point to.
The Financial Times report frames exactly this problem. Being based in Singapore puts a firm within arm's reach of local law on paper. It does not automatically put the protocol, its users, or its order flow under the regulator's defined perimeter. That is the gap the regulator appears to be acknowledging.
A regulator admitting its limits is unusual
Most regulatory headlines involve a watchdog asserting authority: a filing, an enforcement action, a license condition. A regulator suggesting it may not have authority is a different kind of signal, and a more candid one.
It points to a design reality that the crypto industry has argued for years and that supervisors have been slower to state plainly. Code that executes without a controlling intermediary does not fit neatly into rulebooks written for intermediaries. Singapore has built a reputation as one of the more structured crypto jurisdictions, with a licensing regime for digital payment token services. An acknowledgment that a prominent, locally based platform might sit outside that structure is a notable concession about where the current framework ends.
For users, the practical reading is cautious rather than alarming. A platform operating in a regulatory gray zone is not the same as a platform operating under consumer protections. If a venue falls outside a regulator's jurisdiction, it can also fall outside the dispute, custody, and recourse mechanisms that come with being supervised.
The precedent problem for other jurisdictions
Singapore is not the only authority that will have to answer this question. The European Union is rolling out its markets in crypto-assets regime, and its own supervisors have already asked for stronger powers to police the sector. The United Kingdom has started moving firms through a formal authorization process. Each of those efforts assumes there is an entity to authorize and supervise.
A decentralized derivatives platform tests that assumption directly. If a firm can be based in a jurisdiction and still argue, credibly, that the regulated activity happens on infrastructure beyond local control, every supervisor with a crypto rulebook faces the same gap. The Singapore case is less a one-off and more a preview of a structural fight over where onchain markets actually sit.
Hyperliquid's visibility sharpens the stakes. The platform's perpetual futures data has already reached mainstream finance surfaces, including a recent appearance on the Bloomberg Terminal. A venue that institutions can watch through professional tools, while regulators debate whether they can supervise it, is an awkward position for everyone involved.
Practical takeaways for crypto users
Traders on decentralized derivatives platforms should treat regulatory status as a factor, not an afterthought. A few points follow directly from the situation:
- Jurisdiction is about where the activity runs, not only where the company is registered. A local address does not guarantee local protections.
- Supervised venues come with defined recourse. Platforms in a gray zone may not, which raises the weight you should place on self-custody and your own risk controls.
- Regulatory clarity can arrive suddenly. A gap today can become a rule tomorrow, and that can change access, listings, or availability for users in a given country.
None of this is a verdict on Hyperliquid itself. The reported position is that a regulator is weighing the limits of its own authority, which is a question about the framework as much as the firm.
The broader market stayed quiet around the report. Bitcoin traded near $85,575 and Ether near $2,698 as of October 7, 2026, both roughly flat on the day, with the Fear and Greed Index at 66, in greed territory. This is a structural and legal story, not a price event.
Overview
The Financial Times reports that Singapore's regulator may not have jurisdiction over Hyperliquid despite the derivatives platform being based in the city-state. The case highlights the gap between where a crypto firm is registered and where its onchain activity actually runs, a distinction that undercuts frameworks built for traditional intermediaries. For users, a platform outside a regulator's reach may also sit outside the protections that supervision normally provides.
This is analysis based on a single reported source and is not financial advice.