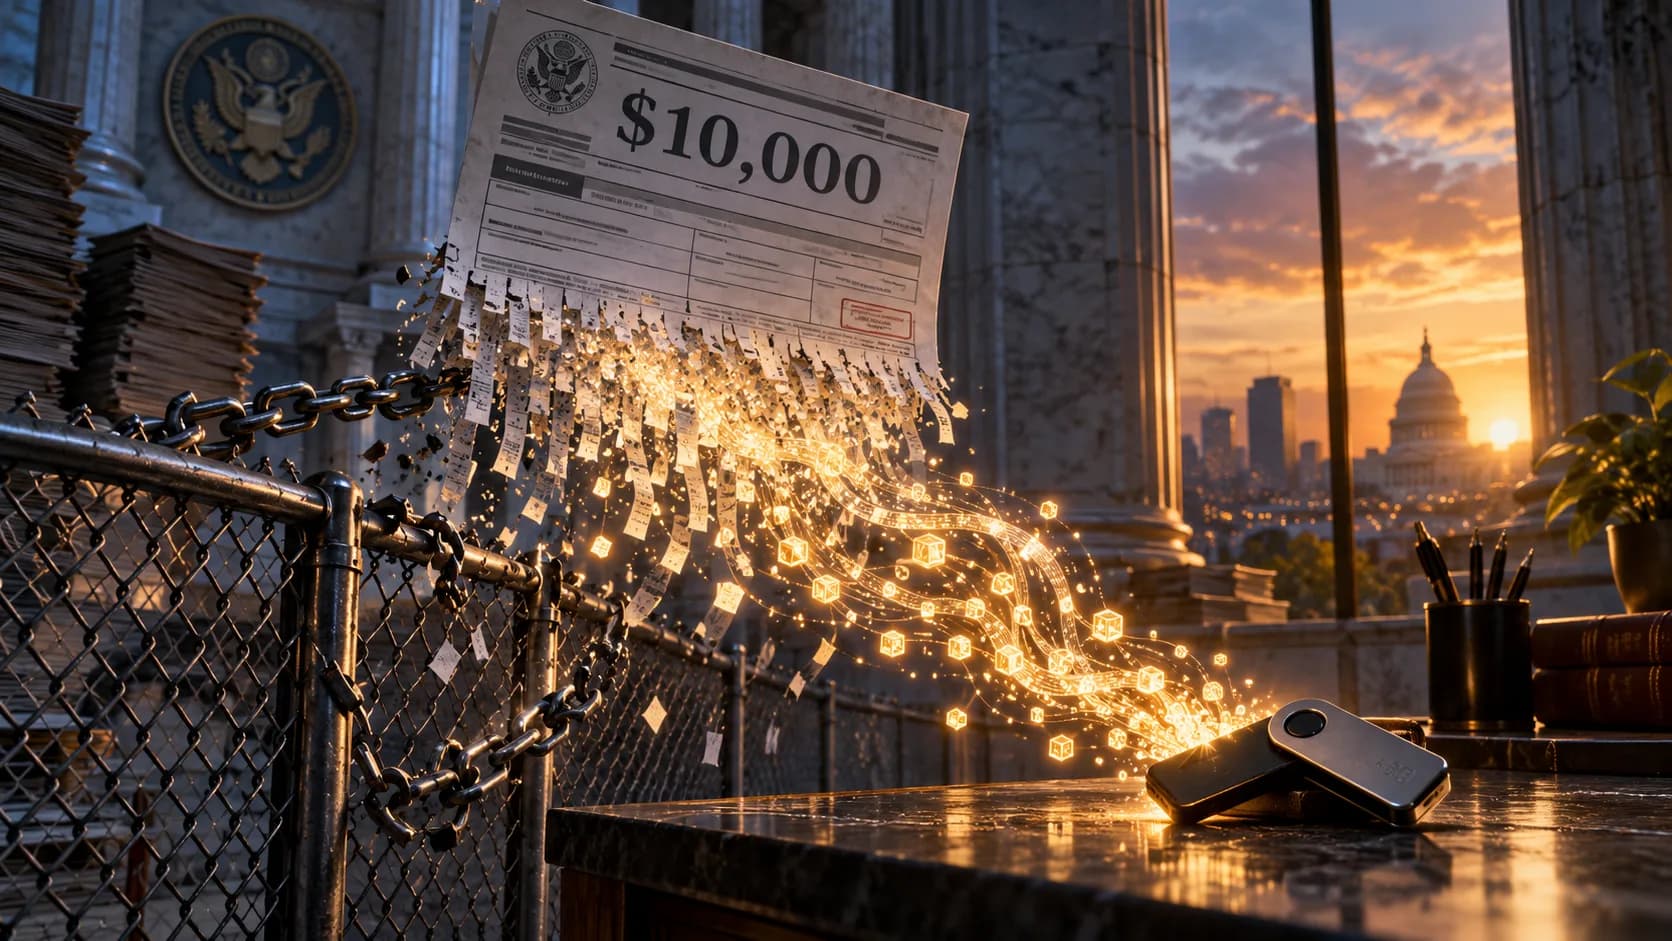
The US Treasury has withdrawn a proposed rule that would have required reporting crypto transfers over $10,000 sent to self-hosted wallets, according to a report from CoinDesk on October 6, 2026. The move removes one of the more contentious surveillance proposals that had been hanging over people who move digital assets into wallets they control themselves.
The scrapped rule would have extended cash-style reporting obligations into crypto. Transactions above the $10,000 threshold going to private, non-custodial wallets would have triggered a disclosure requirement, mirroring how large cash movements are reported to the government. Dropping it means that type of transfer stays outside that specific reporting net.
A reporting line that treated self-custody like a cash drop
The logic behind the original proposal borrowed directly from existing cash rules. Large cash transactions already carry reporting duties, and the plan would have applied a similar trigger to crypto headed for wallets without an intermediary sitting in the middle. The friction point was the destination: a self-hosted wallet has no exchange or custodian to file paperwork, so the burden and the privacy exposure landed differently than it does with a bank wire.
For anyone who holds their own keys, that framing was the problem. Moving funds from an exchange into a personal wallet is a routine part of taking custody, not an unusual event. A $10,000 line would have caught ordinary self-custody behavior rather than targeting anything specific, and it would have done so at the exact moment users step away from third-party control and onto their own keys.
Part of a broader retreat from wallet-level surveillance
This withdrawal lands in the same window as other rollbacks of wallet-focused reporting ideas. US regulators recently stepped back from a separate set of proposed obligations aimed at crypto mixers and unhosted wallets, another plan that would have pushed disclosure requirements onto transactions involving wallets outside the custodial system.
Taken together, the two reversals point in the same direction. The reporting burden that policymakers floated for self-hosted wallets is being pulled back rather than expanded. That does not rewrite the underlying tax treatment of crypto or erase other obligations that already exist, but it does remove a specific new tripwire that would have attached to the act of moving coins to a wallet you control.
A narrow but real effect for self-custody users
The practical effect is narrow but real. The transfer that would have triggered the proposed filing, crypto above $10,000 moving to a self-hosted wallet, no longer carries that particular reporting requirement. People who use self-custody options to spend or store from their own wallets avoid a disclosure step that had been on the table.
Nothing here changes the mechanics of custody itself. Holding your own keys still means you are the last line of defense: there is no issuer to reverse a mistaken send and no custodian to recover access if a seed phrase is lost. The withdrawn rule was about who reports a transfer to the government, not about who bears the risk of self-custody. That risk is unchanged.
It is also worth separating this from how regulated on-ramps operate. Exchanges and custodial card programs still run their own compliance and verification processes, and those are not affected by dropping a self-hosted-wallet reporting line. The change applies to the specific transfer the rule would have covered, not to the broader reporting landscape that already governs intermediaries.
Overview
The US Treasury has scrapped a proposed rule that would have required reporting crypto transfers over $10,000 to self-hosted wallets, per a CoinDesk report dated October 6, 2026. The proposal had aimed to apply cash-style disclosure to large transfers landing in wallets outside the custodial system. Its withdrawal, alongside a recent step back from mixer and unhosted-wallet rules, removes a specific reporting trigger for people taking custody of their own coins. Custodial intermediaries and existing obligations are unaffected, and the risks of self-custody remain the user's to manage.