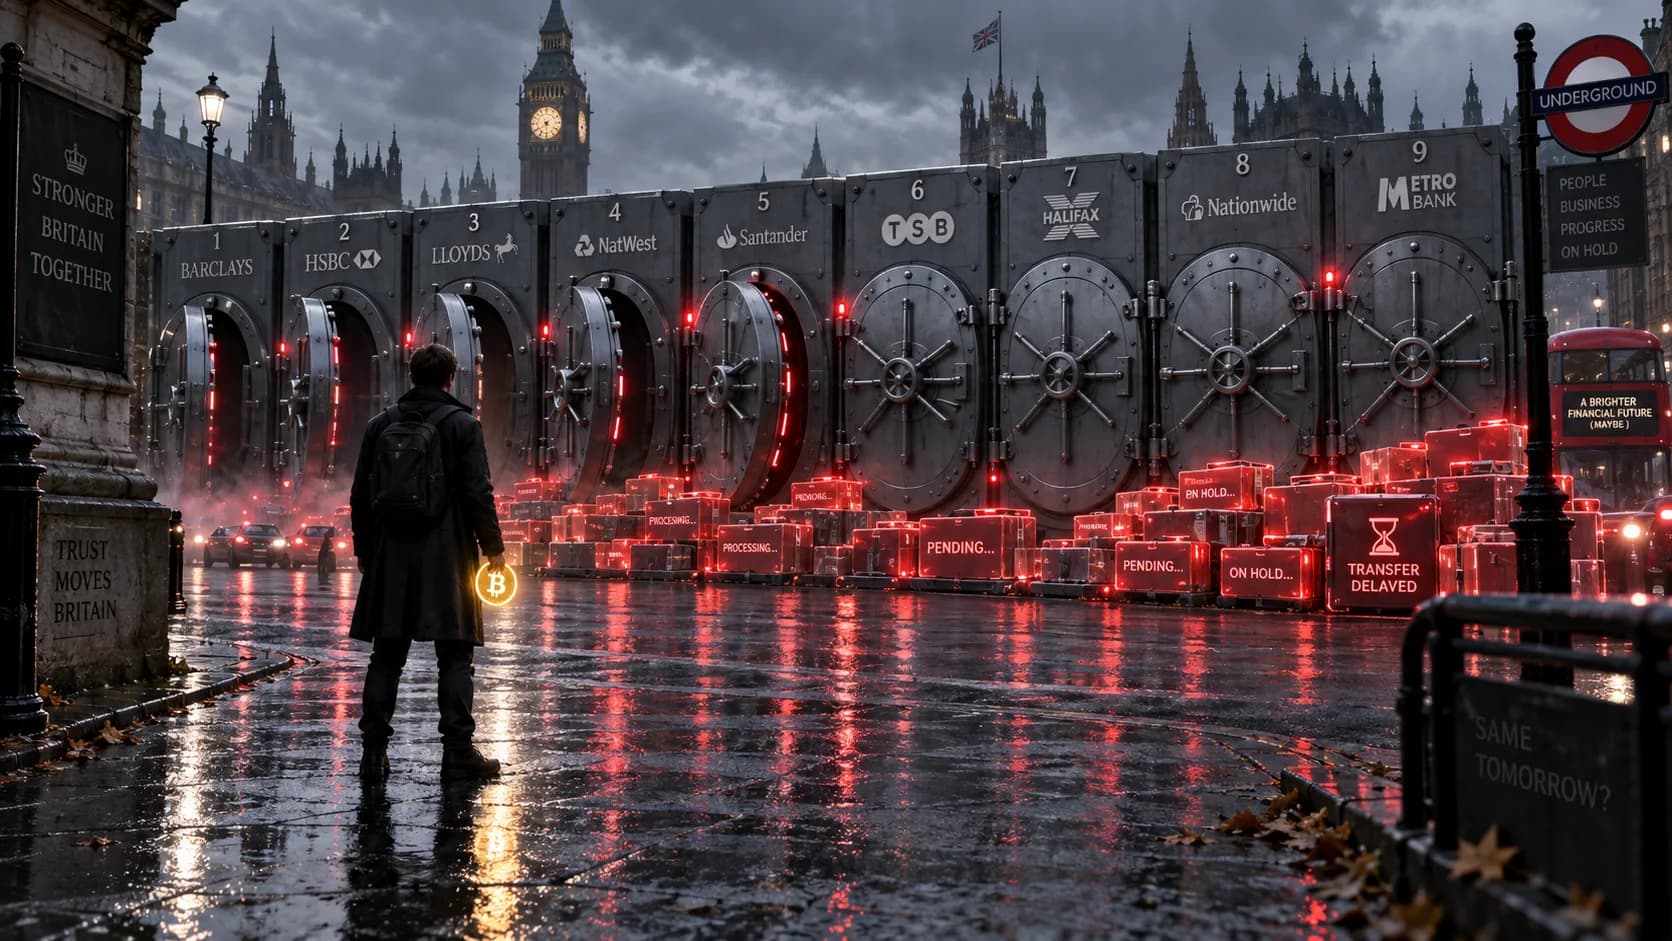
Nine of the United Kingdom's ten largest retail banks now block or restrict transactions to crypto platforms, according to a report shared by WuBlockchain on September 16, 2026. The same report notes that UK retail banks will not be forced to provide services to crypto customers, leaving the decision to each institution's own risk appetite.
The finding puts a hard number on something UK crypto holders have felt for years: their bank is often the first obstacle between a paycheck and an exchange. With nine of the top ten now imposing outright blocks or transfer limits, the friction is close to systemic rather than the choice of a single cautious lender.
The scale of the restriction
A single bank declining crypto payments is a policy quirk. Nine out of ten is a pattern. When most of the mainstream banking sector applies the same brake, retail users lose the practical ability to move money in and out of digital assets through the accounts they already hold. The restrictions reported range from full blocks on payments to crypto exchanges to daily or monthly caps that throttle how much can be sent.
Banks have long justified these measures as fraud prevention. Authorized push payment scams, where a customer is tricked into sending money to a fraudster, frequently route through crypto exchanges, and UK lenders now carry reimbursement liability for many of those losses. Limiting the exposure at the source is the cheaper path for a bank's balance sheet, even if it penalizes legitimate users in the process.
No obligation to bank crypto
The second half of the report matters as much as the first. If banks cannot be compelled to serve crypto customers, then the restrictions are not a temporary technical measure waiting to be reversed by regulators. They are a settled commercial position that the rules currently permit.
This lands as the Financial Conduct Authority continues building out the UK's cryptoasset regime. The FCA issued fresh guidance this week on how the new regulatory framework applies to firms, part of a longer effort to bring crypto activity under formal supervision. A clearer rulebook for licensed crypto firms does not automatically translate into friendlier treatment from the banks that sit upstream of them. The two tracks are moving at different speeds.
The off-ramp squeeze for UK users
For someone in the United Kingdom trying to buy or cash out crypto, the bank block is the point where the plan stalls. Bank transfers are the cheapest and most common funding route for exchanges, and when they are capped or refused, users are pushed toward slower or costlier alternatives: card payments with higher fees, peer-to-peer trades with counterparty risk, or accounts at the smaller banks and e-money firms that still permit the transfers.
Crypto cards sit at the other end of this pipe. A card that spends directly from a wallet or exchange balance sidesteps the need to route funds back through a hostile bank account before spending them. That does not solve the on-ramp problem, since you still need to get money into crypto in the first place, but it changes the exit. UK residents weighing their options can compare what is actually available in the market on our United Kingdom crypto card guide, where availability and fee structures vary widely by provider.
Users should also read the fee print carefully. A card advertised as low-cost can still carry a network spread on the Visa or Mastercard rail, a conversion spread when crypto is sold at the point of sale, and gas costs on any on-chain top-up. The headline number is rarely the full price of spending.
The wider signal
Britain has positioned itself as a jurisdiction that wants regulated crypto activity while its banks quietly wall it off at the retail layer. Both things are happening at once, and the tension is now measurable: nine of ten banks restricting access on one side, an FCA building a licensing regime on the other. The market context is not helping sentiment either. Bitcoin traded around $75,747 on September 16, 2026, down 1.5% on the day and 4.8% over the week, with XRP off 8% in 24 hours, so retail demand is meeting these access hurdles during a soft stretch rather than a rally.
Overview
Nine of the UK's ten largest retail banks now block or limit crypto transactions, and regulators have confirmed banks are under no obligation to serve crypto customers. The result is a narrower set of off-ramps for UK users, arriving alongside a still-forming FCA framework that governs crypto firms but not how banks treat them. For anyone spending crypto in Britain, the practical takeaway is to plan funding and withdrawal routes around bank restrictions rather than assume a standard transfer will clear.