Nexo said on October 13, 2026 that the entry point for its flagship zero-interest credit line fell by 10x for Bitcoin collateral, according to a post from the company's official X account. The change lowers the minimum Bitcoin balance a user needs to open the line, bringing a product that was effectively sized for larger balances within reach of retail holders.
The move lands with Bitcoin at $83,335, up 0.7% over 24 hours but down 2.6% on the week, as of October 13, 2026. A lower entry threshold means more holders can borrow against their coins during a flat-to-soft stretch rather than sell into it.
The mechanics of a borrow-against-crypto line
A crypto-backed credit line lets a holder pledge an asset such as Bitcoin as collateral and draw cash or stablecoins against it without selling the underlying coin. The borrower keeps exposure to any future price upside and avoids triggering a taxable sale, which is the main reason this structure appeals to long-term holders.
Nexo's framing of the product as "zero-interest" refers to its tiered model, where the headline rate depends on how much a user borrows relative to the value of their collateral, known as the loan-to-value ratio. Lower loan-to-value draws sit in the cheapest band. The company's post did not restate the specific terms of that band, so the relevant detail here is the access change rather than a new rate.
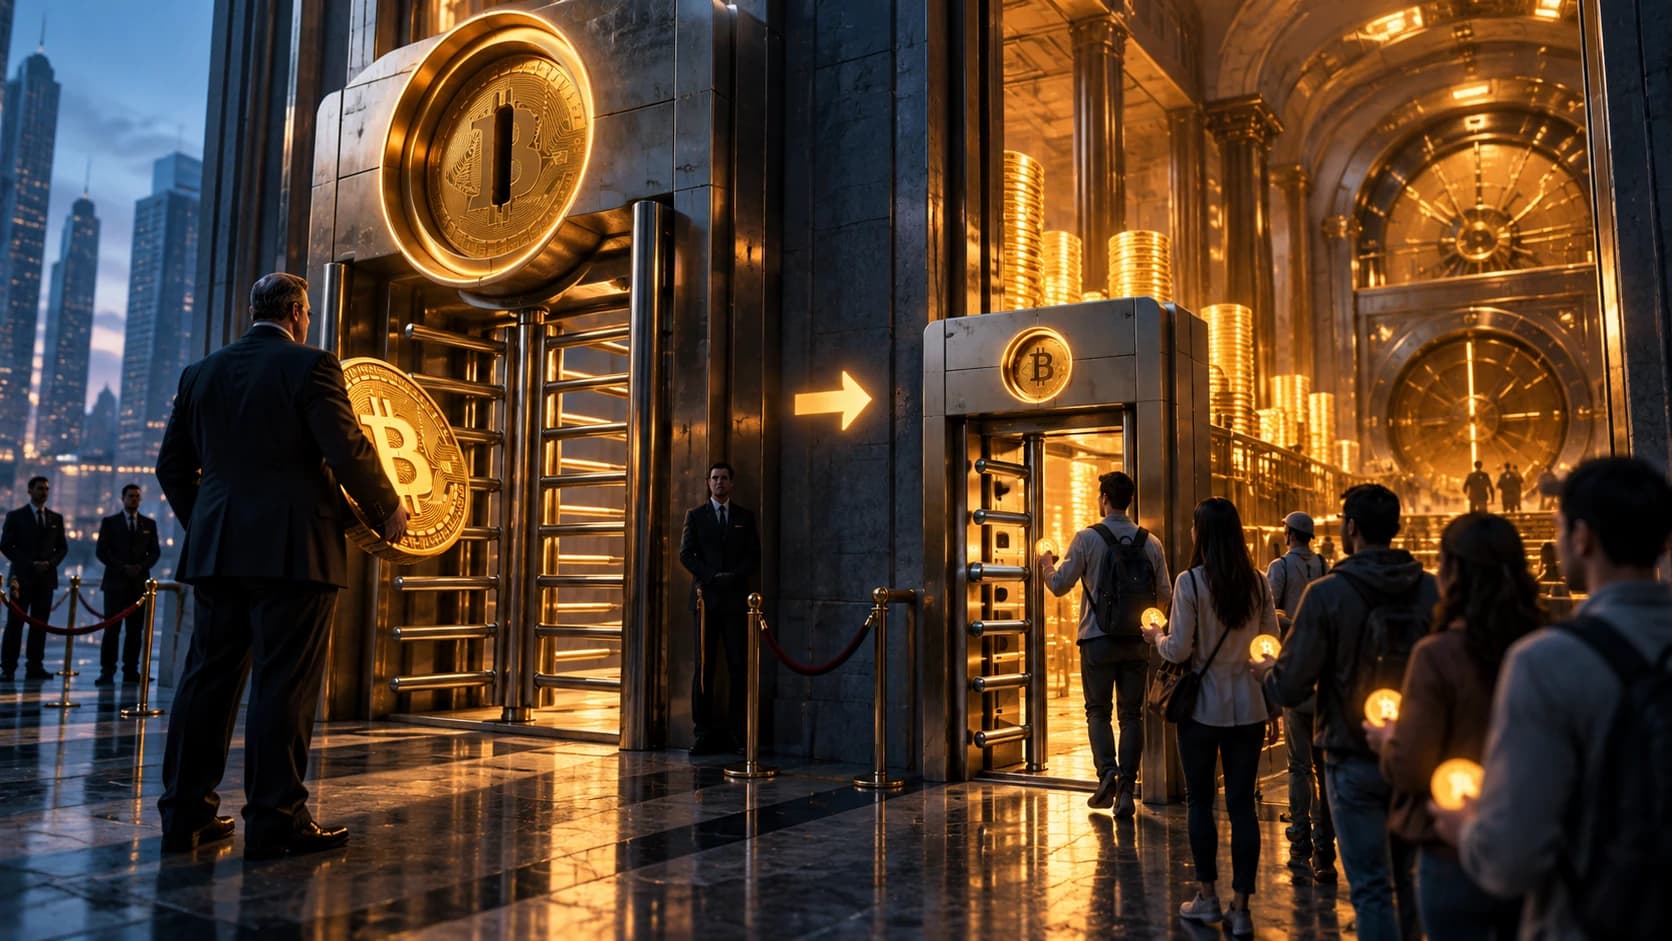
By cutting the Bitcoin entry point 10x, Nexo is widening the top of the funnel. A holder who previously fell short of the minimum collateral can now open the same line with a much smaller stack. For context on where this sits in Nexo's broader card and account lineup, see our Nexo overview.
The liquidation point governs the outcome
The headline most people will read is "zero-interest." The number that actually governs outcomes is the liquidation point.
When you borrow against Bitcoin, the lender sets a loan-to-value ceiling. If BTC falls far enough that your loan grows too large relative to your remaining collateral, the position can be liquidated, meaning the collateral is sold to repay the debt. A smaller holder opening a line near the new minimum has less buffer to post more collateral in a drawdown, which makes them more sensitive to exactly the kind of weekly dip Bitcoin is showing now.
That is the trade every borrow-against-crypto user accepts. The appeal is liquidity without selling. The risk is that a sharp move forces a sale at the worst possible moment, and at a price the borrower did not choose. Lowering the entry bar does not change that math. It just invites more people to run it.
Access versus affordability
Nexo is one of several lenders competing to pull dormant Bitcoin into active use rather than leaving it idle in cold storage. The product category has grown alongside onchain alternatives; Lido recently rolled out a Morpho-based lending market aimed at looping strategies, and borrowing demand tends to track whether holders expect to keep their coins.
A 10x lower entry point is a distribution decision, not a pricing one. It does not reduce what a given loan costs. It reduces how much Bitcoin you need before the door opens. For a holder sitting on a fraction of a coin who wants spending power without a sale, that distinction is the whole story.
There is also a custody dimension worth stating plainly. Collateral posted to a centralized lender sits with that lender. The borrower is exposed to the platform's solvency and to its right to liquidate on its own terms, not just to Bitcoin's price. Readers who want to spend crypto while keeping control of their assets should weigh self-custody options against the convenience of a custodial credit line.
Overview
Nexo lowered the Bitcoin collateral entry point for its zero-interest credit line by 10x on October 13, 2026, per its official X post. The change is about access: smaller Bitcoin holders can now open a line that was previously sized for larger balances. The borrowing rate and the underlying liquidation risk are unchanged. With Bitcoin at $83,335 and down 2.6% on the week, the practical takeaway is that a lower buffer means a thinner margin before a drawdown forces a sale. Borrowing against crypto keeps your upside and avoids a taxable sale, but it hands custody and liquidation control to the lender. Check the loan-to-value band and the liquidation threshold before pledging any coin.