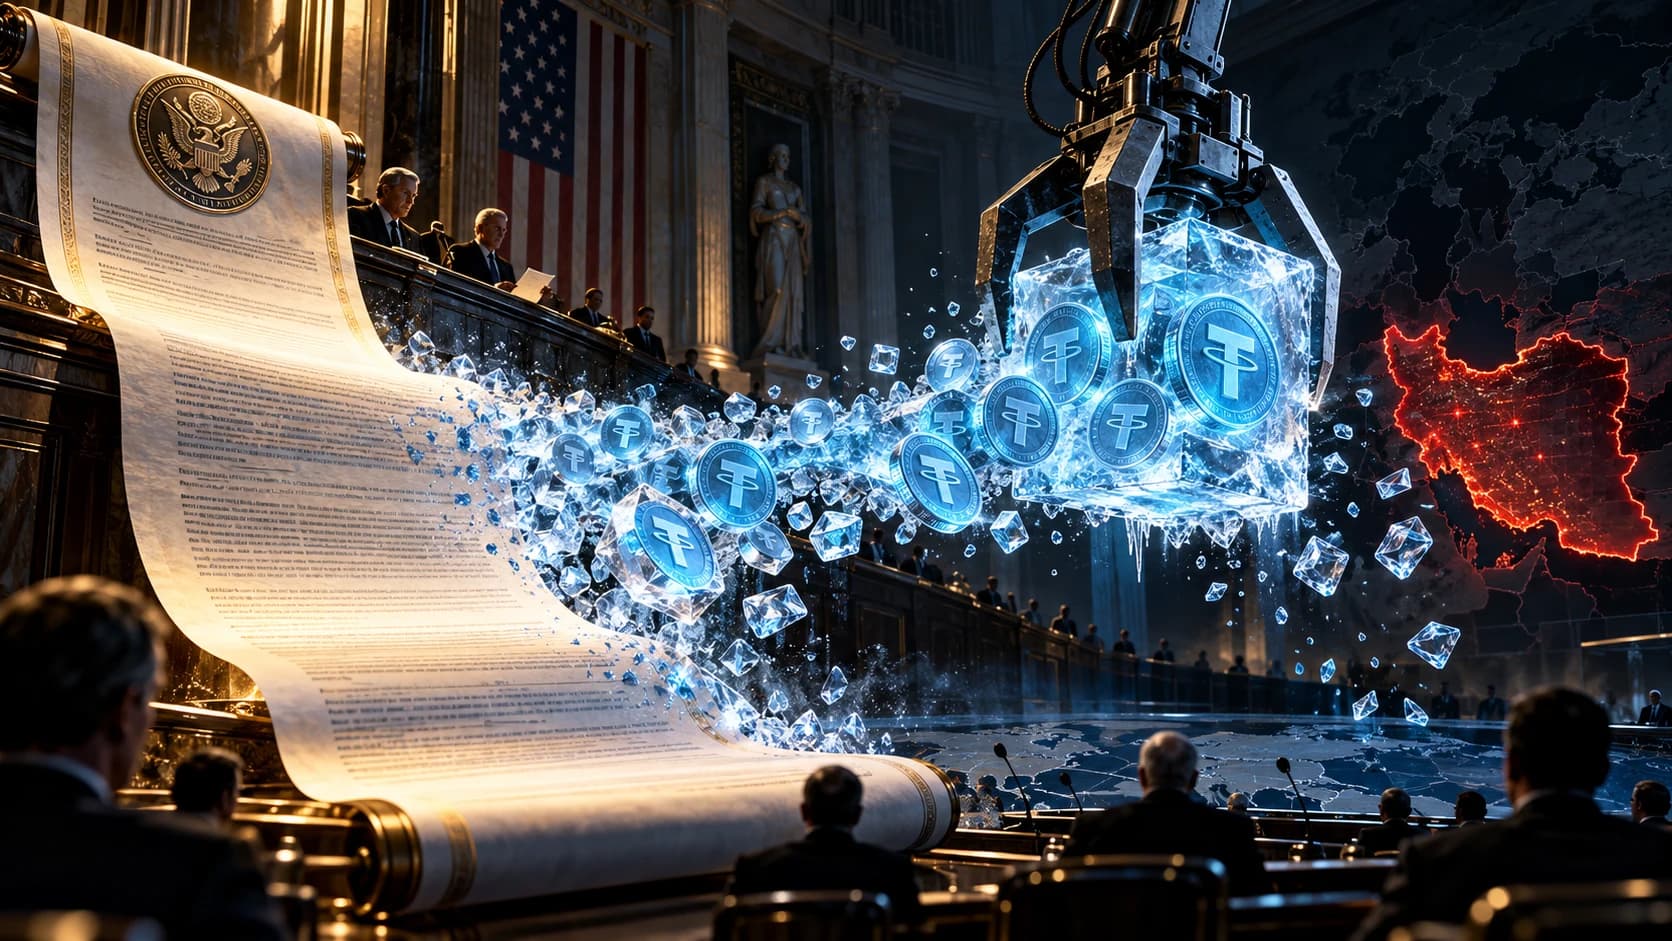
Tether is contesting a US Senate report that ties its USDT stablecoin to Iranian sanctions evasion. CEO Paolo Ardoino responded publicly on October 19, 2026, arguing that the company freezes suspect wallets well before formal sanctions land, and that Iran-linked stablecoin volume has fallen 94% since 2023. The exchange came after a Senate Democrats report, released September 28 and presented by Senator Richard Blumenthal, examined 846 sanctioned wallets with Iranian links and found that 84% primarily moved USDT.
The numbers behind the dispute
The Senate report's core claim is concentration: of the Iran-linked sanctioned addresses it studied, the large majority ran on Tether's dollar token rather than any competing stablecoin. That figure is the basis for the accusation that USDT has become the default rail for actors trying to route around US and allied restrictions.
Ardoino's rebuttal does not contest that sanctioned entities have held USDT. It reframes the timeline. According to his response, Tether froze the relevant addresses an average of four weeks before sanctions arrived from the US Treasury's Office of Foreign Assets Control and Israel's National Bureau for Counter Terror Financing. He also said Tether's internal flagging beat Chainalysis labeling in 99% of the cases cited. The company reported helping freeze close to $550 million in Iran-associated USDT across 2026.
The two sides are measuring different things. The Senate report counts which token sanctioned wallets used. Tether counts how quickly it cut those wallets off. Both can be accurate at once, which is why the dispute is less about the raw data and more about what the data proves.
A centralized kill switch, by design
The freeze mechanism at the center of the argument is a feature of how USDT works. Tether can block transfers and immobilize balances on specific addresses because it controls the contract that issues the token. That capability is what lets the company claim it acts faster than regulators. It is also what distinguishes a centrally issued stablecoin from a permissionless asset like Bitcoin, where no single party can reverse or halt a transaction.
That control cuts both ways. The same switch that freezes an Iran-linked wallet before OFAC names it is the switch critics point to when they argue a private company is making unilateral calls about whose money moves. Tether's position is that it uses the switch aggressively and early, and the 94% volume decline is its headline evidence.
Washington keeps circling Tether
This is not a one-off skirmish. Tether has spent 2026 as a recurring target of US scrutiny, from questions about its reserves to its political connections. A Senate report carrying a specific, quantified accusation raises the stakes because it feeds directly into the legislative debate over how dollar-backed stablecoins should be supervised.
USDT sits at the center of that debate for a simple reason: scale. It is the most widely held stablecoin in circulation and underpins a large share of crypto trading and cross-border transfer volume. The same reach that makes it the backbone of dollar liquidity in markets with limited banking access is what makes it attractive to actors under sanctions. Any serious rule-making on stablecoins has to account for both at once.
For readers who hold or spend stablecoins, the practical takeaway is the counterparty relationship. A balance in a centrally issued token is subject to the issuer's compliance decisions. Tether is presenting that as a strength here, pointing to early freezes as proof it polices its own network. The Senate report presents the same centralization as a risk vector. Neither framing changes the underlying fact: with USDT, the issuer can freeze funds, and it does.
The open question
The report and the response leave the central policy question unresolved. Fast private freezes can be read as effective self-policing or as evidence that a single issuer now shoulders enforcement work that belongs to governments. Ardoino is betting on the first reading and has the volume data to support it. Blumenthal's report rests on the second.
Tether's $550 million in Iran-linked freezes during 2026 is the figure both sides will keep returning to. To Tether it is proof of action. To the Senate it is proof of exposure. The next move belongs to lawmakers deciding whether stablecoin legislation should lean on issuer compliance or build enforcement that does not depend on a company flipping its own switch.
Overview
Tether's Paolo Ardoino rejected a September 28 Senate Democrats report, led by Senator Blumenthal, that found 84% of 846 Iran-linked sanctioned wallets used USDT. His defense cites freezes averaging four weeks ahead of OFAC action, a 94% drop in Iran-linked stablecoin volume since 2023, and roughly $550 million in Iran-associated USDT frozen during 2026. The disagreement turns on interpretation: the same centralized freeze power is framed as self-policing by Tether and as a risk by the Senate.